Tag Archives: institutional density

No Group Works Less for Itself Than African Americans: Just 8% of Black Workers Are Employed by Black-Owned Firms

“When an African American earns $1.00 with our labor, there is an owner that earns $1.20 in operating income from ownership of the vessel and they get to count said vessel as an asset. This means when we do not work for firms from our own community, then the bulk benefit of our talents are still rewarding Others. That reality does not change whether we are earning $80,000 or $8 million. Individual talents are always building up institutional wealth, the question is for our own community or someone else’s.” – William A. Foster, IV
A river does not ask where its water goes. It simply runs, cutting canyons, carrying silt, turning turbines wherever the engineers have built them. For a hundred years, a river ran through a valley and lit every town along its banks, except the town it rose from. That town kept its lanterns. It sent its water downstream and called the arrangement progress, because the workers who built the dam drew a wage, and a wage, everyone insisted, was the same as owning the river. It was not until the town tried to build its own turbine that it discovered the difference: a wage ends when the shift ends. A turbine keeps generating current long after the worker who built it has gone home.

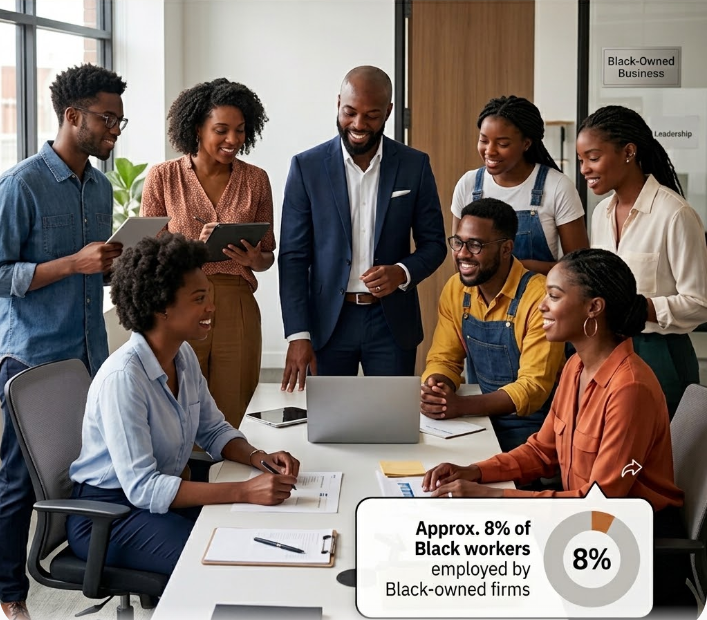
That difference between generating value and owning the mechanism that captures it is the entire story embedded in a figure from Pew Research Center’s analysis of federal business data that ought to stop every Black economist and institution builder in their tracks: Black-owned employer firms in the United States employed roughly 1.6 million workers in 2022, with annual payrolls estimated at $61.2 billion, according to Pew’s review of Census Bureau survey data. Set against the more than 20 million Black Americans in the labor force, that 1.6 million figure is not a success statistic. It is a containment statistic. No group in America works less for itself than African Americans and not because Black workers labor any less than anyone else, but because so little of what that labor builds accrues to institutions Black America actually owns. The river runs. The valley stays dark.

The economist Claud Anderson gave this dynamic its plainest possible name three decades ago in Black Labor, White Wealth: The Search for Power and Economic Justice, arguing that American wealth was built substantially on Black labor under slavery and Jim Crow and has been sustained since through policy and practice that keeps that labor’s output flowing into someone else’s balance sheet rather than its own. Anderson’s proposed remedy, which he later formalized through his organization, the PowerNomics Corporation of America, was not a moral appeal either it was a group-economics strategy aimed squarely at ownership and capital control rather than participation and goodwill. The employment and ownership figures that follow are the modern receipts for exactly the imbalance Anderson named in 1994, updated with three additional decades of federal data that show the imbalance persisting in remarkably precise form.

This is not a moral argument. It is a capacity argument, and the distinction matters, because HBCU Money has never found the moral case persuasive to the people who control capital allocation, and neither should we expect it to be. The self-interest case is the only one that survives contact with a boardroom: an ecosystem that does not own the firms employing its own labor cannot retain the capital that labor generates, cannot direct where that capital gets reinvested, and cannot build the institutional density required to negotiate as a bloc rather than beg as individuals. Ownership is not a symbolic preference. It is the only mechanism by which labor output converts into compounding capital instead of a paycheck that clears and disappears.

Start with the scale problem, because it is worse than the employment figure alone suggests, and it is worse specifically relative to every other ownership group tracked by the federal government. According to the U.S. Census Bureau’s most recent release on business owner characteristics, Black or African American-owned firms account for 3.4% of U.S. employer businesses, up from 2.7% just two years earlier per Brookings’ analysis of the Annual Business Survey — real movement, but movement from a base so small it barely changes the fundamental picture. Put the ownership share next to the population share and the comparison sharpens considerably: Brookings researchers Andre Perry, Manann Donoghoe, and Hannah Stephens found that in 2021, white Americans owned 82% of employer businesses while representing 72.5% of the population, its ownership exceeding population share by nearly ten points. Asian Americans owned 10.9% of employer businesses against a 6.3% population share — again, ownership exceeding population. Black Americans owned 2.7% of employer businesses against a 14.4% population share, and Hispanic or Latino Americans owned 6.9% against a 19.1% population share, both groups locked well below proportional representation, with Black America carrying the widest gap of any racial category Brookings measured. That is not a rounding error. It is a four-to-one to five-to-one density gap between population share and ownership share depending on which year you measure, and it is the single most important number in this entire conversation, because density is what everything else depends on.

The size distribution inside that 3.4% makes the containment tighter still, and here the comparison across ownership groups is unusually clean because the federal data measures the same thing the same way for everyone: what share of each group’s businesses employ nobody at all. Per the same Brookings analysis of Census sole-proprietorship data, Black-owned businesses are the most concentrated of any racial group at that zero-employee scale where 96.3% are sole proprietorships with no paid staff, compared with 92.4% for both Hispanic/Latino-owned and Native American-owned firms, and 81.1% for white-owned firms and 80.1% for Asian American-owned firms. Run the comparison from the employer side and, per Pew’s analysis, it holds just as tightly: about seven-in-ten Black-owned employer firms had between one and nine employees in 2022, a concentration at the smallest possible operating scale that leaves the ownership tier structurally unable to absorb meaningful shares of the available Black labor force even if every one of those firms doubled tomorrow.

The dollar-value version of the same gap is, if anything, more damning, because it isn’t about headcount at all, it’s about what each firm is actually worth once it exists. Using the Census Bureau’s most recent figures, white-owned employer firms generated roughly $17.0 trillion in combined receipts across 4.8 million firms, an average of about $3.5 million in receipts per firm. Black-owned employer firms generated $249.0 billion in combined receipts across 201,000 firms, an average of roughly $1.2 million in receipts per firm, meaning the typical white-owned firm generates nearly three times the revenue of the typical Black-owned firm. Asian-owned firms averaged about $1.75 million per firm and Hispanic-owned firms about $1.47 million, both ahead of the Black-owned average as well.

Two further measurements explain why that revenue gap exists rather than merely documenting that it does, and both point to the same conclusion Anderson reached in 1994: the constraint is access, not capacity. The first is sector composition. Per Pew’s sector breakdown, Black-owned employer firms are concentrated in health care and social assistance (26% of all Black-owned firms), professional and scientific services (14%), transportation and warehousing (9%), administrative and waste management services (8%), and retail and food service (7% each) — sectors that require comparatively little startup capital and generate correspondingly modest revenue per firm. Black ownership is nearly absent from the industries that produce the highest revenue per firm precisely because those industries — utilities, wholesale trade, heavy manufacturing — demand the largest upfront capitalization to enter at all; Brookings researchers note that a 2018 federal survey recorded a total of just 18 Black-owned businesses nationally in the entire utilities sector. Economist Robert Fairlie’s research for the National Bureau of Economic Research finds the same pattern from a different angle: roughly 18% of Black workers are employed in innovation-intensive industries compared with 22% of white workers, and even among Black workers already employed inside them, only about 9% go on to own a business in that industry compared with roughly 14% of white workers in the same position. Tellingly, a study by the Initiative for a Competitive Inner City found that where Black-owned manufacturers do exist inside tracked supply chains, they are on average larger than the white-owned manufacturers in those same chains, the clearest available evidence that this is a barrier to entry, not a deficit of competence, ambition, or business acumen.

The second measurement is the investor class itself, and here the gap dwarfs everything discussed so far. Per Crunchbase data, Black-founded startups received roughly 0.4% of all U.S. venture capital in 2024, down from a 2021 peak of 1.3%, and according to HBCUvc’s quarterly funding tracking, only 17% of Black-founded deals that do get funded reach a Series A round, compared with 37.7% of funded deals overall meaning the small number of Black-founded firms that clear the first hurdle are roughly half as likely to clear the second one. The lending side of the ledger shows the identical pattern in a different market: the Federal Reserve’s Small Business Credit Survey finds Black-owned firms denied credit at roughly 39%, more than double the 18% denial rate for white-owned firms, and a 2021 Federal Reserve Bank of New York report found Black-owned firms independently rated low credit risk were approved for full financing at close to the same rate as high-risk white-owned firms.

But the venture and lending statistics both describe capital that a firm is applying for from someone else. The layer underneath both of them is capital a founder never has to apply for at all, because it comes from their own household or their own network before any bank or investor is ever approached and this is where the wealth gap already documented in this piece does its most permanent damage. According to Google for Startups’ own reporting on the pre-seed funding gap, the average U.S. startup launches on a friends-and-family round of $100,000 to $150,000, drawn from founders’ personal savings and the people closest to them; for Black founders, that figure averages closer to $35,000. Measured on a liquid-wealth basis stripping out home equity, since a house cannot be cashed out to fund a check, a 2023 analysis by Fifth Star Funds put the white-to-Black wealth ratio at roughly twenty-two-to-one, meaning a Black founder trying to raise a typical $23,000 friends-and-family round would need to draw on the entire liquid wealth of six Black families to do it. A firm that cannot clear this round never reaches the point of being denied a bank loan or passed over by a fund; it simply launches undercapitalized, if it launches at all, and stays capped near sole-proprietor scale for the rest of its life which is a large part of why it stays there. The historical contrast needs no editorializing: Bloomberg’s reporting on Amazon’s founding, later summarized by Newser, found Amazon’s 1995 seed round included $245,573 personally invested by Jeff Bezos’s own parents, Jackie and Mike Bezos. And per multiple retellings of Google’s founding, including Celebrity Net Worth’s account of its earliest investors, Google’s first outside money, three years later, arrived as $100,000 personal checks from Stanford computer science professor David Cheriton and Sun Microsystems co-founder Andy Bechtolsheim, written before the company was even legally incorporated, followed within weeks by a $250,000 personal investment from Bezos himself. No institution of any kind was involved in either case. The capital that mattered most was already sitting in a family’s bank account.

The handful of Black-led investment vehicles that do exist compound this problem rather than solve it, and the reason is worth stating plainly rather than glossing over: Black households cannot yet supply enough investable wealth to anchor those funds as limited partners, and Black institutions — banks, credit unions, HBCU endowments, pension-adjacent capital pools — are not yet large enough collectively to do it either. A Black general partner running a fund capitalized primarily by Others’ foundations, endowments, and pension systems has changed who makes the investment decisions without changing who ultimately owns the return, which means fund formation at the top of the capital stack and household wealth at the bottom of it are not two separate problems. They are the same institutional density gap, expressed at two different altitudes.

Five separate measurements now point at the same wall: Black-owned firms are underrepresented in raw count relative to population, overrepresented at the smallest employee-size tier, smaller in average dollar value, concentrated in the lowest-capital sectors, and shut out of the personal, venture, and institutional capital that would move a firm generating $1.2 million in revenue toward the $3.5 million white-owned average. Five measurements, one underlying constraint.

The historical context here is not ancient, and it runs on two tracks that arrive at the same conclusion from different directions. Where Anderson traced the mechanism backward through slavery and Jim Crow policy, the sociologist Thomas Shapiro traced it forward through household balance sheets a decade later, arguing in The Hidden Cost of Being African American that income and wealth are not the same variable, and that the persistence of racial inequality runs through the asset side of the ledger rather than the wage side. Employment, even full employment, even rising Black employment, does not close a wealth gap if the employer capturing the surplus value of that labor sits outside the community. This is precisely why the Federal Reserve’s Survey of Consumer Finances, as analyzed by the National Community Reinvestment Coalition, shows the gap widening in dollar terms even as it narrows in percentage terms: median Black household wealth rose from roughly $28,000 to $44,900 between 2019 and 2022, but median wealth overall rose enough that the absolute gap between Black and white households actually grew by nearly $50,000 over the same period. By 2022, the median white household held $284,310, more than six times the $44,100 held by the median Black household. Labor income is necessary. It has never been sufficient. A wage is a flow; a firm is a stock. You cannot out-earn a four-to-one ownership density gap through salary alone, no matter how many Black workers show up for shifts at other people’s companies.

There is a growth signal worth taking seriously here, and HBCU Money should not undersell it even while insisting the baseline remains inadequate. Per Census Bureau data reported by Governing, the number of Black-owned employer businesses grew nearly 57% between 2017 and 2022, and Black-owned firms accounted for more than half of all new employer businesses started nationally in that period. In the most recent year-over-year comparison available across all racial groups, Brookings found Black-owned employer businesses posted the largest percentage increases in employee count, revenue, and payroll of any group tracked employee growth of 7%, revenue growth of 30%, and payroll growth of 27%, each figure running 5 to 10 percentage points ahead of white, Asian American, and Hispanic firms over the same year. Formation is not the same as capacity, however, and the arithmetic of closing a base this small is unforgiving: Brookings analysts estimate it would take roughly 700,000 additional Black-owned employer firms to bring ownership into line with Black population share, representing an estimated $800 billion in additional revenue and 6 million additional jobs and that at the pace of the single best growth year on record, full parity remains roughly 100 years away.

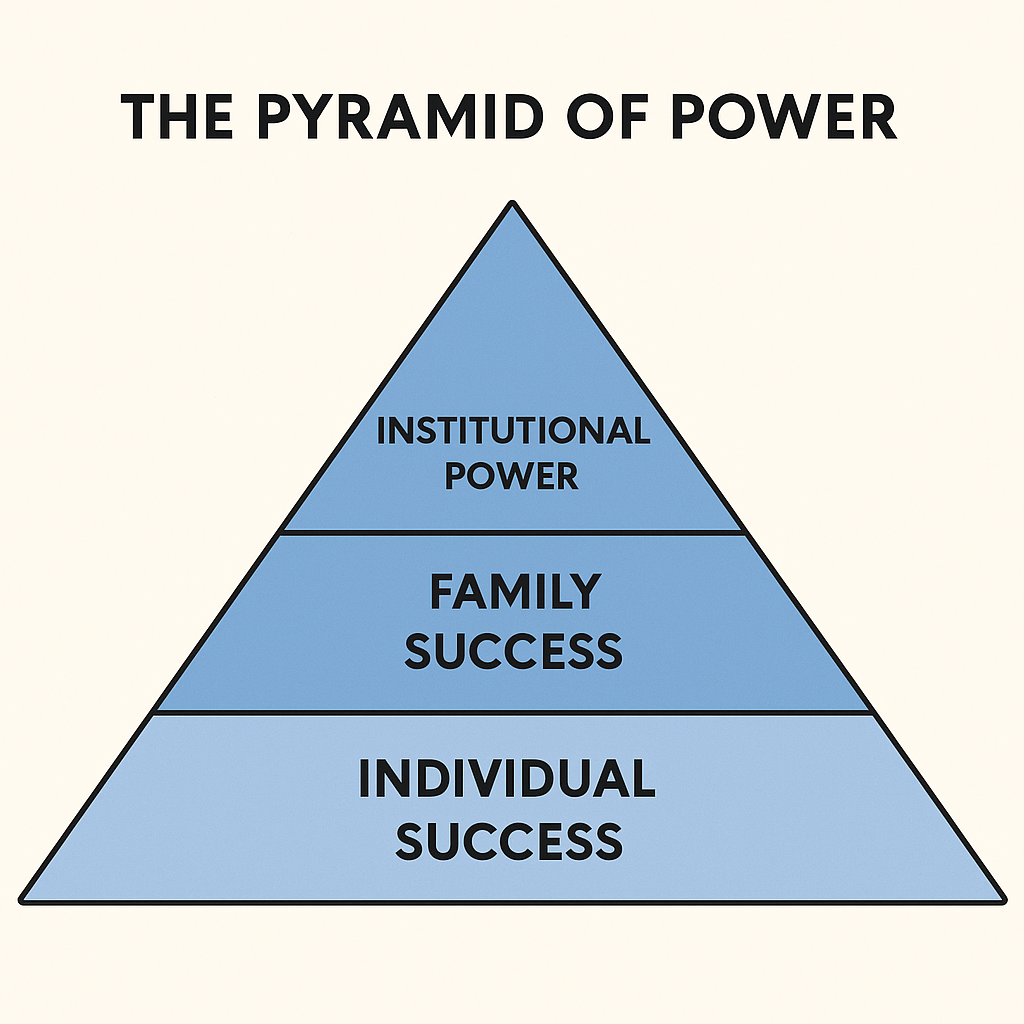
The strategic implications follow directly from the density problem, and this is where the four throughlines this publication returns to — institutional density, capital retention, talent concentration, and strategic coordination — stop being abstractions and start functioning as a diagnostic. Institutional density is the root constraint: 201,000 Black-owned employer firms against 5.9 million total U.S. employer firms, per the Census Bureau, means the ecosystem simply does not have enough vessels to hold its own labor, and those vessels that do exist are smaller both in headcount and in revenue than their counterparts in every other ownership category and are locked, disproportionately, into the sectors and financing markets least able to change that. Capital retention fails as a direct downstream consequence. Talent concentration is the third casualty: the most capable Black managers, engineers, and operators in the country are overwhelmingly employed inside institutions Black America does not control. And strategic coordination; the ability to move Black labor, Black capital, and Black institutional leadership as a single directed force, precisely the coordination Anderson’s PowerNomics called for cannot exist at scale when the typical Black-owned firm is roughly a third the revenue size of the typical white-owned firm, is concentrated outside the industries capable of scaling, has almost no access to personal, venture, or institutional growth capital, and when 92 of every 100 Black workers punch in somewhere the community has no ownership stake in the firm.

This is where the banking and credit union infrastructure this publication tracks obsessively becomes the actual lever, not a side note though it is now clear that lever needs a second one built alongside it. According to HBCU Money’s own 2025 African American-Owned Bank Directory and African American-Owned Credit Union Directory, there are 17 African American-owned banks in the country holding roughly $6.72 billion in combined assets, and 205 African American-owned credit unions holding roughly $8.15 billion across nearly 727,000 members, a combined $15 billion in institutional balance sheet capacity sitting underneath a labor force generating tens of billions in annual wages that mostly clears through mainstream white-owned lenders instead. Only a small fraction of HBCUs and PBIs themselves bank with African American-owned institutions, per that same directory data, a fact that should embarrass every finance department at every one of the 100 plus federally designated HBCUs and PBIs. But deposit infrastructure alone cannot close the sector-composition gap, the friends-and-family gap, or the institutional-capital gap, those require a growth-equity layer this ecosystem still largely lacks, and building it will require Black institutional balance sheets to grow enough to anchor it themselves, not simply put a Black name on someone else’s money.

Business schools at institutions like Fort Valley State, Chicago State, Grambling, and Norfolk State are training a pipeline of Black finance, accounting, and management talent every year, talent that overwhelmingly gets absorbed into the same non-Black employer base generating the 1.6 million versus 20 million imbalance Pew’s data documents in the first place. The concrete institutional solution is not a slogan about entrepreneurship; it’s coordination between four things that currently operate as strangers to each other: the HBCU business school pipeline producing operators, the $15 billion Black bank and credit union balance sheet capacity that can underwrite working capital, an equity and growth-capital layer purpose-built and Black-capitalized to move firms out of the lowest-capital sectors and into the high-revenue ones currently closed to them, and the roughly 200,000 existing Black-owned employer firms that need all three of those pieces to grow past the headcount ceiling, the revenue ceiling, and the sector ceiling that currently trap the median firm below every comparable ownership group.

The employment share figure — 1.6 million out of a labor force many multiples that size — is not a statistic to mourn. It is a target with a number attached, and the comparative data makes the target legible in five dimensions at once: more firms, larger firms, firms worth more per dollar of revenue, firms operating in higher-capital sectors, and firms with actual access to the capital — personal, venture, and institutional — that funds growth. Anderson named this arrangement in 1994. The federal government has spent every year since generating the receipts that prove him right. No group works less for itself than African Americans; not for lack of labor, and not for lack of the firms willing to try, but for lack of the sectors, the capital, and the institutions built to keep that labor’s output at home.

Disclaimer: This article was assisted by ClaudeAI.
HBCU Alumni Have a Profound Reason to Support Dolly Parton’s Imagination Library — and It Isn’t Charity

 “If I’m remembered 100 years from now, I hope it will be not for looks but for books.” – Ms. Dolly Parton

Every homecoming, a knot of alumni takes the same walk back onto campus past the same block, the same porches, the same children playing in yards a few hundred feet from the gates they once walked through themselves. Most years they don’t really see them. They’re thinking about the game, the cookout, the faces they haven’t seen since spring. But those children live only steps from the campus that shaped them, closer than any of them ever stopped to notice while they were students there. Their future and the institution’s are already tangled together whether anyone admits it or not. Some of them will never walk through those gates themselves — not for lack of promise, but because no one made sure they could read well before they turned six, and by the time it shows up as a problem, everyone treats it as someone else’s failure to fix. A fence line, or sometimes just a street, is all that separates the campus that made them from the community raising the children who could be next. This year, walking that same route, one of them finally says it out loud. By Monday, the group has pulled the zip code. It’s already moving through the group chat; who’s in, who’s giving what, who’s setting up the recurring charge tonight. Each of them commits to a standing monthly gift, on their own, no chapter paperwork needed. By next year’s homecoming, they’re not just showing up, they’re telling everyone else in that same group chat’s orbit to do the same.

That is the structural story hiding inside a straightforward piece of philanthropic news. On August 25, Dolly Parton died at 80 after a battle with cancer, and within hours her Imagination Library, the nonprofit that has mailed more than 300 million free books to children from birth to age five since 1995, pledged to continue operating without her. It has strong reason to reassure the public. In the months before her death, Indiana and Missouri, two of the program’s largest state partners, cut a combined $10 million in public funding, and the effects were immediate: Missouri froze new enrollment on July 1 after lawmakers cut its allocation from roughly $6 million to $2 million, and Indiana dropped a $6 million two-year commitment that had reached more than 152,000 children, about 37 percent of the state’s under-five population, leaving a private fundraising campaign to close the gap.

It is worth being precise about why this particular loss registers differently across Black America than the death of most entertainers would. Parton’s standing in Black communities was not incidental goodwill; it was built through specific, repeated decisions over four decades. When Whitney Houston’s 1992 cover of “I Will Always Love You” generated an estimated $10 million in royalties for Parton, she used part of that windfall to purchase a commercial complex in a predominantly Black Nashville neighborhood, a property she later called, in her own words, “the house that Whitney built.” She was among the first public figures to advocate openly for people living with HIV and AIDS in the 1980s, when the subject carried real professional risk. In 2020 she voiced unambiguous support for the principle behind Black Lives Matter, and that same year donated $1 million to Vanderbilt University Medical Center toward coronavirus research that fed into the Moderna vaccine, a contribution not framed as racial-justice philanthropy but one that mattered disproportionately to Black communities carrying a disproportionate share of COVID-19’s toll. When Beyoncé reworked “Jolene” on Cowboy Carter in 2024, Parton publicly welcomed it rather than guarding the song as untouchable. Her death drew tributes from Black cultural and political figures across generations, including the nation’s first Black president. None of that history makes the Imagination Library a Black institution, and this publication has no interest in overstating it. But it explains why the erosion of one of her signature programs is being felt in Black America as something closer to institutional loss than celebrity news and why the ecosystem she consistently, unsentimentally invested in is well positioned to be the one that protects what she built.

The Imagination Library’s funding architecture is worth understanding before arguing that HBCU alumni should engage with it. The Dollywood Foundation covers national administrative overhead; local partners; usually a nonprofit, library system, or community foundation, fund the actual books and postage for their coverage area; and in many states, a public appropriation matches what the local partner raises, typically on a fifty-fifty basis. This is a genuinely decentralized model, closer in structure to a franchise network than a single national charity, and it is precisely because of that structure that state-level political decisions can gut service in one place while leaving it untouched in another. Missouri’s cut is the sharper illustration: in 2024 the state became the first in the country to fully fund the program, delivering 1.9 million books in a single year, and this year’s reduction converted a national model program into a waitlist. Indiana’s cut removed the largest state contribution the program had, and while the governor’s wife has since run a private campaign that had reached roughly 90 percent of its two-year replacement goal by March, the shortfall illustrates a pattern this publication has tracked in other contexts: public commitments to Black and working-class communities are frequently the first line item removed when budgets tighten, and private philanthropy is expected to backfill on short notice with no guarantee of permanence.

This is where the moral case for giving; that literacy is good, that children deserve books, that Parton’s legacy is worth honoring should give way to a structural case, because the moral case, while true, does nothing to explain why HBCU alumni specifically should act, or why they should act through this program rather than any other worthy cause competing for the same dollar. The structural case is that early childhood reading proficiency is the first stage of the same talent pipeline that HBCU admissions offices, endowments, and surrounding local economies depend on decades later. The Annie E. Casey Foundation has found that students who are not reading proficiently by the end of third grade are four times more likely to leave high school without a diploma than proficient readers, and shared reading in the earliest years has been identified in the pediatric research literature as one of the most effective levers for building the school-readiness skills that predict later outcomes. Every child in a majority-Black zip code who fails to reach third-grade proficiency is a young person the institutional ecosystem has effectively lost before that child ever applies anywhere; not lost to a rival university, but lost to a structural gap that formed a decade earlier and was never someone’s assigned responsibility to close. HBCUs sit inside this pipeline whether their leadership treats it that way or not. A campus’s long-run enrollment base, its local labor pool, its alumni base twenty years out, and the tax and consumer base of the surrounding Black community are not separable from the reading outcomes of five-year-olds currently living within a few miles of the quad.

Framed this way, the Imagination Library’s donation mechanics stop being incidental and start being a genuine instrument of capital retention. The donation platform allows a donor to designate a gift to a specific Local Program Partner, either by selecting one directly or by entering a zip code or postal code, which routes the contribution to the affiliate serving that address rather than into an undifferentiated national pool. An alumnus of Fisk can direct dollars into Nashville. An alumnus of Grambling State can direct dollars into Lincoln Parish. An alumnus of Alcorn State, Fort Valley State, or Cheyney can direct dollars into Lorman, Fort Valley, or the Brandywine Valley rather than into whichever state happens to have the most visible fundraising campaign that year. This matters because the HBCU ecosystem’s chronic capital-retention problem is not only about tuition dollars or philanthropic gifts leaving the ecosystem for PWIs it is also about diffuse, well-intentioned giving that never lands in the specific towns and neighborhoods that make up the extended HBCU footprint. A general donation to a national children’s literacy charity is a fine act of citizenship. A designated donation, tied to the zip code of one’s own institution and repeated as a recurring monthly gift, is an act of institutional infrastructure-building indistinguishable in kind, if not in scale, from an endowment gift or a scholarship fund. It should be treated by advancement offices the same way: as a designated giving category, marketed alongside scholarships and building funds, not left to individual alumni to discover on their own.

Before any of this can be marketed with confidence, it needs verification, because the network’s coverage is uneven by design. Not every zip code has an active Local Program Partner (check with Imagination Library), and a well-intentioned designated gift to an HBCU’s host community will simply fail to route if no affiliate exists there yet. Alumni associations and institutional advancement offices should check availability for their specific campus community before building a giving campaign around it, and where no local affiliate exists, the more consequential action may be organizing one; approaching a local library system, community foundation, or the institution itself about becoming a Local Program Partner, which would let the university’s home community capture matching state or philanthropic dollars rather than simply mailing checks into someone else’s affiliate. That is a heavier lift than a donation button, but it is the difference between renting a spot in someone else’s infrastructure and building a permanent piece of one’s own, a distinction the HBCU ecosystem has learned to care about in banking, in real estate, and in research capacity, and should extend to children’s literacy as well.

There is a natural, if imperfect, partner already sitting inside the ecosystem for this work: the HBCU Library Alliance, a membership consortium of HBCU academic libraries built around preserving Black historical and cultural collections, developing library leadership, and building digital archives, with active Mellon Foundation support for financial capacity-building and NEH backing for humanities collections work. Its formal mandate is academic library infrastructure, not early-childhood book distribution, and this publication has been consistently corrected on the danger of assigning capabilities to institutions that do not actually have them so it would be inaccurate to describe the Alliance as an operator of childhood literacy programs or a grantor with authority over Imagination Library funding decisions. What it plausibly can do, sitting where it does inside the ecosystem, is convene. Its member libraries are physically embedded in or near the same host communities alumni would be donating into, and a consortium built around expanding access to books and preserving Black intellectual life is a natural venue for publicizing zip-code-designated giving campaigns to alumni networks, tracking which member institutions’ communities have active local affiliates and which have coverage gaps, and lending its existing credibility with member library directors to conversations with local governments and foundations about establishing new affiliates in underserved HBCU towns. None of that requires new statutory authority or grant capacity the Alliance does not have. It requires treating the organization as what it already is: a coordination point for the library infrastructure of the HBCU ecosystem, extended one step further to include the earliest readers who will eventually walk into those same libraries as students.

The broader pattern here is not new, even if the specific instance is. Public commitments to reading infrastructure in under-resourced and disproportionately Black communities have proven, across states and across administrations, to be among the more fragile line items in a state budget — vulnerable to a single legislative session in a way that private, community-anchored infrastructure is not. Books and reading are not merely contested terrain nationally; they are an active battlefield, fought out in school and library book removals, in funding fights over public library systems, and now in the quiet defunding of a program that puts a single free book in a child’s hands each month. The casualties of that fight are not abstract. A child who does not encounter books in the first five years of life does not get those years reissued at eight or twelve; the window for building early reading skill closes on a biological, not a legislative, schedule, and every budget cycle that treats early literacy funding as negotiable is making that closure permanent for some number of real children, disproportionately in the communities already carrying the least institutional cushion to absorb it. The lesson the HBCU ecosystem has already learned from its own experience with federal and state funding volatility that institutions dependent entirely on public appropriation are institutions one legislative session away from crisis applies with equal force here. The strategic response is the same in both cases: build parallel, community-owned capacity that does not evaporate when a state’s budget priorities shift.

None of this requires alumni to feel sentimental to justify participating, even if the sentiment is real and, in this case, well earned. It requires recognizing that a five-year-old in Lorman, Daytona Beach, or Dover who receives a free book every month for five years is a more literate ten-year-old, a more prepared seventeen-year-old, and, a decade or two on, a more plausible applicant, employee, or neighbor of the institution down the road and that the zip code field on a donation form is, in this narrow but real sense, an instrument of institutional strategy. The Imagination Library will likely survive the loss of its founder; whether the specific communities that surround Black colleges and universities keep receiving it is a separate question, one that now depends on whether the institutions with the clearest long-run interest in the answer choose to treat it as their responsibility.

There is also a simpler way to say all of this. Dolly Parton spent four decades showing up for Black America without asking anything of it in return and not always loudly, rarely as spectacle, usually in the form of money quietly redirected toward a Black neighborhood, a vaccine trial, an artist reworking her song, a stance taken when it would have been easier not to. The obligation that creates is not sentimental; it is the same obligation that governs any relationship built on reciprocity rather than charity. An institution she built and unsentimentally invested in is now vulnerable and not only in Indiana and Missouri, but as one casualty inside a far broader, ongoing national contest over whether children retain unencumbered access to books at all, playing out simultaneously in book removals from school and library shelves and in funding fights over public library systems nationwide. She never framed that fight as her own. But a free book mailed to a five-year-old every month for five years was always, structurally, a stake in it. Showing up for that institution the way she showed up for Black America; consistently, structurally, without waiting to be asked twice is simply the other half of the exchange she started. That is what protecting her legacy actually looks like: not a tribute, but a continuation.

How to do this, starting today:

  1. Get your HBCU’s zip code. Not your alma mater’s mailing address — the zip code of the actual community around the campus, where the children you’d be reaching live.
  2. Confirm a Local Program Partner is active there. Go to imaginationlibrary.com/check-availability and enter the zip code before donating. Coverage isn’t universal — some HBCU communities don’t have an affiliate yet, which is its own problem worth knowing about.
  3. Go to donate.imaginationlibrary.com and designate your gift. Select your country, check the box to designate the donation to a specific Local Program Partner, and enter the zip code so it routes to that community rather than into the general fund.
  4. Set it to recur monthly, not once. A one-time gift helps a handful of children for a few months. A standing monthly gift is what keeps a child enrolled from birth through age five — pick an amount you can sustain, not one that feels good today and stops in March.
  5. Pull someone else in before you close the tab. Text the group chat, post it to your chapter’s page, bring the zip code to next year’s homecoming. This works at scale only if it becomes a habit alumni pass to each other, not an individual good deed.
  6. If there’s no local partner yet, say so out loud. Flag it to your alumni association or your institution’s advancement office. A missing affiliate in an HBCU’s own community is a gap someone with standing needs to raise with a local library system or community foundation — not just wait out.

Disclaimer: This article was assisted by ClaudeAI.
The 1.8% Problem: What the Wealth Data Says About NIL’s HBCU Gap

“In a race-based capitalist society, it’s not what you know — it’s what you own.” – Dr. Claud Anderson

In 1975, a small manufacturing town watched its largest employer announce a new headquarters two counties over. The mayor called a meeting of the leading families and asked them to match the incentive package the rival town had offered. The families were respected, well-connected, active in every civic club in the region but not one of them owned the mill, the bank, or the rail line that had made the town matter in the first place. They owned homes, pensions, and good names. The headquarters left. Two decades later, when a regional grocery distributor scouted the same corridor for a new warehouse hub, it wasn’t the town’s civic reputation that won the deal, it was the fact that, by then, three local families owned the land, the trucking contracts, and the cold-storage facility the distributor needed to move product. Ownership, not affection, decided where capital went.

That distinction between people who care about an institution and people who own enough to move capital toward it is the one that has been missing from nearly every conversation about Name, Image and Likeness and the widening chasm between Historically Black Colleges and Universities and their Power Four counterparts. The prevailing HBCU theory of the NIL era held that Black America’s demonstrable, generational devotion to its football and basketball programs would translate into competitive collective fundraising once the NCAA’s amateurism rules fell. It has not, and it will not, because the premise was never about devotion. It was about ownership, and on that metric the arithmetic was never close.

Consider what happened in West Texas this summer. Texas Tech’s football stadium, known for decades as Jones AT&T Stadium, was renamed Galaxy Stadium in a naming-rights agreement reported at $75 million, replacing AT&T as the venue’s corporate partner. Galaxy Digital is a cryptocurrency and AI-infrastructure company that operates a large data campus in nearby Dickens County, currently undergoing a multibillion-dollar expansion. Its founder and chief executive, Mike Novogratz, is a Princeton graduate. AT&T, the company that held the naming rights before it, is led by John Stankey, a graduate of Loyola Marymount and UCLA. Neither man has any alumni tie to Texas Tech. The deal was not an act of institutional loyalty. It was a commercial transaction, a company with regional infrastructure interests buying brand proximity to a media asset with roughly 60,000 seats and a television footprint. Around the same time, Ripple became the first cryptocurrency sponsor to appear on a college jersey, at the University of Kansas, the alma mater of Ripple’s chief executive, Brad Garlinghouse, but a decision made unilaterally by a founder who controls his company’s marketing budget, not a fundraising campaign that mobilized thousands of small donors.

Compare that to the version of “alumni giving” available to HBCUs. Mark Cuban, a 1981 graduate of Indiana University and among the wealthiest men to build his fortune from a single company he founded and sold, has been a steady donor to his alma mater: roughly five million dollars for a sports media center in 2015, six million for the rugby program, and an undisclosed “big number” more recently funneled toward Indiana’s transfer portal recruiting. These are genuinely generous gifts from a genuinely engaged alumnus. They are also, by an order of magnitude or more, smaller than what a single infrastructure company paid for a stadium’s name. That gap is the entire story. When the money comes from an alumnus who happens to own a company outright, the number is real but bounded by one person’s balance sheet. When the money comes from a corporation with no alumni relationship at all, the number reflects what an asset, the media rights, the stadium, the media market, is worth on the open market, and it dwarfs even the most generous individual gift.

HBCUs have access to neither lever at scale, and the reason is visible in the numbers rather than in sentiment. HBCU Money’s 2024 Annual Wealth Report, drawing on Federal Reserve data, put total African American household assets at roughly $7.1 trillion. Private businesses — the asset class that actually produces boosters capable of writing nine-figure checks — accounted for just $330 billion of that, or 4.7% of African American household assets, and only 1.8% of all U.S. household private business assets. For a population that is roughly 13 to 14% of the country, a 1.8% share of the nation’s private business wealth is not a gap; it is close to an absence, and it is the single most underrepresented major asset category in the entire report relative to population share. Corporate equities and mutual fund shares told the same story from a different angle: also $330 billion, also 4.7% of Black household assets, but a mere 0.7% of total U.S. household equity holdings meaning African American households are not meaningfully participating in the ownership side of public markets either.

What African American households do hold, in scale, is retirement income tied to employment. Defined benefit pension entitlements totaled $1.73 trillion or 24.4% of all African American household assets, and 9.7% of the nation’s defined benefit pension assets, by far the highest representation of any asset category relative to population share. Add defined contribution plans like 401(k)s, another $880 billion and 12.4% of assets, and pension entitlements alone account for nearly 37% of everything African American households own — more than real estate, more than every other asset class combined except real estate itself. That is not a portfolio built by owners. It is a balance sheet built by workers: people whose wealth exists because an employer, public or private, guaranteed them a retirement benefit in exchange for decades of labor, not because they held equity in the enterprise itself. The wealth is real, and the institutions that produced it, often public-sector employers and unionized industries, deserve credit for building it. But a pension check, however large in aggregate, cannot write a stadium naming-rights deal. Only ownership can, and ownership is precisely the asset class where the data shows African American households are furthest from parity.

This is not a story about HBCU alumni failing to show up. It is a story about a capital-formation deficit that predates NIL by a century, rooted in exclusion from mainstream lending, redlining that kept Black-owned enterprise from accumulating the commercial real estate and equity positions that compound into founder-scale wealth, and a labor-market history that concentrated African American economic participation in employment rather than ownership, a history the wealth data confirms is still very much the present, not just the past. NIL simply exposed, in real time and in dollar figures anyone can look up, a gap that institutional strategists have been describing in more abstract terms for years. The mistake was believing that emotional intensity, the unmatched loyalty HBCU alumni show their bands, their homecomings, their institutions could substitute for what only ownership scale provides. It cannot. A hundred thousand donors giving fifty dollars each produces five million dollars and an enormous amount of goodwill. It does not produce seventy-five million dollars, because the mathematics of collective small-dollar giving and the mathematics of a single balance sheet decision operate on entirely different curves.

The strategic response, then, cannot be a better fundraising pitch. It has to be a redirection of where HBCU athletic and institutional leadership spend their effort. Conference-level collective bargaining, SWAC and MEAC schools pooling media rights and NIL infrastructure rather than competing individually for the same small donor base, captures at least some of the scale economics that individual HBCUs cannot achieve alone. Building actual venture and private equity vehicles modeled on efforts like Ariel Investments’ Project Black, which exists explicitly to grow Black-owned enterprises to the scale where their founders become the next generation of nine-figure donors, addresses the underlying ownership gap rather than the symptom. HBCU athletic departments should pursue infrastructure and commercial partnerships on the same terms Galaxy Digital pursued Texas Tech; as deals tied to real assets (media rights, campus real estate, facility co-location) rather than appeals to conscience from companies with no alumni connection to lose sleep over. And alumni giving programs should shift from one-time gifts toward equity-bearing vehicles — alumni investment funds tied to HBCU-linked enterprises — that convert working-professional generosity into compounding ownership stakes rather than annual write-offs.

None of this closes the gap by next season. The wealth data suggests the honest horizon for building an HBCU-linked ownership class capable of matching this kind of capital is measured in decades, not fundraising cycles, the private business share of African American wealth has moved only marginally year over year even as pensions and real estate continued compounding. But the alternative of continuing to ask a donor base of working professionals to out-fundraise infrastructure companies and telecom giants was never a strategy. It was a hope mistaken for one.

Disclaimer: This article was assisted by ClaudeAI.

The Collapse of African America’s Timber Companies Parallels Its Land Ownership Collapse

We are forced to trust the very institutions who stole the land in the first place because we have not developed and maintained our own. – William A. Foster, IV

A grandfather in Wilcox County plants loblolly pine on forty acres in 1961, the year the trees will outlive him being the whole point. He tells his children the timber is not for cutting; it is for holding. When he dies without a will, the forty acres become the property of nine heirs, then, a generation later, of thirty-one. No bank will lend against a title held by thirty-one people who cannot agree to sign the same document. The family calls the county forester listed on the state’s directory, the only one covering their district, because there is no other option in the phone book and no other name anyone in the family has ever heard mentioned with trust. The advice that comes back is vague, the timeline uncertain, and there is no second opinion to check it against, no other firm to call, no one who looks like the family sitting across the table. The pines keep growing, undermanaged not for lack of care but for lack of anywhere safe to take that care. Forty years after planting, a timber company buys out the confused heirs for a fraction of the standing timber’s value, and the grandfather’s patient capital becomes someone else’s harvest.

That scene is not a story about one bad forester or one unlucky family. It is a story about what happens when an entire asset class has exactly zero Black-owned institutions capable of serving it; no brokerage, no financing arm, no forestry consultancy, no appraisal firm built by and accountable to the community whose land is on the table. For nearly every other category of wealth-building infrastructure, HBCU Standard has documented at least a partial institutional base: Black-owned banks and credit unions, Black-owned commercial real estate firms, Black-owned construction companies. In rural land and timberland specifically, a category increasingly discussed as an inflation hedge, a carbon-credit asset, and a durable multigenerational holding — that base does not exist. Not a small one. Not a regional one. None. And the absence does not simply mean missed opportunity. It means that every African American family holding rural land, and every one considering buying it, is doing so without the single thing that would let them tell the difference between good advice and bad: a trusted counterparty inside the industry with something to lose if it gets that advice wrong.

This is the predicament worth naming plainly. A family that already holds land has, in most of the rural South, exactly one state district forester assigned to their county, no competing Black-owned firm to call for a second opinion, and no institutional recourse if that forester’s guidance turns out to serve someone else’s interests rather than theirs. A family looking to buy timberland as an asset has no Black-owned equivalent of a firm like Hall and Hall, which does not simply broker land but finances it directly, offering loan programs ranging from low variable rates to full thirty-year fixed terms so a client can originate, appraise, and fund an acquisition inside a single relationship. That vertical integration is precisely what makes an institution durable across a timber rotation: the same firm that helps a client find and value a parcel can also lend against it, rather than sending the client back out to a separate lender with no connection to the land or the deal.

To understand why that absence matters, it helps to see what a firm like Hall and Hall actually does, because it bears almost no resemblance to the real estate transaction most readers know from buying a house. A residential agent lists a property, compares it against recent sales of similar homes nearby, and hands the buyer off to a conventional mortgage lender who underwrites based on the buyer’s income and an appraiser’s estimate of the house’s value alone. None of those tools transfer to timberland. Valuing a working forest requires an actual cruise of the standing timber; a forester physically walking the property to inventory species, age, volume per acre, and growth rate because the trees themselves are a separate, living asset with their own market price, layered on top of the bare land value, changing every year whether anyone touches it or not. Financing the purchase means underwriting against decades of projected harvest income, and often against secondary income like grazing or hunting leases, rather than a buyer’s fixed monthly paycheck, which is why Hall and Hall runs its own loan programs instead of referring clients to a bank teller. And the transaction itself carries considerations a residential closing never touches: mineral rights that may or may not convey with the surface, water rights in Western states, conservation easements that permanently restrict future use in exchange for tax benefits, access easements across neighboring land, and a formal management plan for what happens to the timber over the next thirty years, not just what happens at the closing table. A firm built to handle all of that under one roof, continuously, is a fundamentally different kind of institution than a residential brokerage that occasionally lists rural acreage on the side and it is exactly why calling a local real estate agent, however well-intentioned, is not a substitute for the thing that’s missing.

No Black-owned firm offers any piece of that stack, let alone all of it. A family that finds its way past appraisal and negotiation on its own still has to secure financing from an institution outside the community entirely often the very kind of lender whose historical record with Black landowners is the reason for caution in the first place.

That wariness is not paranoia. It has a documented record behind it. Pigford v. Glickman, settled in 1999 as one of the largest civil rights settlements in American history, established in federal court that the USDA had systematically discriminated against Black farmers in the allocation of farm loans and disaster assistance between 1981 and 1996 delaying and denying credit that white farmers received routinely, and for over a decade failing to functionally operate the very civil rights office meant to investigate complaints about it. Congress appropriated another $1.2 billion in 2010 for a second settlement, Pigford II, because so many farmers with legitimate claims had been unable to file the first time. This is not ancient history from the era of outright land theft after emancipation. It is a pattern of institutional behavior toward Black landowners that persisted into living memory, inside the very federal agency structure that state and district foresters, county extension offices, and agricultural lenders all sit within. A family that has watched that pattern play out in the district office, in the bank, sometimes in their own family’s dealings with a local forester has every reason to want a trusted, accountable alternative before signing anything. The absence of that alternative is the actual risk, not an inconvenience layered on top of one.

Layer the heirs’ property problem on top of that trust deficit and the predicament compounds rather than adds. Research out of the University of Georgia’s Warnell School of Forestry has documented how clouded title land passed down without a will, held as an undivided interest among a growing number of descendants locks families out of financing, cost-share programs, and professional forest management, because no lender or agency wants to deal with an ownership structure that any single heir could blow up with a partition sale. Resolving that title requires legal expertise most families cannot afford and most local firms are not built to provide with any particular care. Mavis Gragg’s organization HeirShares exists specifically to clear these legal pathways, and the Federation of Southern Cooperatives has run a Land Assistance Fund toward the same end for decades. But neither is a brokerage, a lender, or a forestry management firm. They can help a family reach clean title. They cannot then walk that family through financing a thinning operation, negotiating a fair timber sale, or acquiring a second parcel to expand the holding, the actual services a firm like Hall and Hall provides continuously to the families who already trust it. Clearing title without a trusted destination to route the resulting clean parcel toward simply relocates the risk rather than resolving it.

The scale of what’s been lost while this institutional vacuum sat unfilled is worth stating plainly, in the register this publication uses for these numbers rather than the multi-trillion projections other outlets reach for. In 1910, according to the National Forest Foundation, Black Americans owned 195 timber companies and comprised roughly a quarter of all employees in the forest products industry. By 1920, per the Land Trust Alliance, African American farmers controlled approximately 14 percent of the nation’s farmland; today that figure is under 1 percent, and total African American land ownership across every category; timberland, farmland, residential, everything has fallen from an estimated 15 to 16 million acres to under 2 million. Set that number against a single entry on the Land Report’s 2025 ranking of America’s largest private landowners: the Emmerson family, through Sierra Pacific Industries, holds 2.44 million acres of timberland in California, Oregon, and Washington alone more than the entirety of Black land ownership nationwide, across every category, combined. John Malone holds roughly 2.2 million acres across four states. The Reed family’s Green Diamond Resource Company, built from a Pacific Northwest logging operation started in 1897, holds about 2.1 million acres. Each of those holdings is the product of a century or more of uninterrupted institutional continuity: clean title passed down without interruption, financing relationships maintained across generations, professional forestry management retained continuously rather than improvised family by family. That continuity is precisely what heirs’ property and the absence of a trusted institutional counterparty have made structurally difficult for Black landowners to replicate, no matter how much care any individual family brings to the effort.

None of this argues that timberland is a bad asset for African American families to hold or acquire. It argues the opposite: that the fundamentals of the asset class; steady periodic cash flow from harvests, low correlation with equity markets, a growing carbon-credit revenue stream for standing forest, and a purchase price still within reach of pooled institutional capital make it exactly the kind of holding worth building durable infrastructure around. And the talent to staff that infrastructure is not the missing piece. Alabama A&M University, one of the nineteen 1890 land-grant HBCUs rather than one of the handful of flagship HBCUs (Howard, Morehouse, Spelman) usually invoked in this conversation, runs the only professionally accredited forestry degree at an HBCU and operates as a USDA Forest Service Center of Excellence. Southern University and A&M College in Baton Rouge, part of the only historically Black land-grant university system in the country, offers a bachelor’s, master’s, and Ph.D. in Urban Forestry through a program it describes as the most comprehensive of its kind in the nation. Tuskegee University runs combined forestry programs with Auburn, Iowa State, the University of Michigan, and Idaho State, sending its students on to finish accredited degrees at partner institutions. And a partnership dating to 1993 between the U.S. Forest Service and four HBCUs; Alabama A&M, Southern, Tuskegee, and Florida A&M has, according to the Forest Service’s own national diversity student programs manager, trained two-thirds of the Black foresters currently working inside the agency. That is not a thin pipeline. It is a substantial, decades-old talent base, producing credentialed foresters at meaningful scale, virtually none of whom currently have the option of being hired into a private Black-owned brokerage, appraisal, or land-management firm because no such firm exists to hire them. The gap in this asset class was never expertise. It is the institution that expertise would staff.

What the Wilcox County family needed in 1961, and what a family looking to buy its first parcel of timberland needs today, is the same thing: an institution built specifically to hold this asset class the way Sierra Pacific and Green Diamond hold theirs, financed the way Hall and Hall finances its own clients’ acquisitions, staffed by graduates of Alabama A&M, Southern, and Tuskegee who are accountable to the community whose trust the industry has not yet earned, and structured to move a family from clouded title through financing through active management without ever requiring them to extend blind faith to a district office or an outside lender with no history of earning it. Every piece of that institution’s eventual capability already exists somewhere, disconnected from the others; title-clearing organizations, a credentialed forestry pipeline, cooperative land trusts, community capital sitting in Black-owned banks and HBCU endowments. Coordinating those pieces into one accountable, professionally staffed, vertically financed institution is not a distant aspiration. It is the specific, buildable answer to a specific, well-documented predicament.

The grandfather who planted loblolly pine in 1961 was making an institutional bet without an institution to back it, trusting that the trees, the family, and eventually someone trustworthy to manage them, would all still be standing when the rotation came due. The trees held up their end. What failed was everything around them: the title no bank would recognize, the forester no one had reason to trust, the financing that had to be sought from strangers, the firm that never got built to stand between the family and the forced sale. Until African America has its own version of the institution that holds land the way Sierra Pacific and Green Diamond hold theirs and finances it the way Hall and Hall finances its own, every acre already owned and every acre still to be bought carries a risk no amount of individual caution can fully offset.

Disclaimer: This article was assisted by ClaudeAI.
Building Dynasties: What It Will Take for African American Families to Rise to Power

“control, control of resources, control of self, control of nation, requires preparation — Garveyism was about total preparation.” – Dr. John Henrik Clarke, writing on Marcus Garvey’s philosophy of Black institutional power

In 1952, a mason in Americus, Georgia bought eleven acres with cash he’d saved from three decades of laying brick. He built a house on it, a smokehouse behind it, and a wraparound porch where he told his grandchildren that the land was the family’s now, forever. He died in 1979. By 1994, the eleven acres had been split six ways, sold in fragments to cover a funeral, a divorce, and two bad business loans. Today a subdivision sits where the smokehouse stood. The mason did everything right by the logic he was given: work, save, buy, own. What he lacked was not virtue. It was infrastructure. Nobody had ever taught him that land without governance is just land waiting to be divided.

That story is not an outlier. It is the median outcome. And it is the central argument of this piece: African America’s problem was never a shortage of individual achievement. It is a near-total absence of the legal, financial, and cultural machinery that converts one generation’s success into the next generation’s platform. Until that machinery is built, deliberately and aggressively, every dollar earned by this community will keep dying with the person who earned it.

Start with the scoreboard, because the scoreboard is brutal. The Federal Reserve’s 2022 Survey of Consumer Finances put median Black household net worth at $44,900, against $285,000 for the median White household — a gap of more than six to one, and one that widened in absolute dollar terms even as Black wealth grew faster in percentage terms during the pandemic recovery. Growth rate is a vanity metric when the base is this small. A 60 percent increase on $28,000 is still poverty with better arithmetic. The gap is not closing. It is compounding, in the same way interest compounds, except in the wrong direction.

Now layer on top of that the single largest wealth movement in American history, already underway. Cerulli Associates projects that $84 trillion will pass from the Baby Boomer and Silent Generations to heirs and charities through 2045, the bulk of it concentrated among households that were already high-net-worth. This is not a rising tide. It is an inheritance economy, and inheritance economies reward whoever already has family structures in place to receive, consolidate, and reinvest capital across generations. Families without that structure will watch the transfer happen around them, not to them. The transfer is not going to wait for African America to get its paperwork in order.

This is where the sentimental version of “generational wealth” needs to be retired. Passing down money is not the same as passing down power, and Black America has been sold the former as if it were the latter. Power, as any serious student of the Waltons, the Rockefellers, or the Kochs understands, does not come from an inheritance check. It comes from the entity that controls the check. The Walton family does not merely benefit from Walmart’s success; through Walton Enterprises LLC and the Walton Family Holdings Trust, they collectively control roughly 45 percent of the company’s outstanding shares, a concentrated bloc large enough to determine board composition, executive succession, and long-term strategy three generations after Sam Walton’s death. That is not inheritance. That is institutionalized command, engineered through trust structures, family governance, and a refusal to let ownership fragment. Jay-Z’s net worth impresses a magazine cover. It does nothing for the fortieth Black family down the street, because it is not organized as an institution — it is one man’s balance sheet, subject to one man’s mortality.

The uncomfortable truth is that most families, of any race, fail at this. Research tracked by the Family Business Institute finds that roughly 30 percent of family-owned businesses survive into a second generation, about 12 percent make it to a third, and only 3 percent endure into a fourth. Succession is hard even with capital, even with lawyers, even with three generations of practice at running something. What that data point exposes is not that Black families are uniquely undisciplined — it’s that family continuity is a discipline nobody is taught, and African America has had roughly one-fifth of the time (counting from Emancipation, and accounting for the systematic destruction of Black wealth through redlining, urban renewal, and outright terrorism such as the 1921 razing of Tulsa’s Greenwood district) to build the muscle memory that older American dynasties built over five and six generations. The response to that deficit cannot be more individual grit. It has to be structure, copied deliberately from where it already works, and adapted ruthlessly to this community’s actual starting conditions.

So build the structure. A family constitution — a written document specifying mission, capital rules, and succession mechanics — costs nothing but discipline and an afternoon with a competent estate attorney, yet almost no Black family has one, while every dynasty mentioned above treats theirs as more binding than a corporate bylaw. A family office does not require billionaire assets to justify its existence; pooled family capital in the low six figures is sufficient to retain a fee-only advisor, establish an LLC or trust structure, and begin making coordinated decisions across a real portfolio — brokerage accounts, retirement vehicles, business equity, insurance-funded trusts, even royalty and intellectual-property streams — instead of six relatives each managing a fragment of the same family’s capital in isolation. Land is one asset class among several and should be governed the same way the rest are: never liquidated to cover an emergency when it could instead be collateralized, folded into a trust, or held alongside an equity stake in a family business and a diversified investment account, each professionally managed rather than administered by whichever relative answered the phone first.

None of these families stayed inside their founding asset. Koch Industries began as a part-interest in a single Minnesota oil refinery bought out in the 1940s and 1960s; under Charles Koch it diversified deliberately into pipelines, fertilizer, pulp and paper, ranching, glass, electronics, and commodities trading, so that no single market downturn — a refining glut, a paper-price collapse, a bad cattle season — could touch the whole estate at once. The Rothschilds began as court bankers to European nobility in the 1760s and, over two centuries, moved family capital into railways, mining, real estate, energy, and, notably, wine estates like Château Lafite and Château Mouton — acquired not as hobbies but as productive, appreciating assets that diversified the family’s holdings away from the banking sector that made them. Even the Waltons, whose fortune is most associated with a single company, don’t hold it as a single asset: Walton Enterprises runs its own internal investment arm allocating family capital into private equity, real estate, and outside ventures entirely apart from Walmart stock, precisely so the family’s fate isn’t fused to one retailer’s stock price. In every case, the founding asset became the seed capital for a portfolio, not the permanent shape of the estate. That is the model the eleven acres in Americus should be measured against. The land was never meant to be the ceiling of that family’s wealth — it was meant to be collateral for the next asset, security for a loan into a business, a hedge alongside a brokerage account, one holding in a portfolio instead of the whole of it. Held that way, structured that way, it doesn’t matter whether the estate a family passes down began as land, a barbershop, a nursing license, or a pension. What matters is whether it was ever allowed to grow past its origin.

None of this is exotic. It is standard operating procedure for every dynasty this essay has named. It has simply never been marketed to African America as something within reach, because the wealth management industry profits more from selling individual products than from building family institutions that don’t need it.

Institutions of the wider Black ecosystem have a direct, self-interested role here, and this is where the case must be made in dollars, not sentiment. A Black-owned bank or credit union that captures family trust deposits and estate accounts gains stable, patient capital instead of transactional balances. A historically Black college or university that structures a real endowed-chair or scholarship-naming relationship with a family — rather than accepting a one-time gift — gains a recurring donor relationship spanning generations rather than a single tax-season transaction. Fisk, Tougaloo, Dillard, and Xavier of Louisiana have decades of experience cultivating exactly this kind of multigenerational donor family; Alcorn State, Coppin State, Savannah State, Bethune-Cookman, Norfolk State, Delaware State, Fort Valley State, and Morgan State could each become the anchor institution for a rising family dynasty if they pursued the relationship as deliberately as the Rockefellers pursued the University of Chicago or the Dukes pursued the university that bears their name. The institution that captures a family early, before its capital scales, is the institution that owns the relationship when that capital multiplies. This is not charity. It is customer acquisition, and any HBCU treating it otherwise is leaving its own endowment on the table.

The same logic extends past the water’s edge. Diaspora capital coordination — joint investment vehicles linking African American family offices with counterparts in the Caribbean and across Africa Core — is not a symbolic gesture toward Pan-Africanism. It is a hedge against the concentration risk of building wealth inside a single, historically hostile domestic market. A family real estate or infrastructure fund co-managed across African American, Jamaican, and Ghanaian family offices diversifies political risk, currency exposure, and asset class in one structure, while building exactly the kind of institutional density and strategic coordination that isolated, single-country family wealth can never achieve alone.

None of this happens through moral appeal, and this publication has no interest in making one. Appeals to racial solidarity have moved conferences and Twitter timelines; they have not moved balance sheets. The case for family institutionalization has to be made the way the Waltons, the Kochs, and the Wallenbergs made it to their own descendants: this structure protects what you have from your own children’s mistakes, from probate courts, from market volatility, and from the actuarial certainty that someone in every family eventually dies without a plan. Estate planning is not morbid. It is the single highest-leverage act of institution-building available to a family with under a million dollars in assets, and it costs less than a used car.

There is also a governance failure hiding inside the sentimental version of Black wealth-building that deserves direct confrontation. Families that treat wealth distribution as an equality exercise — splitting everything evenly among heirs regardless of role, competence, or commitment — are optimizing for fairness at the expense of survival. The Family Business Institute’s own data on why family enterprises collapse points overwhelmingly to succession disputes and undefined governance, not lack of capital. A family that assigns real roles — someone accountable for investment decisions, someone accountable for philanthropic strategy, someone accountable for legal and tax exposure — and backs those roles with actual authority, not just a title at Thanksgiving, will outlast a family that insists every cousin gets an equal, undifferentiated vote on every decision. Institutions require hierarchy. Families building institutions will have to get comfortable with that, however uncomfortable it sits against a cultural instinct toward flattened, communal decision-making.

The alternative to all of this is not neutral. It is continued erosion. Every family that fails to formalize governance sends its capital back into the undifferentiated churn of individual consumption — the paycheck model this publication has criticized elsewhere, in which wealth is treated as something to be spent rather than something to be commanded. Every dollar that leaves the Black institutional ecosystem through an unplanned estate, an uninsured death, or a liquidated piece of land is a dollar the next generation has to earn from zero, while families with institutional infrastructure simply compound what they already hold. The compounding gap in the Federal Reserve’s data is not an accident of history. It is the visible output of one set of families running institutional software and another set running none at all.

The mason in Americus did not fail his family. He succeeded at everything available to him in 1952, in a state where a Black man building wealth at all was itself an act of defiance. What failed him was the absence of a structure that could have held what he built past his own lifetime, and the absence of a plan to let that first asset become seed capital for a second and third — a trust, a governance document, a designated successor with both the authority and the training to keep the estate whole and growing, whatever form that estate took or became. That absence is fixable, at a scale of millions of families, in this generation, and it applies as much to a brokerage account or a stake in a family business as it does to eleven acres of Georgia clay. The Kochs turned one refinery into a dozen industries. The Rothschilds turned a banking desk into vineyards and mines. Neither family mistook where they started for where they had to stay. It requires no act of Congress and no act of philanthropy from outside the community. It requires families to stop organizing themselves as clusters of individuals bound by affection, and start organizing as institutions bound by structure, because affection does not survive probate court and structure does. The eleven acres are gone. Whatever the next generation holds — land, equity, a business, a portfolio, or something none of them have thought to build yet — does not have to stop there, and does not have to follow them into the ground.

Disclaimer: This article was assisted by ClaudeAI.