Tag Archives: hbcu strategy

The 1.8% Problem: What the Wealth Data Says About NIL’s HBCU Gap

“In a race-based capitalist society, it’s not what you know — it’s what you own.” – Dr. Claud Anderson
In 1975, a small manufacturing town watched its largest employer announce a new headquarters two counties over. The mayor called a meeting of the leading families and asked them to match the incentive package the rival town had offered. The families were respected, well-connected, active in every civic club in the region but not one of them owned the mill, the bank, or the rail line that had made the town matter in the first place. They owned homes, pensions, and good names. The headquarters left. Two decades later, when a regional grocery distributor scouted the same corridor for a new warehouse hub, it wasn’t the town’s civic reputation that won the deal, it was the fact that, by then, three local families owned the land, the trucking contracts, and the cold-storage facility the distributor needed to move product. Ownership, not affection, decided where capital went.

That distinction between people who care about an institution and people who own enough to move capital toward it is the one that has been missing from nearly every conversation about Name, Image and Likeness and the widening chasm between Historically Black Colleges and Universities and their Power Four counterparts. The prevailing HBCU theory of the NIL era held that Black America’s demonstrable, generational devotion to its football and basketball programs would translate into competitive collective fundraising once the NCAA’s amateurism rules fell. It has not, and it will not, because the premise was never about devotion. It was about ownership, and on that metric the arithmetic was never close.

Consider what happened in West Texas this summer. Texas Tech’s football stadium, known for decades as Jones AT&T Stadium, was renamed Galaxy Stadium in a naming-rights agreement reported at $75 million, replacing AT&T as the venue’s corporate partner. Galaxy Digital is a cryptocurrency and AI-infrastructure company that operates a large data campus in nearby Dickens County, currently undergoing a multibillion-dollar expansion. Its founder and chief executive, Mike Novogratz, is a Princeton graduate. AT&T, the company that held the naming rights before it, is led by John Stankey, a graduate of Loyola Marymount and UCLA. Neither man has any alumni tie to Texas Tech. The deal was not an act of institutional loyalty. It was a commercial transaction, a company with regional infrastructure interests buying brand proximity to a media asset with roughly 60,000 seats and a television footprint. Around the same time, Ripple became the first cryptocurrency sponsor to appear on a college jersey, at the University of Kansas, the alma mater of Ripple’s chief executive, Brad Garlinghouse, but a decision made unilaterally by a founder who controls his company’s marketing budget, not a fundraising campaign that mobilized thousands of small donors.

Compare that to the version of “alumni giving” available to HBCUs. Mark Cuban, a 1981 graduate of Indiana University and among the wealthiest men to build his fortune from a single company he founded and sold, has been a steady donor to his alma mater: roughly five million dollars for a sports media center in 2015, six million for the rugby program, and an undisclosed “big number” more recently funneled toward Indiana’s transfer portal recruiting. These are genuinely generous gifts from a genuinely engaged alumnus. They are also, by an order of magnitude or more, smaller than what a single infrastructure company paid for a stadium’s name. That gap is the entire story. When the money comes from an alumnus who happens to own a company outright, the number is real but bounded by one person’s balance sheet. When the money comes from a corporation with no alumni relationship at all, the number reflects what an asset, the media rights, the stadium, the media market, is worth on the open market, and it dwarfs even the most generous individual gift.

HBCUs have access to neither lever at scale, and the reason is visible in the numbers rather than in sentiment. HBCU Money’s 2024 Annual Wealth Report, drawing on Federal Reserve data, put total African American household assets at roughly $7.1 trillion. Private businesses — the asset class that actually produces boosters capable of writing nine-figure checks — accounted for just $330 billion of that, or 4.7% of African American household assets, and only 1.8% of all U.S. household private business assets. For a population that is roughly 13 to 14% of the country, a 1.8% share of the nation’s private business wealth is not a gap; it is close to an absence, and it is the single most underrepresented major asset category in the entire report relative to population share. Corporate equities and mutual fund shares told the same story from a different angle: also $330 billion, also 4.7% of Black household assets, but a mere 0.7% of total U.S. household equity holdings meaning African American households are not meaningfully participating in the ownership side of public markets either.

What African American households do hold, in scale, is retirement income tied to employment. Defined benefit pension entitlements totaled $1.73 trillion or 24.4% of all African American household assets, and 9.7% of the nation’s defined benefit pension assets, by far the highest representation of any asset category relative to population share. Add defined contribution plans like 401(k)s, another $880 billion and 12.4% of assets, and pension entitlements alone account for nearly 37% of everything African American households own — more than real estate, more than every other asset class combined except real estate itself. That is not a portfolio built by owners. It is a balance sheet built by workers: people whose wealth exists because an employer, public or private, guaranteed them a retirement benefit in exchange for decades of labor, not because they held equity in the enterprise itself. The wealth is real, and the institutions that produced it, often public-sector employers and unionized industries, deserve credit for building it. But a pension check, however large in aggregate, cannot write a stadium naming-rights deal. Only ownership can, and ownership is precisely the asset class where the data shows African American households are furthest from parity.

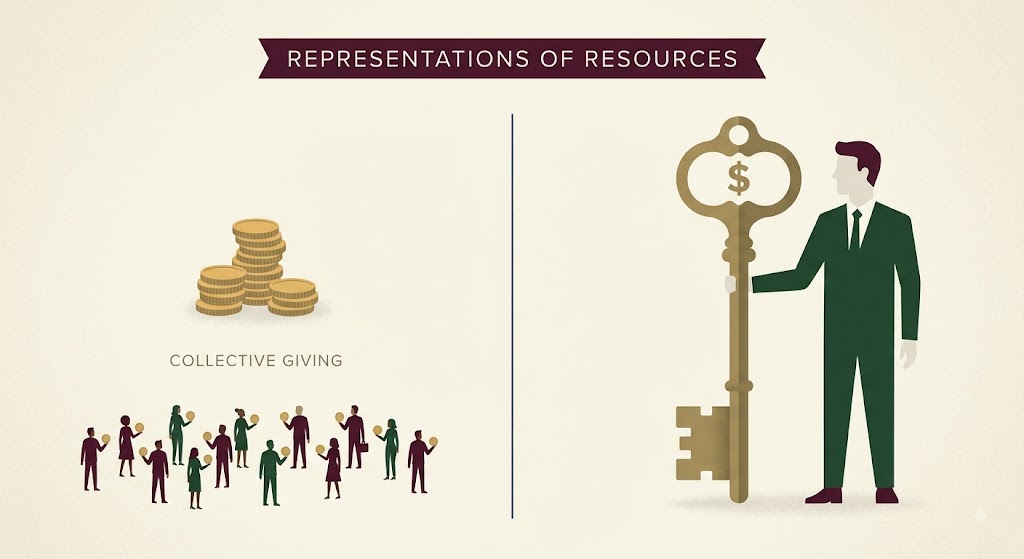
This is not a story about HBCU alumni failing to show up. It is a story about a capital-formation deficit that predates NIL by a century, rooted in exclusion from mainstream lending, redlining that kept Black-owned enterprise from accumulating the commercial real estate and equity positions that compound into founder-scale wealth, and a labor-market history that concentrated African American economic participation in employment rather than ownership, a history the wealth data confirms is still very much the present, not just the past. NIL simply exposed, in real time and in dollar figures anyone can look up, a gap that institutional strategists have been describing in more abstract terms for years. The mistake was believing that emotional intensity, the unmatched loyalty HBCU alumni show their bands, their homecomings, their institutions could substitute for what only ownership scale provides. It cannot. A hundred thousand donors giving fifty dollars each produces five million dollars and an enormous amount of goodwill. It does not produce seventy-five million dollars, because the mathematics of collective small-dollar giving and the mathematics of a single balance sheet decision operate on entirely different curves.

The strategic response, then, cannot be a better fundraising pitch. It has to be a redirection of where HBCU athletic and institutional leadership spend their effort. Conference-level collective bargaining, SWAC and MEAC schools pooling media rights and NIL infrastructure rather than competing individually for the same small donor base, captures at least some of the scale economics that individual HBCUs cannot achieve alone. Building actual venture and private equity vehicles modeled on efforts like Ariel Investments’ Project Black, which exists explicitly to grow Black-owned enterprises to the scale where their founders become the next generation of nine-figure donors, addresses the underlying ownership gap rather than the symptom. HBCU athletic departments should pursue infrastructure and commercial partnerships on the same terms Galaxy Digital pursued Texas Tech; as deals tied to real assets (media rights, campus real estate, facility co-location) rather than appeals to conscience from companies with no alumni connection to lose sleep over. And alumni giving programs should shift from one-time gifts toward equity-bearing vehicles — alumni investment funds tied to HBCU-linked enterprises — that convert working-professional generosity into compounding ownership stakes rather than annual write-offs.

None of this closes the gap by next season. The wealth data suggests the honest horizon for building an HBCU-linked ownership class capable of matching this kind of capital is measured in decades, not fundraising cycles, the private business share of African American wealth has moved only marginally year over year even as pensions and real estate continued compounding. But the alternative of continuing to ask a donor base of working professionals to out-fundraise infrastructure companies and telecom giants was never a strategy. It was a hope mistaken for one.

Disclaimer: This article was assisted by ClaudeAI.
The DEI Distraction: Why Black Business Leaders Are Defending the Wrong Battlefield

It is simple. Our talent and capital is either empowering and enriching our institutional ecosystem – or it is doing that for someone else. We are begging Others’ to let our talent and capital make them richer and more powerful. – William A. Foster, IV

When Bloomberg Businessweek convened a roundtable of prominent Black business executives in late March 2026 to discuss the Trump administration’s sweeping rollback of diversity, equity, and inclusion initiatives, the gathering carried an unmistakable weight. The participants — Ursula Burns of Integrum, Lisa Wardell of the American Express board, Jacob Walthour Jr. of Blueprint Capital Advisors, Nicole Reboe of Rich Talent Group, and Chris Williams of Siebert Williams Shank represent some of the most accomplished figures in American corporate life. Their concerns are real. Their frustrations are earned. And they are, with the greatest respect, focused on exactly the wrong problem.

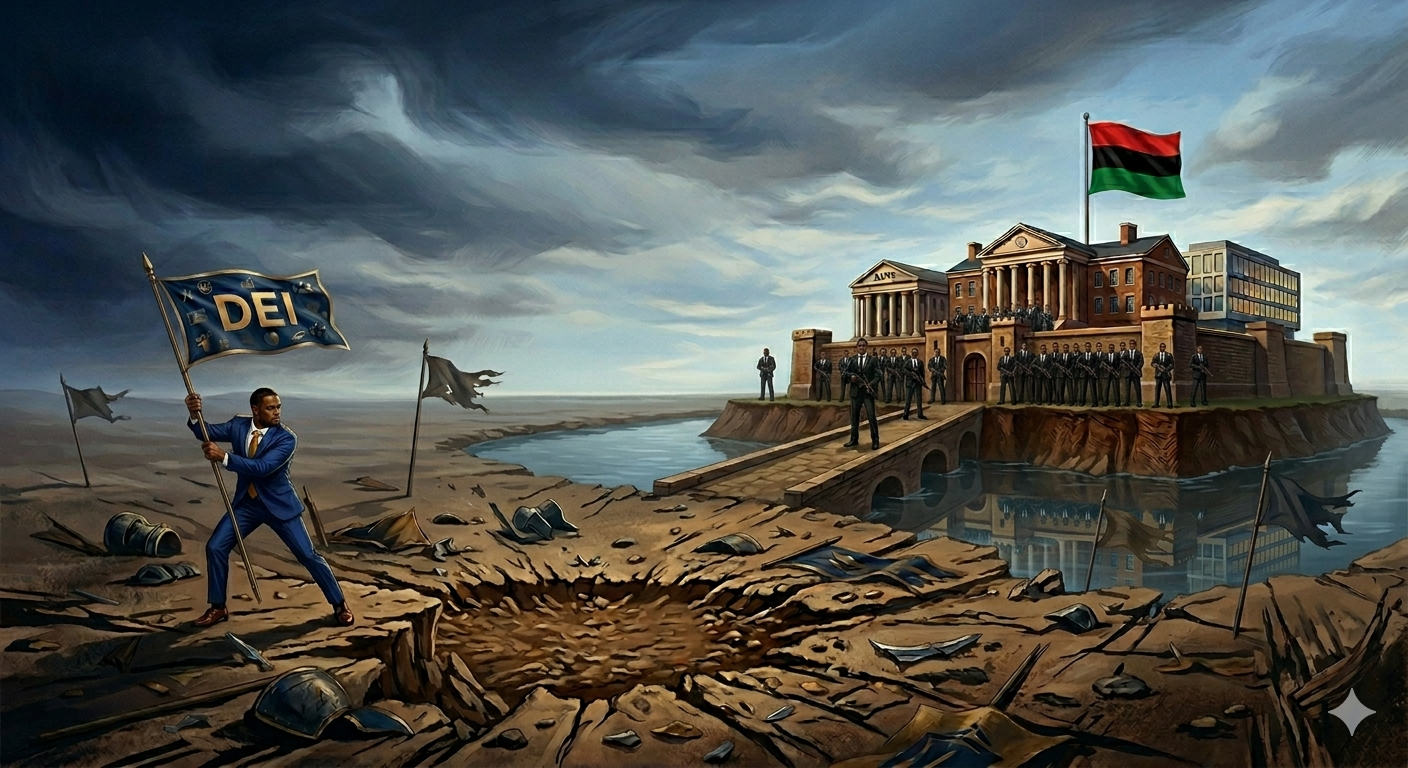
The DEI debate has consumed enormous intellectual and political energy among Black business leadership. Executives like Burns have emphasized that DEI efforts historically helped address systemic barriers rather than provide unfair advantages. This is correct as far as it goes. But defending the legitimacy of DEI however righteous the argument is fundamentally an argument about access to other people’s institutions. It is a debate about whether African American talent will be permitted to generate wealth for corporate structures that it does not own, govern, or ultimately benefit from in proportion to its contribution. Winning that argument secures a seat at a table built by someone else, financed by someone else, and passed on to someone else’s heirs.

The more consequential question, one that the DEI debate reliably obscures is this: what is the strategic value of Black business ownership as the foundation of an autonomous African American institutional ecosystem, and why has that ecosystem remained so structurally underdeveloped compared to the scale of Black talent and labor flowing through the broader American economy?

The case against centering the DEI debate as the primary lens for Black economic advancement is, at its core, an argument about capital flows. Every dollar of Black labor and talent that enters a corporation it does not own produces returns that are retained, reinvested, and compounded within that corporation’s ownership structure. The wages extracted represent a fraction of the value created. This is not a critique unique to the experience of African Americans, it is the fundamental logic of capitalism. The distinction, however, is that other ethnic and national communities have historically used their productive capacity to capitalize their own institutional ecosystems: banks, insurance companies, real estate holding entities, research universities, and media operations that recirculate wealth within the community rather than exporting it.

Between 2017 and 2022, Black-owned employer businesses grew by nearly 57 percent, adding more than 70,000 new firms, injecting $212 billion into the economy and paying over $61 billion in salaries. That is not a trivial contribution. But its structural limitations are equally stark. Black Americans make up 14 percent of the U.S. population but own only 3.3 percent of businesses. More revealing still: if Black business ownership continues to grow at its current rate of 4.72 percent annually, it will take 256 years to reach parity with the share of Black people in America, a timeline that leaves racial wealth gaps entrenched across generations. No DEI program, however well-designed or vigorously defended, addresses that structural gap. DEI operates within the existing distribution of institutional ownership. It does not alter it. A Black executive ascending to the C-suite of a Fortune 500 company is a personal achievement of consequence, but it does not transfer a dollar of equity to the African American institutional ecosystem. The corporation retains its ownership structure, its compounding endowment, and its ability to extend opportunity to subsequent generations on its own terms.

This is not an argument that employment in major corporations is without value. It is an argument about strategic priority and institutional logic. The Bloomberg roundtable reflects the perspective of individuals who have navigated the highest levels of American corporate life with exceptional skill. But the very fact that their primary public posture is a defense of DEI — a program designed to manage the terms of Black participation in institutions owned by others — illustrates how thoroughly that framework has captured the strategic imagination of Black business leadership. White workers overall still hold 71 percent of executive jobs, 61 percent of manager positions, and 54 percent of professional roles. DEI, at its most effective, redistributed a fraction of corporate leadership positions without altering the underlying structure of institutional ownership. The wealth generated by those institutions through equity appreciation, retained earnings, and compounding investment portfolios continued to flow overwhelmingly to the same ownership class it always has.

The parallel structure that could generate equivalent wealth retention within the African American community requires not better access to existing institutions but the construction and capitalization of independent ones. HBCUs represent the most significant existing node in that potential ecosystem. They are anchor institutions with land assets, research capacity, and the ability to concentrate and retain Black talent. But they remain chronically undercapitalized relative to their peer institutions, in large part because the most financially productive graduates of HBCUs and of Black communities broadly are systematically routed into corporations and financial institutions that extract rather than recirculate their productive capacity.

Black households have, on average, 77 percent less wealth than white households — roughly $958,000 less per household, representing approximately 24 cents for every dollar of white family wealth. That gap is not primarily explained by differences in income or educational attainment. It is explained by differences in asset ownership, intergenerational wealth transfer, and institutional investment. The DEI framework, even at its most ambitious, addresses income. It does not address assets. If the share of Black employer businesses reached parity with the share of the Black population, cities across the country could see as many as 757,000 new businesses, 6.3 million more jobs, and an additional $824 billion in revenue circulating in local economies. That figure represents the economic magnitude of the ownership gap and none of it is captured by diversity metrics in corporate hiring. The structural barriers to closing that gap are not primarily political. They are financial. On average, 35 percent of white business owners received all the financing they applied for, compared to 16 percent of Black business owners. Black entrepreneurs are nearly three times more likely than white entrepreneurs to have business growth and profitability negatively impacted by a lack of financial capital, and 70.6 percent rely on personal and family savings for financing which means that lower household wealth creates a compounding disadvantage that no corporate diversity initiative is designed to resolve. This is the architecture of the problem: insufficient institutional wealth produces insufficient capital formation, which constrains business ownership, which perpetuates insufficient institutional wealth. DEI does not break that cycle because it operates entirely outside of it.

The African American institutional ecosystem: HBCUs and their endowments, African American owned banks and credit unions, Black-owned insurance and real estate entities, and community development financial institutions represents the structural alternative to the DEI framework. It is not a consolation prize for those excluded from mainstream corporate life. It is the only mechanism capable of generating the compounding institutional wealth that produces genuine economic sovereignty. HBCUs enroll approximately 10 percent of Black college students while producing a disproportionate share of Black professionals in STEM, law, medicine, and business. They hold land assets in some of the most economically dynamic metros in the South. They maintain alumni networks that, if systematically directed toward institutional investment rather than individual career advancement, could generate endowment growth and enterprise development at a scale currently untapped. The strategic argument is straightforward: every Black student who graduates from an HBCU and subsequently directs their career, capital, and philanthropic energy toward institutions within the aforementioned African American ecosystem compounds the institutional wealth available to the next generation. Every Black student who takes that same talent into a corporation it does not own, however successfully, contributes to the wealth of an institution that will not reciprocate at the ecosystem level.

This is not an argument for economic separatism. It is an argument for institutional density, the same logic that has guided the development of Jewish philanthropic networks, Korean rotating credit associations, and the university endowment strategies of the Ivy League. Strong communities maintain reinforcing networks of institutions that recirculate capital and concentrate talent. The DEI framework asks Black Americans to enrich other communities’ institutional networks on the condition of fairer treatment. The ownership framework asks Black Americans to build their own.

None of this is to diminish the real harm caused by the current administration’s DEI rollbacks. Black-owned businesses that relied on federal contracting set-asides have seen immediate, concrete losses with some small business owners reporting the loss of $15,000 to $20,000 per month due to reduced contract flows. The SBA admitted only 65 companies to its 8(a) business development program in 2025, compared with more than 2,000 admissions over the previous four years. These are real economic injuries that warrant legal and political challenge. But the defensive posture of protecting DEI within institutions that Black America does not control is insufficient as a long-term economic strategy. The Bloomberg roundtable produced eloquent testimony about the frustrations of Black executives navigating a hostile political environment. It produced very little discussion of what autonomous Black institutional infrastructure should look like, or how the talent assembled in that room of capital allocators, board directors, investment bankers, and talent executives might direct its resources toward building it.

The transition from a DEI-centered to an ownership-centered strategic framework requires institutional coordination that does not yet exist at scale. It requires HBCU endowments to function as patient capital for Black enterprise ecosystems rather than passive investment portfolios. It requires Black-owned financial institutions to be capitalized and connected to the deal flow generated by Black corporate executives. It requires alumni networks to function as economic infrastructure rather than social affinity groups. And it requires Black business leadership to measure its success not by representation metrics within institutions it does not own, but by the growth of institutional assets within the ecosystem it does. The DEI debate is real and the rollback is damaging. But the strategic imagination of Black business leadership will remain constrained so long as its primary horizon is defined by the terms of inclusion offered by others. The more consequential work — slower, less visible, and politically unrewarded — is the construction of institutions powerful enough that the terms of inclusion become irrelevant. That is the work HBCUs and the broader African American institutional ecosystem exist to support. It is the work that this moment demands.

HBCU B-Schools’ Leadership Still Embarrassingly Lacking In HBCU Alumni

The most difficult thing in life is to know yourself. — Thales

The Graham Principle: Why HBCU Business Schools Must Lead From Within

Warren Buffett’s rejection by Benjamin Graham is more than a quaint footnote in the history of American finance. It is a parable about institutional loyalty, strategic insulation, and the deliberate construction of parallel economic power. Graham, the architect of value investing, declined to hire the future Oracle of Omaha not for lack of qualification but for reasons of principle. At a moment when Wall Street’s doors remained firmly closed to European American Jews, Graham made a conscious decision to build from within his own community. His hiring practices were not sentimental. They were strategic—an act of institutional self-preservation in a market structured against him. He understood that talent required more than identification; it required cultivation, protection, and deliberate positioning within institutions the community itself controlled.

A decade has passed since anyone undertook a comprehensive examination of leadership trends within HBCU business schools. The intervening years might reasonably have produced a renaissance of internal cultivation—an era defined by deliberate succession planning, alumni-led governance, and a clear institutional commitment to developing leadership from within. That hope has gone largely unrealized. Across the landscape of HBCU business education, the preference for external hires persists, the pipeline for internal leadership development remains thin, and the governing logic of these schools continues to defer, implicitly or explicitly, to standards of excellence defined by the very institutions that historically excluded Black scholars from full participation.

The appointment of deans and senior faculty from predominantly white institutions is routinely framed as a commitment to excellence—the familiar rhetoric of meritocracy dressed in the language of best practices. What this framing systematically obscures is the structural disadvantage HBCU graduates face in academic and professional labor markets, disadvantages produced not by deficiency but by decades of underfunding, network exclusion, and credential discrimination. When HBCU business schools accept this framing uncritically, they do not rise above structural inequality; they reproduce it within their own walls. The result is a business education ecosystem that remains institutionally disconnected from the communities it is chartered to serve.

Of the 85 accredited HBCU business schools and departments operating under the latest available data, fewer than 20 percent are led by HBCU alumni. Of that minority, fewer than half hold both undergraduate and graduate degrees from HBCUs, further attenuating the institutional knowledge that might otherwise be reinvested across the ecosystem. The contrast with elite PWI practice is clarifying. Approximately 75 percent of business school deans at Ivy League institutions hold at least one degree from an Ivy League school. This is not coincidence. It reflects a deliberate institutional philosophy that prizes continuity, internal network loyalty, and cultural capital accumulated within the institution itself. These schools understand that leadership is not merely a management function. It is an expression of institutional identity and a mechanism for transmitting values across generations of students and faculty.

HBCU business schools have not absorbed that lesson with equivalent seriousness. The absence of a deliberate succession strategy—one that identifies, mentors, and elevates internal talent over sustained periods—constitutes a structural failure that compounds over time. When young Black scholars do not see themselves reflected in the senior leadership of their own institutions, the implicit signal is that the path to authority runs elsewhere. And so it does. Promising scholars educated at HBCUs routinely migrate to PWIs for higher compensation, greater prestige, or more robust professional infrastructure. When those scholars eventually ascend to positions of institutional leadership, their loyalty and networks do not reliably return. The brain drain becomes self-reinforcing, and the institutions that initially formed these scholars see little of the compounded return on that investment.

This pattern might be called institutional amnesia—a collective failure to study, internalize, and replicate the strategies through which other minority communities have built durable institutional ecosystems. Jewish, Catholic, and Mormon institutions have each constructed powerful networks by systematically aligning leadership selection with community identity, concentrating institutional resources within their own structures, and maintaining cultural continuity across leadership transitions. They benchmark their performance against their own historical trajectories and communal objectives, not against the preferences of institutions oriented toward different communities and different purposes. HBCU business schools, by contrast, frequently evaluate themselves against ranking systems and accreditation frameworks built around metrics that reflect neither their mission nor the specific market failures their students are positioned to address.

The strategic costs of this posture are substantial and compounding. Recruitment searches for business school deans, when conducted through executive search firms, routinely exceed $250,000 in direct expense. When that investment produces a dean with limited institutional loyalty and no deep roots in the community the school serves, the organization is exposed to the further costs of short tenures, strategic discontinuity, and misaligned fundraising. Business schools function as economic engines—engines that generate networks, direct student talent toward particular career paths, shape research agendas, and produce or fail to produce the intellectual infrastructure that sustains community-level economic development. Leadership that lacks genuine cultural and strategic commitment to the HBCU mission cannot be expected to operate that engine in the community’s interest.

The curriculum consequences are equally significant. HBCU business schools exist in a moment when the structural dimensions of Black economic life—persistent wealth gaps, discriminatory access to capital, the collapse of Black-owned financial institutions, the chronic underdevelopment of Black neighborhoods—constitute some of the most pressing and tractable problems in American political economy. Addressing those problems requires not merely academic competence but institutional orientation. Who is designing curricula around cooperative economics and community wealth retention? Who is building research programs on Black entrepreneurship, the historical function of Black banking, and the mechanics of financial exclusion? Who is developing partnerships with Black-owned financial institutions, investment funds, and real estate developers that would allow students to graduate with network capital as well as intellectual credentials? These priorities require leadership that has been formed within the ecosystem, that understands its history, and that has a personal stake in its long-term trajectory.

The Graham analogy holds at precisely this level of analysis. Graham’s decision to hire from within his community was not a concession to sentiment. It was a calculated judgment that institutional effectiveness depended on leadership whose values, networks, and long-term interests were structurally aligned with the institution’s mission. He was not interested in demonstrating that his firm could attract talent validated by mainstream institutions. He was interested in building something that would compound over time within his own community’s orbit. The question for HBCU business school leadership is whether a comparable institutional logic is possible—and whether the will exists to pursue it.

The remedies are neither mysterious nor beyond reach, but they require deliberate institutional action sustained over years rather than episodic declarations of intent. HBCU business schools must establish formal succession pipelines that identify promising alumni early, support their doctoral training and early-career development, and create structured pathways back into institutional leadership. Mentorship programs, leadership fellowships, and transparent internal promotion tracks are the instruments through which this pipeline is built and maintained. Without them, talented HBCU alumni will continue to be absorbed by institutions with superior infrastructure, and the cycle of external dependence will continue.

Boards of trustees and presidential leadership must also reckon honestly with the hiring criteria that have produced current outcomes. Cultural alignment, mission literacy, and demonstrated investment in HBCU communities should carry weight commensurate with academic credentials in dean and faculty searches. These are not competing values. They are complementary ones, and institutions that treat them as such will find that the pool of qualified, mission-aligned candidates is larger than conventional search processes have suggested.

The benchmarks against which HBCU business schools measure their progress require reconstruction as well. Chasing rankings defined by and for PWIs produces strategic mimicry rather than institutional distinctiveness. The appropriate comparators are institutions that have used internal leadership and community alignment to produce durable economic outcomes for the communities they serve. The relevant question is not whether an HBCU business school resembles Wharton. It is whether that school is building the human capital, research infrastructure, and network density that the African American institutional ecosystem requires to become economically self-reinforcing.

Alumni hold a particular form of leverage in this process that has been insufficiently exercised. Philanthropic capital directed toward HBCU business schools carries with it the legitimate expectation of institutional integrity. Alumni who fund these schools are entitled to ask whether the institutions are investing in their own—whether succession planning exists, whether internal candidates are being developed and promoted, whether the school’s research and curricular agenda reflects the community’s strategic needs. These are not hostile demands. They are the expressions of institutional ownership that any serious donor community directs toward the organizations it sustains.

The broader HBCU ecosystem has long understood, at least in principle, that institutional density is the precondition for community resilience. Strong communities are not produced by exceptional individuals operating in isolation. They are produced by networks of reinforcing institutions—universities, banks, hospitals, media organizations, research centers—that retain capital, concentrate talent, and coordinate strategically across organizational boundaries. Business schools are a critical node in that network. They are the institutions most directly positioned to translate academic investment into economic infrastructure, to convert tuition into entrepreneurial capacity, and to channel philanthropic capital into research that serves the community’s long-term interests. Their leadership must reflect that position.

The failure to develop and elevate HBCU alumni into business school leadership is not simply an administrative oversight. It is a strategic error with consequences that extend well beyond the schools themselves. Every dean recruited from outside the ecosystem without a plan to develop internal successors is a missed compounding opportunity. Every promising scholar who departs for a PWI without a pathway back represents a loss of accumulated institutional knowledge that will not return on its own. Every curriculum designed to satisfy external accreditation standards at the expense of community-relevant content is a semester in which the institution’s potential as an engine of economic development goes partially unrealized.

Graham built his firm on the premise that talent required institutional protection to reach its full potential—that external markets, structured against your community, could not be trusted to recognize or reward what you were building. That premise has lost none of its force. HBCU business schools that internalize it, and act on it with the rigor and consistency it demands, will be better positioned to fulfill the extraordinary institutional promise that their founding represented. Those that continue to defer to external validation and outsourced leadership will find that the promise remains exactly that—unrealized, and over time, increasingly difficult to recover.

Disclaimer: This article was assisted by ClaudeAI.