Tag Archives: family governance

Homeownership and Power: Why African American Men Should Be Inspired—Not Intimidated—By African American Women Who Buy Homes

Black men like all men need to recognize that their worth in a relationship is and should be more than financial. That being said, for African America who has never reached 50% homeownership rate, to have men upset is on a level of a Eddie Murphy comedy – or Shakespeare tragegy. Take your pick. — William A. Foster, IV
In 1903, Maggie Lena Walker chartered the St. Luke Penny Savings Bank in Richmond, Virginia, becoming the first woman of any race in the United States to found and preside over a bank. She did not build it as a monument to her own ambition. She built it as infrastructure, a vessel through which the pennies of domestic workers and laundresses could become mortgages, storefronts, and a department store on Broad Street. Walker understood a principle African America has had to relearn in every generation since: an asset only compounds if there is an institution designed to hold it. A single woman’s initiative was never the story. The structure she built around it was.

That principle — asset first, institution second — is the correct lens for a trend now reshaping African American household formation, and it is being widely misread as a referendum on Black manhood rather than what it actually is. According to the National Association of Realtors’ 2025 Profile of Home Buyers and Sellers, single women account for 39 percent of all Black home purchases, nearly matching the 42 percent share held by married couples and far exceeding the single-women share among White (20 percent), Asian American/Pacific Islander (19 percent), or Hispanic (18 percent) buyers. NAR’s deputy chief economist Jessica Lautz notes that Black women have consistently outpaced women of every other racial and ethnic group as homebuyers — a pattern she attributes to a demographic “leaning especially hard on property as a tool for long-term wealth and stability.”

That explanation is accurate as far as it goes, but a rigorous accounting of the data requires a second layer Lautz’s framing does not reach: is this trend driven primarily by preference, or is it also driven by a contracting marriage market that leaves a growing share of Black women building wealth alone by structural necessity rather than by choice? Both can be true simultaneously, and treating them as mutually exclusive is the same interpretive error HBCU Money has flagged before when Black men cite the 75 percent figure, the share of married Black men wed to Black women, as proof that no structural shift is underway in Black partnership formation. That figure is real. So is the fact that Black men have posted the fastest-growing intermarriage rate of any male demographic group in the country, tripling from 8 percent of newly married Black men in 1980 to 24 percent by 2015, concentrated heavily among the most educated and highest-earning men. Among newly married Black adults overall, the gender gap in intermarriage runs 12 points in men’s favor — 24 percent of men to 12 percent of women. Among college graduates specifically, that gap widens to 17 points: 30 percent of Black male college graduates intermarry, against 13 percent of Black female college graduates.

Read against the NAR data, this is not a coincidence sitting beside another coincidence. It is one mechanism producing two visible outcomes. A marriage market in which credentialed Black women face a same-race partner pool contracting faster than any other group’s, compounded by incarceration’s well-documented effect on the available Black male population and a decades-long educational attainment gap that has moved decisively in women’s favor, is a marriage market with a measurable supply-demand imbalance on the women’s side of the ledger. Homeownership is one of the few asset classes a person can acquire entirely alone, without waiting on a partner who may not arrive on the expected timeline or at all. Framed this way, the surge in single Black women’s home purchases looks less like elective wealth-building and more like an institutionally rational hedge against a partnership market that is not behaving the way it does for other groups of women.

This is an accounting, not an accusation, and the distinction matters for how the community responds to it. It is not a claim that any individual man has abandoned anyone, and it is not a claim that any individual woman is buying a home out of desperation rather than ambition — both things NAR’s own qualitative data contradict, since single women report treating homeownership as a deliberate, prioritized financial goal, not a fallback. It is a claim that the aggregate pattern has a structural driver worth naming honestly, because institutions built to respond to “women choosing wealth-building” and institutions built to respond to “a rising share of women building wealth alone because the partnership market has structurally narrowed for them” are not the same institutions, and African America needs the second kind at least as much as the first.

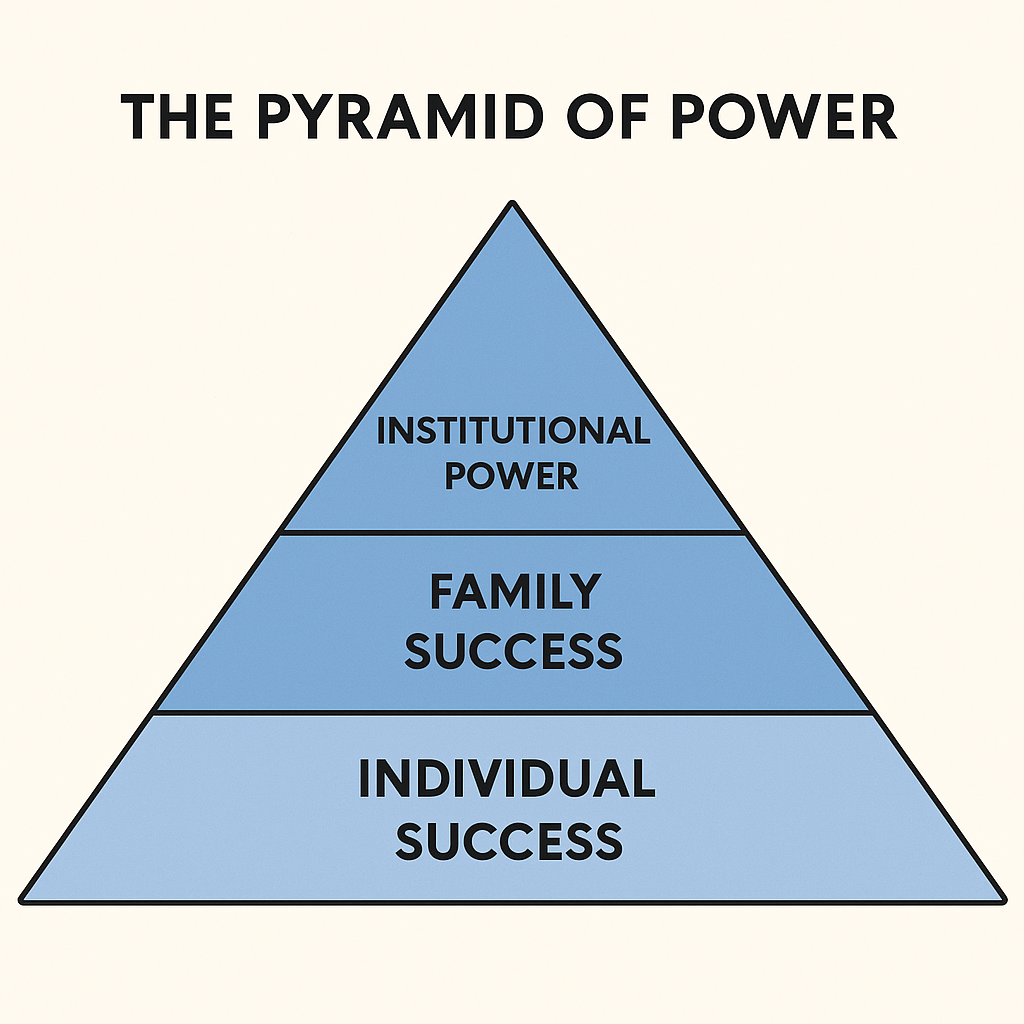
Every functioning institution has a balance sheet, a division of roles based on comparative advantage, and a mechanism for retaining and compounding the capital that enters it. HBCU Money applies this logic routinely to banks, universities, and credit unions. It applies with equal force to the family and it requires the family, as an institution, to be designed for two distinct entry conditions rather than one: capital entering through a partnership, and capital entering through a woman building alone who may or may not partner later. A family-governance framework that only knows how to receive equity once a marriage has already formed is a framework that fails a growing share of the very women generating the equity it is supposed to hold.

Where partnership does form, the economics remain exactly as favorable as they were before this data was added to the picture. A household in which one partner already holds home equity is not a household where one officer outranks another; it is a balance sheet that begins with collateral instead of without it, refinanceable into business capital, deployable as a down payment on a second unit, combinable with a partner’s income to acquire block-level property neither could reach alone. None of that requires the man’s asset to arrive first or match hers in size; it requires a governance norm that allocates roles by comparative advantage rather than gender-coded ego, the same norm any competently run institution already applies to its officers. The men who read a partner’s equity as a threat rather than as capital entering the household are the ones least equipped to benefit from precisely this kind of coordination.

But the institutional response cannot stop at “coordinate better once partnered,” because the data says a meaningful and growing share of the ecosystem’s most credentialed women will be building wealth solo, for a period that may not be temporary. That is where African America’s institutional thinness compounds the problem. A Black-owned bank or credit union — a Citizens Trust, a OneUnited, a Hope Credit Union — is well positioned to build savings and refinance products for solo women building equity as a first-class household unit, not merely as a pre-partnership placeholder waiting to merge into someone else’s balance sheet. Family governance infrastructure; trusts, estate documentation, succession planning for how a solo-acquired home transfers to children, siblings, or reinvests into a next acquisition has to be built around the reality that a growing number of these estates will not have a second adult name on the deed, ever. HBCU business and law programs at Tougaloo, at Fort Valley State, at Coppin State, at Savannah State are positioned to teach family financial governance as a competency that includes solo wealth-holding as a designed-for outcome, not an edge case.

None of this changes the invitation at the center of this piece. A man who understands the full accounting, that Black women are buying homes at a record pace both because they are choosing to and because a structurally contracting partner pool makes solo acquisition a rational institutional hedge has more reason to be inspired, not less. Her closing is not a verdict on him individually; in aggregate, it is a population-level response to conditions that include, among other things, the very intermarriage pattern concentrated among men with his own credentials. That 12-point gap among the overall population widens to 17 points among the college-educated, unmatched by any other racial group in the country, and grows precisely with the credentials, a bachelor’s degree, a stable income, that also predict homeownership readiness. The honest response to that accounting is not resentment and it is not denial. It is building the coordination where partnership exists and building the infrastructure to support solo wealth-holding where it does not because both are now permanent features of the same institutional landscape, and the family, understood as an institution, has to be designed for both.

Maggie Lena Walker did not build her bank for women who were waiting on a partner to arrive before their savings counted. She built it to hold the capital of women who were already building, on whatever timeline their circumstances gave them. The single Black woman closing on a home in 2026 has done her part twice over; she has cleared discriminatory underwriting alone, and she has done it inside a marriage market that data shows is measurably tighter for her than for women of any other group. Whether that asset becomes the founding capital of a functioning family institution, or simply one more well-earned equity position with no institutional structure built to receive it, depends on whether the ecosystem is honest enough to build for the conditions that actually produced it.

Disclaimer: This article was assisted by ClaudeAI.
Raising Builders, Not Just Dreamers: Why African American Parenting Needs a New Blueprint Rooted in Institutional Power

“If you raise your children to be happy, they may or may not be productive. But if you raise them to be productive, happiness tends to follow. Not the fleeting kind, but the self-earned kind.” — William A. Foster, IV

In 1867, a formerly enslaved family in the Alabama Black Belt pooled its first wages into a single ledger kept by the eldest daughter, who could read. Every dollar earned by every member of the household was recorded, and every dollar spent required a reason written beside it. Within a decade, that ledger had financed forty acres, a one-room schoolhouse, and tuition for two children at a normal school two counties over. The family did not think of itself as remarkable. It thought of itself as an operation. That distinction between a family that raises individuals and a family that runs an institution is the one African America has largely lost, and it is the one this generation of parents must recover.

The debate over how to raise Black children has, in recent years, narrowed into a contest between two imported frameworks. One is gentle parenting, an approach built around emotional attunement, negotiated boundaries, and the primacy of the child’s internal experience. The other is the disciplined, achievement-maximizing model popularized under the label “tiger parenting,” associated with East Asian immigrant households and organized around the assumption that excellence must be engineered, not discovered. Both frameworks have something to offer. Neither was built for the problem African America actually has, which is not a deficit of individual achievement but a deficit of institutional ownership and neither, notably, asks what a child owes to anything larger than a household.

This is a structural distinction, not a rhetorical one. African American households have, over the past sixty years, produced physicians, engineers, federal judges, university presidents, and Fortune 500 executives at rates that would have been unimaginable to the family keeping that 1867 ledger. And yet the balance sheet of the community as a whole; its share of bank assets, its landholdings, its endowed research capacity, its control of the institutions that educate, capitalize, and govern it has not moved in proportion to that individual advancement. The gap between individual credentialing and institutional ownership is the central economic fact of postwar Black America, and it is a fact that parenting philosophy, as currently imported and debated, does nothing to address.

The reason is straightforward. Gentle parenting and tiger parenting are both, at bottom, individual-optimization frameworks. They differ on method where one prioritizes emotional regulation, the other prioritizes output but they share an assumption: that the unit of success is the child, and that the family’s job is to produce the best possible version of that child for the child’s own benefit. Neither framework asks what the child owes back to the institutions that produced them, or what the family itself is building as an ongoing concern. A household organized around either model can raise a child into a six-figure salary and a rented apartment in a city with no connection to the family’s origin, and count that as complete success. Historically, African American households did not have the luxury of treating the family as merely a launching pad for individual departure. The family was itself an institution, often the only one fully under Black control, and children were raised as its future officers, not its former residents.

What African American families need, then, is not a synthesis of two individual-optimization models but a third model organized around a different unit of analysis: the household as an institution with a balance sheet, a governance structure, and a multigenerational mandate. But the household cannot be the terminal unit in this model, and this is where most versions of “legacy-minded” parenting stop short. A family that builds its own capital and stops at its own front door has replicated, at smaller scale, the same isolation that has weakened Black institutions generally; a landholding without a bank, a bank without a university, a university without a diaspora partner. The household is the first institution in a chain, not the last one, and children raised inside it need to understand early that the chain runs outward: from family, to the Black-owned bank or credit union that holds the family’s deposits, to the HBCU or community institution that trained its members, to the broader network of African-descended institutions on the continent and across the Diaspora that this ecosystem is, whether acknowledged or not, already entangled with.

This outward extension is not sentimental. Diaspora institutions; universities, exchanges, development banks, and enterprises across what this publication designates Africa Core represent both a market and a set of potential partners that African American capital has been almost entirely absent from, even as African American households have accumulated more collective wealth than at any point in the community’s history. A family that trains its children to think only as far as the neighborhood or the HBCU that produced them is training them to operate inside a smaller institutional universe than the one actually available to them. A family that trains its children to understand Africa Core institutions as legitimate strategic partners; not as a heritage destination or a charitable cause, but as counterparties in trade, education, and finance is preparing them for a considerably larger field of institutional play. This is a matter of literacy as much as intention: a child who can explain why an African Depository Receipt structure might allow a Black-owned enterprise to list on an African exchange has a materially different frame than one who was simply told to “know their African history.”

This reframes what “cultural confidence” should mean inside the household. It is common, and not wrong, to want children to know Black history and African history. But that knowledge functions very differently depending on whether it is transmitted as heritage or as strategy. A child who knows that the Mali Empire under Mansa Musa possessed wealth on a scale historians still struggle to estimate, but does not also understand why that wealth left no durable institutional apparatus behind it, has learned a fact without learning the lesson. The lesson is that capital without institutions is temporary, however large it is at its peak — a lesson equally applicable to a family’s household wealth and to a civilization’s. Children raised with this frame do not treat diaspora history as content to be proud of; they treat it as a cautionary case study in what their own family and community are still at risk of repeating.

Several concrete practices distinguish this model from either import, and each one now needs a diaspora dimension that is usually missing. The first is treating family meetings as governance rather than logistics; regular sessions, monthly is typical among families that sustain this practice, in which children are present for real discussion of what the family owns, owes, and is building toward. Extended properly, these meetings also address where the family’s capital sits in relation to Black-owned financial institutions rather than mainstream white-owned lenders by default, and whether any portion of family investment, however small, is directed toward diaspora-linked opportunity rather than exclusively domestic and mainstream markets.

The second practice is treating a child’s education and career as a capital allocation decision made by the household, with the question reframed from “what do you want to be” to “what institution or system do you want to be capable of building or running” and that system should be understood to include Africa Core institutions as a live option, not an afterthought. A child who becomes a physician under this model might be asked not only whether the family should fund a scholarship at the HBCU that trained them, but whether a medical partnership or exchange with an African Core institution is within reach. Fisk, Xavier of Louisiana, Meharry, and Morehouse School of Medicine have each supplied physicians into families that made exactly this domestic calculation; very few have extended the same calculation across the Atlantic, and that is the gap this model asks families to close.

The third practice is structuring rites of passage around economic contribution rather than consumption pairing major life transitions with a corresponding step in managing capital, drafting a business plan, or taking a formal role in family enterprise. Norfolk State, Bethune-Cookman, and Alcorn State each sit inside regional economies where family enterprise remains viable, and families near those institutions have more opportunity than most to make this practice concrete.

The fourth practice is explicit instruction in the mechanics of collective capital; family investment clubs, the dangers of heirs’ property and forced partition, the function of a family trust or LLC in holding assets across generations without fragmentation. This is not financial literacy as a slogan; it is mechanism-specific instruction, and the same instruction should extend to the mechanics of diaspora capital circulation, so that a child understands not only how to protect family land in the Mississippi Delta but how African American enterprise might eventually list, trade, or partner across Africa Core markets.

None of this requires treating children purely as instruments, and a household that does so will produce resentment and eventual defection, which defeats the purpose. Emotional security and individual flourishing remain conditions for sustained institutional contribution, not competitors with it. The correction is one of scope as much as sequencing: the mandate a household transmits should not terminate at the family’s own advancement, or even at the advancement of the nearest HBCU or Black bank, but should understand itself as one node in a coordinated ecosystem that includes the full institutional Diaspora.

The comparison that clarifies the stakes is between two children who end up in different relationships to that ecosystem. One child is trained from an individual-optimization frame, secures a strong salary, and directs the returns on that investment toward personal consumption and geographic departure. A second child, raised inside a household organized institutionally and taught to see the Diaspora as a coordinated system rather than a collection of disconnected causes, may follow a similar career path but returns capacity to family, to community institutions, and where the opportunity exists to Africa Core partners as well. Both may report comparable personal satisfaction. Only one outcome adds to the institutional density of African America and the wider Diaspora it is part of.

This is the argument for institutional parenting, and it should be understood as strategic rather than moral: households that stop at their own advancement, or even at their own neighborhood’s advancement, are not failing their children, but they are failing to build the multi-tiered asset base — familial, communal, and diasporic — that the ecosystem as a whole requires to close its institutional-ownership gap. That gap will not close through individual achievement, however impressive it continues to be, and it will not close through household wealth-building that stops at the water’s edge. It closes only when families begin raising children who understand themselves as heirs not just to a household, but to an entire, interconnected institutional Diaspora they are responsible for strengthening.

Editor’s Note: To make this concrete rather than conceptual; a family investment club that currently allocates purely to domestic equities or a home-purchase fund could, without restructuring, designate a small, fixed percentage of new contributions (a family might set this at five or ten percent, reviewed annually rather than left open-ended) to a “Diaspora allocation” line, tracked separately in the club’s ledger the same way a 1867 household ledger tracked land money apart from schooling money. That line does not require access to instruments that do not yet exist. It can fund things available now: a stake in an African American-owned enterprise already doing business in an Africa Core market, a deposit or investment product offered by one of the African American-owned banks or credit unions active in diaspora trade finance, attendance at an Africa Core trade or investment conference where a family member makes direct contact with counterparts on the continent, or a subscription that keeps the family current on African exchange and policy developments rather than reliant on secondhand summary. The point of naming the line item now, while children are still watching the ledger, is not to bet on a future instrument. It is to build the habit of treating the Diaspora as a place the family’s capital already goes, in small and specific ways, so that when larger mechanisms for cross-listing and cross-investment do mature, the household has years of practice allocating toward that horizon rather than a decision to make from a standing start.

Disclaimer: This article was assisted by ClaudeAI.
Building Dynasties: What It Will Take for African American Families to Rise to Power

“control, control of resources, control of self, control of nation, requires preparation — Garveyism was about total preparation.” – Dr. John Henrik Clarke, writing on Marcus Garvey’s philosophy of Black institutional power

In 1952, a mason in Americus, Georgia bought eleven acres with cash he’d saved from three decades of laying brick. He built a house on it, a smokehouse behind it, and a wraparound porch where he told his grandchildren that the land was the family’s now, forever. He died in 1979. By 1994, the eleven acres had been split six ways, sold in fragments to cover a funeral, a divorce, and two bad business loans. Today a subdivision sits where the smokehouse stood. The mason did everything right by the logic he was given: work, save, buy, own. What he lacked was not virtue. It was infrastructure. Nobody had ever taught him that land without governance is just land waiting to be divided.

That story is not an outlier. It is the median outcome. And it is the central argument of this piece: African America’s problem was never a shortage of individual achievement. It is a near-total absence of the legal, financial, and cultural machinery that converts one generation’s success into the next generation’s platform. Until that machinery is built, deliberately and aggressively, every dollar earned by this community will keep dying with the person who earned it.

Start with the scoreboard, because the scoreboard is brutal. The Federal Reserve’s 2022 Survey of Consumer Finances put median Black household net worth at $44,900, against $285,000 for the median White household — a gap of more than six to one, and one that widened in absolute dollar terms even as Black wealth grew faster in percentage terms during the pandemic recovery. Growth rate is a vanity metric when the base is this small. A 60 percent increase on $28,000 is still poverty with better arithmetic. The gap is not closing. It is compounding, in the same way interest compounds, except in the wrong direction.

Now layer on top of that the single largest wealth movement in American history, already underway. Cerulli Associates projects that $84 trillion will pass from the Baby Boomer and Silent Generations to heirs and charities through 2045, the bulk of it concentrated among households that were already high-net-worth. This is not a rising tide. It is an inheritance economy, and inheritance economies reward whoever already has family structures in place to receive, consolidate, and reinvest capital across generations. Families without that structure will watch the transfer happen around them, not to them. The transfer is not going to wait for African America to get its paperwork in order.

This is where the sentimental version of “generational wealth” needs to be retired. Passing down money is not the same as passing down power, and Black America has been sold the former as if it were the latter. Power, as any serious student of the Waltons, the Rockefellers, or the Kochs understands, does not come from an inheritance check. It comes from the entity that controls the check. The Walton family does not merely benefit from Walmart’s success; through Walton Enterprises LLC and the Walton Family Holdings Trust, they collectively control roughly 45 percent of the company’s outstanding shares, a concentrated bloc large enough to determine board composition, executive succession, and long-term strategy three generations after Sam Walton’s death. That is not inheritance. That is institutionalized command, engineered through trust structures, family governance, and a refusal to let ownership fragment. Jay-Z’s net worth impresses a magazine cover. It does nothing for the fortieth Black family down the street, because it is not organized as an institution — it is one man’s balance sheet, subject to one man’s mortality.

The uncomfortable truth is that most families, of any race, fail at this. Research tracked by the Family Business Institute finds that roughly 30 percent of family-owned businesses survive into a second generation, about 12 percent make it to a third, and only 3 percent endure into a fourth. Succession is hard even with capital, even with lawyers, even with three generations of practice at running something. What that data point exposes is not that Black families are uniquely undisciplined — it’s that family continuity is a discipline nobody is taught, and African America has had roughly one-fifth of the time (counting from Emancipation, and accounting for the systematic destruction of Black wealth through redlining, urban renewal, and outright terrorism such as the 1921 razing of Tulsa’s Greenwood district) to build the muscle memory that older American dynasties built over five and six generations. The response to that deficit cannot be more individual grit. It has to be structure, copied deliberately from where it already works, and adapted ruthlessly to this community’s actual starting conditions.

So build the structure. A family constitution — a written document specifying mission, capital rules, and succession mechanics — costs nothing but discipline and an afternoon with a competent estate attorney, yet almost no Black family has one, while every dynasty mentioned above treats theirs as more binding than a corporate bylaw. A family office does not require billionaire assets to justify its existence; pooled family capital in the low six figures is sufficient to retain a fee-only advisor, establish an LLC or trust structure, and begin making coordinated decisions across a real portfolio — brokerage accounts, retirement vehicles, business equity, insurance-funded trusts, even royalty and intellectual-property streams — instead of six relatives each managing a fragment of the same family’s capital in isolation. Land is one asset class among several and should be governed the same way the rest are: never liquidated to cover an emergency when it could instead be collateralized, folded into a trust, or held alongside an equity stake in a family business and a diversified investment account, each professionally managed rather than administered by whichever relative answered the phone first.

None of these families stayed inside their founding asset. Koch Industries began as a part-interest in a single Minnesota oil refinery bought out in the 1940s and 1960s; under Charles Koch it diversified deliberately into pipelines, fertilizer, pulp and paper, ranching, glass, electronics, and commodities trading, so that no single market downturn — a refining glut, a paper-price collapse, a bad cattle season — could touch the whole estate at once. The Rothschilds began as court bankers to European nobility in the 1760s and, over two centuries, moved family capital into railways, mining, real estate, energy, and, notably, wine estates like Château Lafite and Château Mouton — acquired not as hobbies but as productive, appreciating assets that diversified the family’s holdings away from the banking sector that made them. Even the Waltons, whose fortune is most associated with a single company, don’t hold it as a single asset: Walton Enterprises runs its own internal investment arm allocating family capital into private equity, real estate, and outside ventures entirely apart from Walmart stock, precisely so the family’s fate isn’t fused to one retailer’s stock price. In every case, the founding asset became the seed capital for a portfolio, not the permanent shape of the estate. That is the model the eleven acres in Americus should be measured against. The land was never meant to be the ceiling of that family’s wealth — it was meant to be collateral for the next asset, security for a loan into a business, a hedge alongside a brokerage account, one holding in a portfolio instead of the whole of it. Held that way, structured that way, it doesn’t matter whether the estate a family passes down began as land, a barbershop, a nursing license, or a pension. What matters is whether it was ever allowed to grow past its origin.

None of this is exotic. It is standard operating procedure for every dynasty this essay has named. It has simply never been marketed to African America as something within reach, because the wealth management industry profits more from selling individual products than from building family institutions that don’t need it.

Institutions of the wider Black ecosystem have a direct, self-interested role here, and this is where the case must be made in dollars, not sentiment. A Black-owned bank or credit union that captures family trust deposits and estate accounts gains stable, patient capital instead of transactional balances. A historically Black college or university that structures a real endowed-chair or scholarship-naming relationship with a family — rather than accepting a one-time gift — gains a recurring donor relationship spanning generations rather than a single tax-season transaction. Fisk, Tougaloo, Dillard, and Xavier of Louisiana have decades of experience cultivating exactly this kind of multigenerational donor family; Alcorn State, Coppin State, Savannah State, Bethune-Cookman, Norfolk State, Delaware State, Fort Valley State, and Morgan State could each become the anchor institution for a rising family dynasty if they pursued the relationship as deliberately as the Rockefellers pursued the University of Chicago or the Dukes pursued the university that bears their name. The institution that captures a family early, before its capital scales, is the institution that owns the relationship when that capital multiplies. This is not charity. It is customer acquisition, and any HBCU treating it otherwise is leaving its own endowment on the table.

The same logic extends past the water’s edge. Diaspora capital coordination — joint investment vehicles linking African American family offices with counterparts in the Caribbean and across Africa Core — is not a symbolic gesture toward Pan-Africanism. It is a hedge against the concentration risk of building wealth inside a single, historically hostile domestic market. A family real estate or infrastructure fund co-managed across African American, Jamaican, and Ghanaian family offices diversifies political risk, currency exposure, and asset class in one structure, while building exactly the kind of institutional density and strategic coordination that isolated, single-country family wealth can never achieve alone.

None of this happens through moral appeal, and this publication has no interest in making one. Appeals to racial solidarity have moved conferences and Twitter timelines; they have not moved balance sheets. The case for family institutionalization has to be made the way the Waltons, the Kochs, and the Wallenbergs made it to their own descendants: this structure protects what you have from your own children’s mistakes, from probate courts, from market volatility, and from the actuarial certainty that someone in every family eventually dies without a plan. Estate planning is not morbid. It is the single highest-leverage act of institution-building available to a family with under a million dollars in assets, and it costs less than a used car.

There is also a governance failure hiding inside the sentimental version of Black wealth-building that deserves direct confrontation. Families that treat wealth distribution as an equality exercise — splitting everything evenly among heirs regardless of role, competence, or commitment — are optimizing for fairness at the expense of survival. The Family Business Institute’s own data on why family enterprises collapse points overwhelmingly to succession disputes and undefined governance, not lack of capital. A family that assigns real roles — someone accountable for investment decisions, someone accountable for philanthropic strategy, someone accountable for legal and tax exposure — and backs those roles with actual authority, not just a title at Thanksgiving, will outlast a family that insists every cousin gets an equal, undifferentiated vote on every decision. Institutions require hierarchy. Families building institutions will have to get comfortable with that, however uncomfortable it sits against a cultural instinct toward flattened, communal decision-making.

The alternative to all of this is not neutral. It is continued erosion. Every family that fails to formalize governance sends its capital back into the undifferentiated churn of individual consumption — the paycheck model this publication has criticized elsewhere, in which wealth is treated as something to be spent rather than something to be commanded. Every dollar that leaves the Black institutional ecosystem through an unplanned estate, an uninsured death, or a liquidated piece of land is a dollar the next generation has to earn from zero, while families with institutional infrastructure simply compound what they already hold. The compounding gap in the Federal Reserve’s data is not an accident of history. It is the visible output of one set of families running institutional software and another set running none at all.

The mason in Americus did not fail his family. He succeeded at everything available to him in 1952, in a state where a Black man building wealth at all was itself an act of defiance. What failed him was the absence of a structure that could have held what he built past his own lifetime, and the absence of a plan to let that first asset become seed capital for a second and third — a trust, a governance document, a designated successor with both the authority and the training to keep the estate whole and growing, whatever form that estate took or became. That absence is fixable, at a scale of millions of families, in this generation, and it applies as much to a brokerage account or a stake in a family business as it does to eleven acres of Georgia clay. The Kochs turned one refinery into a dozen industries. The Rothschilds turned a banking desk into vineyards and mines. Neither family mistook where they started for where they had to stay. It requires no act of Congress and no act of philanthropy from outside the community. It requires families to stop organizing themselves as clusters of individuals bound by affection, and start organizing as institutions bound by structure, because affection does not survive probate court and structure does. The eleven acres are gone. Whatever the next generation holds — land, equity, a business, a portfolio, or something none of them have thought to build yet — does not have to stop there, and does not have to follow them into the ground.

Disclaimer: This article was assisted by ClaudeAI.