Tag Archives: Black-owned banks

No Group Works Less for Itself Than African Americans: Just 8% of Black Workers Are Employed by Black-Owned Firms

“When an African American earns $1.00 with our labor, there is an owner that earns $1.20 in operating income from ownership of the vessel and they get to count said vessel as an asset. This means when we do not work for firms from our own community, then the bulk benefit of our talents are still rewarding Others. That reality does not change whether we are earning $80,000 or $8 million. Individual talents are always building up institutional wealth, the question is for our own community or someone else’s.” – William A. Foster, IV
A river does not ask where its water goes. It simply runs, cutting canyons, carrying silt, turning turbines wherever the engineers have built them. For a hundred years, a river ran through a valley and lit every town along its banks, except the town it rose from. That town kept its lanterns. It sent its water downstream and called the arrangement progress, because the workers who built the dam drew a wage, and a wage, everyone insisted, was the same as owning the river. It was not until the town tried to build its own turbine that it discovered the difference: a wage ends when the shift ends. A turbine keeps generating current long after the worker who built it has gone home.

That difference between generating value and owning the mechanism that captures it is the entire story embedded in a figure from Pew Research Center’s analysis of federal business data that ought to stop every Black economist and institution builder in their tracks: Black-owned employer firms in the United States employed roughly 1.6 million workers in 2022, with annual payrolls estimated at $61.2 billion, according to Pew’s review of Census Bureau survey data. Set against the more than 20 million Black Americans in the labor force, that 1.6 million figure is not a success statistic. It is a containment statistic. No group in America works less for itself than African Americans and not because Black workers labor any less than anyone else, but because so little of what that labor builds accrues to institutions Black America actually owns. The river runs. The valley stays dark.

The economist Claud Anderson gave this dynamic its plainest possible name three decades ago in Black Labor, White Wealth: The Search for Power and Economic Justice, arguing that American wealth was built substantially on Black labor under slavery and Jim Crow and has been sustained since through policy and practice that keeps that labor’s output flowing into someone else’s balance sheet rather than its own. Anderson’s proposed remedy, which he later formalized through his organization, the PowerNomics Corporation of America, was not a moral appeal either it was a group-economics strategy aimed squarely at ownership and capital control rather than participation and goodwill. The employment and ownership figures that follow are the modern receipts for exactly the imbalance Anderson named in 1994, updated with three additional decades of federal data that show the imbalance persisting in remarkably precise form.

This is not a moral argument. It is a capacity argument, and the distinction matters, because HBCU Money has never found the moral case persuasive to the people who control capital allocation, and neither should we expect it to be. The self-interest case is the only one that survives contact with a boardroom: an ecosystem that does not own the firms employing its own labor cannot retain the capital that labor generates, cannot direct where that capital gets reinvested, and cannot build the institutional density required to negotiate as a bloc rather than beg as individuals. Ownership is not a symbolic preference. It is the only mechanism by which labor output converts into compounding capital instead of a paycheck that clears and disappears.

Start with the scale problem, because it is worse than the employment figure alone suggests, and it is worse specifically relative to every other ownership group tracked by the federal government. According to the U.S. Census Bureau’s most recent release on business owner characteristics, Black or African American-owned firms account for 3.4% of U.S. employer businesses, up from 2.7% just two years earlier per Brookings’ analysis of the Annual Business Survey — real movement, but movement from a base so small it barely changes the fundamental picture. Put the ownership share next to the population share and the comparison sharpens considerably: Brookings researchers Andre Perry, Manann Donoghoe, and Hannah Stephens found that in 2021, white Americans owned 82% of employer businesses while representing 72.5% of the population, its ownership exceeding population share by nearly ten points. Asian Americans owned 10.9% of employer businesses against a 6.3% population share — again, ownership exceeding population. Black Americans owned 2.7% of employer businesses against a 14.4% population share, and Hispanic or Latino Americans owned 6.9% against a 19.1% population share, both groups locked well below proportional representation, with Black America carrying the widest gap of any racial category Brookings measured. That is not a rounding error. It is a four-to-one to five-to-one density gap between population share and ownership share depending on which year you measure, and it is the single most important number in this entire conversation, because density is what everything else depends on.

The size distribution inside that 3.4% makes the containment tighter still, and here the comparison across ownership groups is unusually clean because the federal data measures the same thing the same way for everyone: what share of each group’s businesses employ nobody at all. Per the same Brookings analysis of Census sole-proprietorship data, Black-owned businesses are the most concentrated of any racial group at that zero-employee scale where 96.3% are sole proprietorships with no paid staff, compared with 92.4% for both Hispanic/Latino-owned and Native American-owned firms, and 81.1% for white-owned firms and 80.1% for Asian American-owned firms. Run the comparison from the employer side and, per Pew’s analysis, it holds just as tightly: about seven-in-ten Black-owned employer firms had between one and nine employees in 2022, a concentration at the smallest possible operating scale that leaves the ownership tier structurally unable to absorb meaningful shares of the available Black labor force even if every one of those firms doubled tomorrow.

The dollar-value version of the same gap is, if anything, more damning, because it isn’t about headcount at all, it’s about what each firm is actually worth once it exists. Using the Census Bureau’s most recent figures, white-owned employer firms generated roughly $17.0 trillion in combined receipts across 4.8 million firms, an average of about $3.5 million in receipts per firm. Black-owned employer firms generated $249.0 billion in combined receipts across 201,000 firms, an average of roughly $1.2 million in receipts per firm, meaning the typical white-owned firm generates nearly three times the revenue of the typical Black-owned firm. Asian-owned firms averaged about $1.75 million per firm and Hispanic-owned firms about $1.47 million, both ahead of the Black-owned average as well.

Two further measurements explain why that revenue gap exists rather than merely documenting that it does, and both point to the same conclusion Anderson reached in 1994: the constraint is access, not capacity. The first is sector composition. Per Pew’s sector breakdown, Black-owned employer firms are concentrated in health care and social assistance (26% of all Black-owned firms), professional and scientific services (14%), transportation and warehousing (9%), administrative and waste management services (8%), and retail and food service (7% each) — sectors that require comparatively little startup capital and generate correspondingly modest revenue per firm. Black ownership is nearly absent from the industries that produce the highest revenue per firm precisely because those industries — utilities, wholesale trade, heavy manufacturing — demand the largest upfront capitalization to enter at all; Brookings researchers note that a 2018 federal survey recorded a total of just 18 Black-owned businesses nationally in the entire utilities sector. Economist Robert Fairlie’s research for the National Bureau of Economic Research finds the same pattern from a different angle: roughly 18% of Black workers are employed in innovation-intensive industries compared with 22% of white workers, and even among Black workers already employed inside them, only about 9% go on to own a business in that industry compared with roughly 14% of white workers in the same position. Tellingly, a study by the Initiative for a Competitive Inner City found that where Black-owned manufacturers do exist inside tracked supply chains, they are on average larger than the white-owned manufacturers in those same chains, the clearest available evidence that this is a barrier to entry, not a deficit of competence, ambition, or business acumen.

The second measurement is the investor class itself, and here the gap dwarfs everything discussed so far. Per Crunchbase data, Black-founded startups received roughly 0.4% of all U.S. venture capital in 2024, down from a 2021 peak of 1.3%, and according to HBCUvc’s quarterly funding tracking, only 17% of Black-founded deals that do get funded reach a Series A round, compared with 37.7% of funded deals overall meaning the small number of Black-founded firms that clear the first hurdle are roughly half as likely to clear the second one. The lending side of the ledger shows the identical pattern in a different market: the Federal Reserve’s Small Business Credit Survey finds Black-owned firms denied credit at roughly 39%, more than double the 18% denial rate for white-owned firms, and a 2021 Federal Reserve Bank of New York report found Black-owned firms independently rated low credit risk were approved for full financing at close to the same rate as high-risk white-owned firms.

But the venture and lending statistics both describe capital that a firm is applying for from someone else. The layer underneath both of them is capital a founder never has to apply for at all, because it comes from their own household or their own network before any bank or investor is ever approached and this is where the wealth gap already documented in this piece does its most permanent damage. According to Google for Startups’ own reporting on the pre-seed funding gap, the average U.S. startup launches on a friends-and-family round of $100,000 to $150,000, drawn from founders’ personal savings and the people closest to them; for Black founders, that figure averages closer to $35,000. Measured on a liquid-wealth basis stripping out home equity, since a house cannot be cashed out to fund a check, a 2023 analysis by Fifth Star Funds put the white-to-Black wealth ratio at roughly twenty-two-to-one, meaning a Black founder trying to raise a typical $23,000 friends-and-family round would need to draw on the entire liquid wealth of six Black families to do it. A firm that cannot clear this round never reaches the point of being denied a bank loan or passed over by a fund; it simply launches undercapitalized, if it launches at all, and stays capped near sole-proprietor scale for the rest of its life which is a large part of why it stays there. The historical contrast needs no editorializing: Bloomberg’s reporting on Amazon’s founding, later summarized by Newser, found Amazon’s 1995 seed round included $245,573 personally invested by Jeff Bezos’s own parents, Jackie and Mike Bezos. And per multiple retellings of Google’s founding, including Celebrity Net Worth’s account of its earliest investors, Google’s first outside money, three years later, arrived as $100,000 personal checks from Stanford computer science professor David Cheriton and Sun Microsystems co-founder Andy Bechtolsheim, written before the company was even legally incorporated, followed within weeks by a $250,000 personal investment from Bezos himself. No institution of any kind was involved in either case. The capital that mattered most was already sitting in a family’s bank account.

The handful of Black-led investment vehicles that do exist compound this problem rather than solve it, and the reason is worth stating plainly rather than glossing over: Black households cannot yet supply enough investable wealth to anchor those funds as limited partners, and Black institutions — banks, credit unions, HBCU endowments, pension-adjacent capital pools — are not yet large enough collectively to do it either. A Black general partner running a fund capitalized primarily by Others’ foundations, endowments, and pension systems has changed who makes the investment decisions without changing who ultimately owns the return, which means fund formation at the top of the capital stack and household wealth at the bottom of it are not two separate problems. They are the same institutional density gap, expressed at two different altitudes.

Five separate measurements now point at the same wall: Black-owned firms are underrepresented in raw count relative to population, overrepresented at the smallest employee-size tier, smaller in average dollar value, concentrated in the lowest-capital sectors, and shut out of the personal, venture, and institutional capital that would move a firm generating $1.2 million in revenue toward the $3.5 million white-owned average. Five measurements, one underlying constraint.

The historical context here is not ancient, and it runs on two tracks that arrive at the same conclusion from different directions. Where Anderson traced the mechanism backward through slavery and Jim Crow policy, the sociologist Thomas Shapiro traced it forward through household balance sheets a decade later, arguing in The Hidden Cost of Being African American that income and wealth are not the same variable, and that the persistence of racial inequality runs through the asset side of the ledger rather than the wage side. Employment, even full employment, even rising Black employment, does not close a wealth gap if the employer capturing the surplus value of that labor sits outside the community. This is precisely why the Federal Reserve’s Survey of Consumer Finances, as analyzed by the National Community Reinvestment Coalition, shows the gap widening in dollar terms even as it narrows in percentage terms: median Black household wealth rose from roughly $28,000 to $44,900 between 2019 and 2022, but median wealth overall rose enough that the absolute gap between Black and white households actually grew by nearly $50,000 over the same period. By 2022, the median white household held $284,310, more than six times the $44,100 held by the median Black household. Labor income is necessary. It has never been sufficient. A wage is a flow; a firm is a stock. You cannot out-earn a four-to-one ownership density gap through salary alone, no matter how many Black workers show up for shifts at other people’s companies.

There is a growth signal worth taking seriously here, and HBCU Money should not undersell it even while insisting the baseline remains inadequate. Per Census Bureau data reported by Governing, the number of Black-owned employer businesses grew nearly 57% between 2017 and 2022, and Black-owned firms accounted for more than half of all new employer businesses started nationally in that period. In the most recent year-over-year comparison available across all racial groups, Brookings found Black-owned employer businesses posted the largest percentage increases in employee count, revenue, and payroll of any group tracked employee growth of 7%, revenue growth of 30%, and payroll growth of 27%, each figure running 5 to 10 percentage points ahead of white, Asian American, and Hispanic firms over the same year. Formation is not the same as capacity, however, and the arithmetic of closing a base this small is unforgiving: Brookings analysts estimate it would take roughly 700,000 additional Black-owned employer firms to bring ownership into line with Black population share, representing an estimated $800 billion in additional revenue and 6 million additional jobs and that at the pace of the single best growth year on record, full parity remains roughly 100 years away.

The strategic implications follow directly from the density problem, and this is where the four throughlines this publication returns to — institutional density, capital retention, talent concentration, and strategic coordination — stop being abstractions and start functioning as a diagnostic. Institutional density is the root constraint: 201,000 Black-owned employer firms against 5.9 million total U.S. employer firms, per the Census Bureau, means the ecosystem simply does not have enough vessels to hold its own labor, and those vessels that do exist are smaller both in headcount and in revenue than their counterparts in every other ownership category and are locked, disproportionately, into the sectors and financing markets least able to change that. Capital retention fails as a direct downstream consequence. Talent concentration is the third casualty: the most capable Black managers, engineers, and operators in the country are overwhelmingly employed inside institutions Black America does not control. And strategic coordination; the ability to move Black labor, Black capital, and Black institutional leadership as a single directed force, precisely the coordination Anderson’s PowerNomics called for cannot exist at scale when the typical Black-owned firm is roughly a third the revenue size of the typical white-owned firm, is concentrated outside the industries capable of scaling, has almost no access to personal, venture, or institutional growth capital, and when 92 of every 100 Black workers punch in somewhere the community has no ownership stake in the firm.

This is where the banking and credit union infrastructure this publication tracks obsessively becomes the actual lever, not a side note though it is now clear that lever needs a second one built alongside it. According to HBCU Money’s own 2025 African American-Owned Bank Directory and African American-Owned Credit Union Directory, there are 17 African American-owned banks in the country holding roughly $6.72 billion in combined assets, and 205 African American-owned credit unions holding roughly $8.15 billion across nearly 727,000 members, a combined $15 billion in institutional balance sheet capacity sitting underneath a labor force generating tens of billions in annual wages that mostly clears through mainstream white-owned lenders instead. Only a small fraction of HBCUs and PBIs themselves bank with African American-owned institutions, per that same directory data, a fact that should embarrass every finance department at every one of the 100 plus federally designated HBCUs and PBIs. But deposit infrastructure alone cannot close the sector-composition gap, the friends-and-family gap, or the institutional-capital gap, those require a growth-equity layer this ecosystem still largely lacks, and building it will require Black institutional balance sheets to grow enough to anchor it themselves, not simply put a Black name on someone else’s money.

Business schools at institutions like Fort Valley State, Chicago State, Grambling, and Norfolk State are training a pipeline of Black finance, accounting, and management talent every year, talent that overwhelmingly gets absorbed into the same non-Black employer base generating the 1.6 million versus 20 million imbalance Pew’s data documents in the first place. The concrete institutional solution is not a slogan about entrepreneurship; it’s coordination between four things that currently operate as strangers to each other: the HBCU business school pipeline producing operators, the $15 billion Black bank and credit union balance sheet capacity that can underwrite working capital, an equity and growth-capital layer purpose-built and Black-capitalized to move firms out of the lowest-capital sectors and into the high-revenue ones currently closed to them, and the roughly 200,000 existing Black-owned employer firms that need all three of those pieces to grow past the headcount ceiling, the revenue ceiling, and the sector ceiling that currently trap the median firm below every comparable ownership group.

The employment share figure — 1.6 million out of a labor force many multiples that size — is not a statistic to mourn. It is a target with a number attached, and the comparative data makes the target legible in five dimensions at once: more firms, larger firms, firms worth more per dollar of revenue, firms operating in higher-capital sectors, and firms with actual access to the capital — personal, venture, and institutional — that funds growth. Anderson named this arrangement in 1994. The federal government has spent every year since generating the receipts that prove him right. No group works less for itself than African Americans; not for lack of labor, and not for lack of the firms willing to try, but for lack of the sectors, the capital, and the institutions built to keep that labor’s output at home.

Disclaimer: This article was assisted by ClaudeAI.
Homeownership and Power: Why African American Men Should Be Inspired—Not Intimidated—By African American Women Who Buy Homes

Black men like all men need to recognize that their worth in a relationship is and should be more than financial. That being said, for African America who has never reached 50% homeownership rate, to have men upset is on a level of a Eddie Murphy comedy – or Shakespeare tragegy. Take your pick. — William A. Foster, IV

In 1903, Maggie Lena Walker chartered the St. Luke Penny Savings Bank in Richmond, Virginia, becoming the first woman of any race in the United States to found and preside over a bank. She did not build it as a monument to her own ambition. She built it as infrastructure, a vessel through which the pennies of domestic workers and laundresses could become mortgages, storefronts, and a department store on Broad Street. Walker understood a principle African America has had to relearn in every generation since: an asset only compounds if there is an institution designed to hold it. A single woman’s initiative was never the story. The structure she built around it was.

That principle — asset first, institution second — is the correct lens for a trend now reshaping African American household formation, and it is being widely misread as a referendum on Black manhood rather than what it actually is. According to the National Association of Realtors’ 2025 Profile of Home Buyers and Sellers, single women account for 39 percent of all Black home purchases, nearly matching the 42 percent share held by married couples and far exceeding the single-women share among White (20 percent), Asian American/Pacific Islander (19 percent), or Hispanic (18 percent) buyers. NAR’s deputy chief economist Jessica Lautz notes that Black women have consistently outpaced women of every other racial and ethnic group as homebuyers — a pattern she attributes to a demographic “leaning especially hard on property as a tool for long-term wealth and stability.”

That explanation is accurate as far as it goes, but a rigorous accounting of the data requires a second layer Lautz’s framing does not reach: is this trend driven primarily by preference, or is it also driven by a contracting marriage market that leaves a growing share of Black women building wealth alone by structural necessity rather than by choice? Both can be true simultaneously, and treating them as mutually exclusive is the same interpretive error HBCU Money has flagged before when Black men cite the 75 percent figure, the share of married Black men wed to Black women, as proof that no structural shift is underway in Black partnership formation. That figure is real. So is the fact that Black men have posted the fastest-growing intermarriage rate of any male demographic group in the country, tripling from 8 percent of newly married Black men in 1980 to 24 percent by 2015, concentrated heavily among the most educated and highest-earning men. Among newly married Black adults overall, the gender gap in intermarriage runs 12 points in men’s favor — 24 percent of men to 12 percent of women. Among college graduates specifically, that gap widens to 17 points: 30 percent of Black male college graduates intermarry, against 13 percent of Black female college graduates.

Read against the NAR data, this is not a coincidence sitting beside another coincidence. It is one mechanism producing two visible outcomes. A marriage market in which credentialed Black women face a same-race partner pool contracting faster than any other group’s, compounded by incarceration’s well-documented effect on the available Black male population and a decades-long educational attainment gap that has moved decisively in women’s favor, is a marriage market with a measurable supply-demand imbalance on the women’s side of the ledger. Homeownership is one of the few asset classes a person can acquire entirely alone, without waiting on a partner who may not arrive on the expected timeline or at all. Framed this way, the surge in single Black women’s home purchases looks less like elective wealth-building and more like an institutionally rational hedge against a partnership market that is not behaving the way it does for other groups of women.

This is an accounting, not an accusation, and the distinction matters for how the community responds to it. It is not a claim that any individual man has abandoned anyone, and it is not a claim that any individual woman is buying a home out of desperation rather than ambition — both things NAR’s own qualitative data contradict, since single women report treating homeownership as a deliberate, prioritized financial goal, not a fallback. It is a claim that the aggregate pattern has a structural driver worth naming honestly, because institutions built to respond to “women choosing wealth-building” and institutions built to respond to “a rising share of women building wealth alone because the partnership market has structurally narrowed for them” are not the same institutions, and African America needs the second kind at least as much as the first.

Every functioning institution has a balance sheet, a division of roles based on comparative advantage, and a mechanism for retaining and compounding the capital that enters it. HBCU Money applies this logic routinely to banks, universities, and credit unions. It applies with equal force to the family and it requires the family, as an institution, to be designed for two distinct entry conditions rather than one: capital entering through a partnership, and capital entering through a woman building alone who may or may not partner later. A family-governance framework that only knows how to receive equity once a marriage has already formed is a framework that fails a growing share of the very women generating the equity it is supposed to hold.

Where partnership does form, the economics remain exactly as favorable as they were before this data was added to the picture. A household in which one partner already holds home equity is not a household where one officer outranks another; it is a balance sheet that begins with collateral instead of without it, refinanceable into business capital, deployable as a down payment on a second unit, combinable with a partner’s income to acquire block-level property neither could reach alone. None of that requires the man’s asset to arrive first or match hers in size; it requires a governance norm that allocates roles by comparative advantage rather than gender-coded ego, the same norm any competently run institution already applies to its officers. The men who read a partner’s equity as a threat rather than as capital entering the household are the ones least equipped to benefit from precisely this kind of coordination.

But the institutional response cannot stop at “coordinate better once partnered,” because the data says a meaningful and growing share of the ecosystem’s most credentialed women will be building wealth solo, for a period that may not be temporary. That is where African America’s institutional thinness compounds the problem. A Black-owned bank or credit union — a Citizens Trust, a OneUnited, a Hope Credit Union — is well positioned to build savings and refinance products for solo women building equity as a first-class household unit, not merely as a pre-partnership placeholder waiting to merge into someone else’s balance sheet. Family governance infrastructure; trusts, estate documentation, succession planning for how a solo-acquired home transfers to children, siblings, or reinvests into a next acquisition has to be built around the reality that a growing number of these estates will not have a second adult name on the deed, ever. HBCU business and law programs at Tougaloo, at Fort Valley State, at Coppin State, at Savannah State are positioned to teach family financial governance as a competency that includes solo wealth-holding as a designed-for outcome, not an edge case.

None of this changes the invitation at the center of this piece. A man who understands the full accounting, that Black women are buying homes at a record pace both because they are choosing to and because a structurally contracting partner pool makes solo acquisition a rational institutional hedge has more reason to be inspired, not less. Her closing is not a verdict on him individually; in aggregate, it is a population-level response to conditions that include, among other things, the very intermarriage pattern concentrated among men with his own credentials. That 12-point gap among the overall population widens to 17 points among the college-educated, unmatched by any other racial group in the country, and grows precisely with the credentials, a bachelor’s degree, a stable income, that also predict homeownership readiness. The honest response to that accounting is not resentment and it is not denial. It is building the coordination where partnership exists and building the infrastructure to support solo wealth-holding where it does not because both are now permanent features of the same institutional landscape, and the family, understood as an institution, has to be designed for both.

Maggie Lena Walker did not build her bank for women who were waiting on a partner to arrive before their savings counted. She built it to hold the capital of women who were already building, on whatever timeline their circumstances gave them. The single Black woman closing on a home in 2026 has done her part twice over; she has cleared discriminatory underwriting alone, and she has done it inside a marriage market that data shows is measurably tighter for her than for women of any other group. Whether that asset becomes the founding capital of a functioning family institution, or simply one more well-earned equity position with no institutional structure built to receive it, depends on whether the ecosystem is honest enough to build for the conditions that actually produced it.

Disclaimer: This article was assisted by ClaudeAI.
Where Black-Owned Lending Doesn’t Reach: Mapping the (Primary) Mortgage Gap

“How do we think about buying the home, but not who is supplying the mortgage? The capital, the very thing we constantly say needs to circulate more we give no thought too. We give no thought to who owns the mortgage company, title company, the real estate brokerage company our agent works for. All we know is – we are buying a house and unfortunately we think that is enough and we could not be more wrong.” – William A. Foster, IV

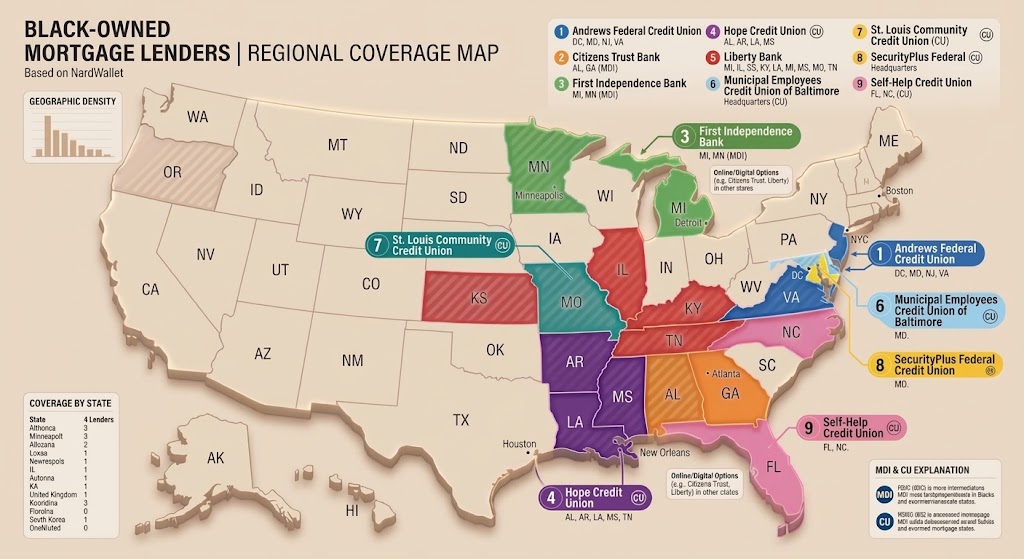
Draw a map of the United States and mark every county with a Black population share above fifteen percent. The shading will run thick down the Mississippi Delta, wrap around the Chesapeake, spill across the Piedmont Carolinas, thicken again in Houston and Dallas, and pool densely in New York, Philadelphia, and the Bay Area. Now draw a second map, this one marking every mortgage lender in America that is actually owned — not merely led, not merely branded, not merely marketed — by African Americans, and actively originating home loans for the house a borrower actually lives in. The second map is nearly blank. Nine dots, clustered in a dozen states, mostly small cities, mostly credit unions. Overlay the two maps and the mismatch becomes the argument: the geography of Black homeownership demand and the geography of Black-owned mortgage capital do not correspond. For most African American home buyers in the country’s largest Black population centers, the choice to bank Black on the single largest financial transaction of their lives does not exist. It was never offered.

This is not a complaint about willingness. It is a diagnosis of capacity. HBCU Money has argued consistently that Black wealth-building runs through institutions, not sentiment, and nowhere is that clearer than in the mortgage market, where the difference between origination by a Black-owned lender and origination by a mainstream white-owned lender is not cosmetic. It is the difference between interest payments compounding inside the African American institutional ecosystem; funding future loans, future branches, future capital reserves and interest payments leaving it permanently, financing balance sheets with no obligation to reinvest. A mortgage is a thirty-year capital-retention decision disguised as a housing decision, and right now the overwhelming majority of that decision is being made by institutions with no stake in Black community reinvestment.

Start with what actually exists. According to NerdWallet’s most recent accounting of lenders serving Black communities, published in January 2026, ten institutions make the list. One of them, Legacy Home Loans, is Black-led and does meaningful volume and it is licensed to operate in twenty-nine states plus Washington, D.C. but it is not Black-owned; it is a nonbank mortgage company, not a depository institution held by African American shareholders or member-owners. It belongs in a different conversation, one about Black executive leadership inside a financial system still substantially owned by others. It should not be counted alongside the nine that are actually owned by African Americans, because ownership, not leadership, is what determines whether profit and reinvestment obligations stay inside the ecosystem or exit it. And even Legacy’s twenty-nine-state reach should be read against the actual scale of the mortgage industry it operates inside: Rocket Mortgage alone originated roughly 429,000 loans worth $116.2 billion in 2025, and the ten largest lenders in the country together accounted for more than a quarter of all mortgage dollar volume originated nationally that year. A single top lender’s annual dollar volume dwarfs the combined asset base of every African American-owned bank and credit union in the country several times over.

The nine that are actually Black-owned are, without exception, small and regional. Andrews Federal Credit Union serves Maryland, New Jersey, Virginia, and Washington, D.C., with a natural base among military members and veterans. Citizens Trust Bank operates out of Atlanta, serving Alabama and Georgia, with a first-time buyer program built on partnership with the Federal Home Loan Bank of Atlanta. First Independence Bank serves Detroit and Minneapolis. Hope Credit Union covers a five-state footprint across the Deep South (Alabama, Arkansas, Louisiana, Mississippi, and Tennessee) with underwriting flexibility built for lower-income borrowers, including ITIN loans for those without Social Security numbers. Liberty Bank has the widest reach of the nine, touching Alabama, Illinois, Kansas, Kentucky, Louisiana, Michigan, Mississippi, Missouri, and Tennessee, and runs a Detroit-specific restoration and acquisition program. Municipal Employees Credit Union of Baltimore and SecurityPlus Federal Credit Union both concentrate on Baltimore. St. Louis Community Credit Union concentrates on St. Louis. Self-Help Credit Union serves Florida and North Carolina, with no-down-payment products designed for borrowers with thin or alternative credit files. What unites all nine, and distinguishes them from the banks discussed below, is that a borrower can walk in the door and finance the home they intend to live in directly with the institution; not a commercial building, not a rental property, not a construction loan against a development, but the primary residence itself.

Compress that list into a set of states and the coverage runs to roughly seventeen states plus the District of Columbia: Alabama, Arkansas, Florida, Georgia, Illinois, Kansas, Kentucky, Louisiana, Maryland, Michigan, Minnesota, Mississippi, Missouri, North Carolina, New Jersey, Tennessee, and Virginia. That is the entire national footprint of Black-owned primary-residence mortgage lending capacity in America.

Now compare it against where African Americans actually live in the largest numbers, and against the fuller picture of where Black-owned banks and credit unions operate at all, primary mortgages or not. Texas holds the largest Black population of any state in the country, concentrated in Houston, Dallas-Fort Worth, and San Antonio. Houston is home to Unity National Bank, and the state carries fourteen active Black-owned credit unions, the fourth-highest count nationally, yet the distinction here has to be precise. Unity does lend against real estate, and lends actively: by its own account, its loan portfolio runs heaviest in commercial and industrial lending, commercial real estate, and small business loans, and it offers financing for owner-occupied and investor commercial buildings, housing development and construction, and SBA-backed acquisitions. What it does not do is originate primary-residence home mortgages directly. Unity’s own materials describe that product as handled “through a trusted third-party partnership” rather than underwritten and held by the bank itself which means a Black family in Houston can finance a commercial building or a construction project through a Black-owned bank, but not, in any direct sense, the house they intend to live in. That is a meaningfully different thing from Citizens Trust, Hope Credit Union, or Liberty Bank actually closing a primary-residence loan in their own name, and it is the precise reason Unity does not appear among the nine even though it is a real, active, community-rooted Black-owned bank. New York tells a related story: no Black-owned bank operates in the state at all, but fifteen active Black-owned credit unions do, the third-highest concentration in the country, serving a Black population that ranks fourth largest nationally and carries the historic institutional density of Harlem, Brooklyn, Buffalo, and Rochester and still, none of those fifteen institutions reach the national primary-mortgage-lender list. Pennsylvania is home to United Bank of Philadelphia, one of the country’s African American-owned banks, and to two of the HBCUs this publication takes care to highlight rather than ignore in Cheyney University, the nation’s first degree-granting HBCU, and Lincoln University, the first degree-granting HBCU for men, yet whatever its lending mix, it does not appear on the active primary-mortgage list either. South Carolina follows a similar pattern: Optus Bank operates out of Columbia, in a state where African Americans make up one of the highest population shares in the country and where Claflin, Voorhees, Allen, Benedict, Morris College, and South Carolina State together form one of the densest HBCU clusters anywhere, but Optus does not appear on that list. California is the thinnest case in this group by far. OneUnited Bank, headquartered in Boston, operates branches and does considerable business in the state, serving a Black population of well over two million people concentrated in Los Angeles, Oakland, and the Bay Area but OneUnited does not offer mortgages anywhere, and California’s own credit union sector amounts to a single active institution holding $318,105 in assets and 262 members, a presence that has contracted since 2016 rather than grown. In each of these five states, the absence is not institutional absence; it is a narrower and in some ways more troubling gap between capital existing, and in some cases lending actively, and that capital being deployed specifically into the primary-residence mortgage product that would make it meaningful to a home buyer rather than a developer or a business owner.

Delaware, Ohio, and Wisconsin sit in a starker category, and two of the three arrived there only this year. Delaware, which by population share ranks among the most heavily African American states in the union and is home to Delaware State University, has no Black-owned bank on record. Ohio, home to Central State University and Wilberforce University, lost its last African American-owned bank, Adelphi Bank, when the institution’s ownership diluted below majority African American control in 2025; a particularly bitter loss because Adelphi had been the first new African American-owned bank chartered anywhere in the country in twenty-three years, and its growing asset base made the loss of ownership control, rather than a closure, the actual wound. Wisconsin’s loss came from the opposite direction: Columbia Savings and Loan Association of Milwaukee, chartered in 1924 and one of the oldest African American-owned financial institutions in the country, survived the Depression, the savings-and-loan crisis, and the 2008 collapse, only to close in 2025 after its capital base finally gave out. Milwaukee’s Black population runs to roughly thirty-nine percent of the city, and it now has no African American-owned bank of any kind, a fact HBCU Money’s own reporting names directly. Together, Ohio and Wisconsin’s losses erased nearly $130 million in Black-owned banking assets in a single year, offset only partly by the addition of Redemption Bank in Salt Lake City, Utah; a welcome new entrant, but one whose presence in a state with a comparatively small Black population does nothing for the students at Central State and Wilberforce or the residents of Milwaukee’s north side. Missouri, notably, does not belong in this category at all while it has no Black-owned bank, but it is one of only four states, alongside Maryland, Mississippi, and Virginia, that together hold roughly eighty percent of all African American-owned credit union assets nationally, with St. Louis Community Credit Union anchoring real capacity in the state even without a bank of its own.

This is the pattern the institutional lens is built to catch and the individual-success lens is built to miss. It is not that Black home buyers in Houston, Harlem, Philadelphia, Columbia, or Los Angeles lack the income, the credit profiles, or the desire to build wealth through homeownership. It is that the institutional infrastructure to let them do it through an ownership structure aligned with their own community’s capital retention simply does not exist where they live, or exists and does real business there, sometimes real estate business, without that business ever reaching the specific product that would make the ownership meaningful to a family buying a home to live in, or existed until this year and has now been lost outright. The absence is structural, and structural absences do not close through individual effort; they close through institutional construction, merger, and expansion or they do not close at all.

The scale problem compounds the geography problem. HBCU Money’s own 2025 directories count African American-owned banks holding $6.7 billion in assets, and 205 active African American-owned credit unions holding $8.15 billion in assets and serving 726,929 members, a combined $14.85 billion in Black-owned depository capital against nearly $25 trillion in total American bank assets alone. The credit union count has fallen from 318 institutions in 2016 to 205 today, a 35 percent decline in the number of institutions even as combined assets more than doubled over the same period, a sector consolidating around its strongest players while losing breadth, not one expanding into new geography. The bank sector tells the same story in sharper relief: two of its oldest and newest institutions, a century-old Milwaukee thrift and a two-year-old Columbus startup, both vanished from the ranks in the same year. Of this already-thin universe, only a handful of institutions actively originate primary-residence consumer mortgages at any real volume; many of the rest, like Unity National, are real and active lenders in commercial and investment real estate without extending that activity into owner-occupied home loans, while others are simply not underwriting real estate credit as a core product line at all, whether from capital constraints, risk appetite, or the absence of the correspondent relationships and secondary-market infrastructure that make mortgage lending viable at scale for a small institution. HBCU Money’s own Annual Wealth Report puts African American household net worth at roughly $5.6 trillion, a figure that makes plain how thin the institutional base is relative to the capital it would need to absorb if African American mortgage demand were redirected toward it in any serious volume. Nine primary-mortgage lenders drawing on $14.85 billion in combined sector assets cannot underwrite home purchases for a population of over forty million people concentrated in dozens of metropolitan areas outside their combined footprint, particularly against an industry where a single national lender moves more than $100 billion in loans in one year. The mismatch is not a marketing problem to be solved with a “bank Black” campaign. It is a balance-sheet, charter, product-line, and geographic-coverage problem that campaigns cannot fix.

What follows from this is not resignation but a specific set of institutional priorities. First, expansion of primary-mortgage capacity into states where Black-owned depository institutions already operate including in adjacent real estate lending, as Unity National does in Texas but do not lend on owner-occupied homes, should be treated as a nearer-term strategic objective than chartering new institutions from scratch, since the regulatory relationship, the deposit base, the real estate underwriting expertise, and in New York’s and Texas’s cases a double-digit count of existing credit unions already exist; what is missing is a specific product line, which is a narrower and more solvable gap than institutional absence. Second, the roughly two hundred active Black-owned credit unions nationally represent underused latent capacity concentrated too heavily in four states; a coordinated push through NCUA guidance, CDFI Fund support, or philanthropic capital specifically earmarked for mortgage-program buildout to bring a meaningful share of the New York and Texas credit union bases into primary-mortgage origination would multiply national coverage without requiring a single new charter. Third, secondary-market aggregation matters more for this sector than for almost any other segment of American banking: a consortium structure that allows small Black-owned institutions to originate loans locally while pooling them for sale or securitization through a shared, mission-aligned intermediary would let a nine-lender map become a fifty-state map without requiring each institution to carry mortgage risk alone on an undersized balance sheet. Fourth, HBCUs themselves properly understood as one node in the broader African American institutional ecosystem rather than its center sit inside several of the exact metropolitan areas where lending capacity is absent, dormant, commercial-only, or newly lost, and alumni associations, endowment offices, and institutional banking relationships at schools in Texas, South Carolina, Pennsylvania, California, and Ohio could function as anchor depositors and referral partners, giving a Unity National, an Optus Bank, or a New York credit union the local relationship base and deposit volume needed to justify building out a primary-mortgage division that does not currently exist.

Fifth, and perhaps most directly actionable, the sector needs its own version of what Legacy Home Loans already proves is possible: a dedicated, Black-owned nonbank mortgage company, built by an entrepreneur with outside investment capital, licensed to originate across multiple states, and structured from the outset to correspond with rather than compete against the depository institutions already discussed. Legacy demonstrates the model works at scale: twenty-nine states plus Washington, D.C., built without ever taking a deposit or carrying a bank charter. What Legacy does not solve is ownership; profit and control sit with a Black-led company, not a Black-owned one, and the model’s success has not yet been replicated in Black-owned form. A founder pursuing this path would not need to invent underwriting or licensing from scratch — nonbank mortgage companies operate on well-established regulatory rails — but would need enough capital to meet state net-worth and bonding requirements across a meaningful footprint, and enough underwriting and secondary-market discipline to sell originated loans forward rather than hold them on a balance sheet the company does not have. The natural distribution partners for such a company are exactly the institutions already identified in this piece as active in real estate or deposits but not in primary mortgages: Unity National Bank in Houston, whose existing commercial real estate lending relationships and third-party mortgage referral arrangement could be absorbed directly into a Black-owned originator rather than an outside partner; United Bank of Philadelphia; Optus Bank in Columbia; OneUnited’s branch network in California; and the credit union bases in New York and Texas. None of them would need to build a primary-mortgage division of their own if a Black-owned originator existed to take the referral, close the loan under a shared or co-branded relationship, and let the deposit-taking institution keep the account and the trust while the mortgage company carries the origination expertise and risk. That structure — bank or credit union as the front door, a dedicated Black-owned originator as the engine behind it — would close more of the map faster than waiting for seventeen banks and two hundred credit unions to each build mortgage capacity independently, and it is the one recommendation on this list that does not depend on an existing institution changing its strategy first; it only requires someone to build it.

None of this requires new instruments that do not yet exist. It requires existing Black-owned banks and credit unions to treat mortgage buildout and geographic expansion as core strategy rather than incidental growth, it requires an entrepreneur and investment capital willing to build the origination company that connects them, and it requires the broader institutional ecosystem such as HBCUs, Black chambers of commerce, Black professional networks to function as coordinated infrastructure for that expansion rather than as separate, isolated actors each solving a piece of the same problem independently. The map of nine dots is not a permanent feature of the landscape. It is the current state of an institutional sector that lost two of its members in a single year, has not gained a stable new charter in over two decades, has shed a third of its credit unions since 2016, and has not yet been asked, systematically, to turn the capital and the real estate expertise it already has into mortgages for the families it was built to serve. Reversing it is a matter of capital, coordination, and institutional will not of finding more good customers, who have never been the scarce resource in this equation.

Disclaimer: This article was assisted by ClaudeAI.
Building Dynasties: What It Will Take for African American Families to Rise to Power

“control, control of resources, control of self, control of nation, requires preparation — Garveyism was about total preparation.” – Dr. John Henrik Clarke, writing on Marcus Garvey’s philosophy of Black institutional power

In 1952, a mason in Americus, Georgia bought eleven acres with cash he’d saved from three decades of laying brick. He built a house on it, a smokehouse behind it, and a wraparound porch where he told his grandchildren that the land was the family’s now, forever. He died in 1979. By 1994, the eleven acres had been split six ways, sold in fragments to cover a funeral, a divorce, and two bad business loans. Today a subdivision sits where the smokehouse stood. The mason did everything right by the logic he was given: work, save, buy, own. What he lacked was not virtue. It was infrastructure. Nobody had ever taught him that land without governance is just land waiting to be divided.

That story is not an outlier. It is the median outcome. And it is the central argument of this piece: African America’s problem was never a shortage of individual achievement. It is a near-total absence of the legal, financial, and cultural machinery that converts one generation’s success into the next generation’s platform. Until that machinery is built, deliberately and aggressively, every dollar earned by this community will keep dying with the person who earned it.

Start with the scoreboard, because the scoreboard is brutal. The Federal Reserve’s 2022 Survey of Consumer Finances put median Black household net worth at $44,900, against $285,000 for the median White household — a gap of more than six to one, and one that widened in absolute dollar terms even as Black wealth grew faster in percentage terms during the pandemic recovery. Growth rate is a vanity metric when the base is this small. A 60 percent increase on $28,000 is still poverty with better arithmetic. The gap is not closing. It is compounding, in the same way interest compounds, except in the wrong direction.

Now layer on top of that the single largest wealth movement in American history, already underway. Cerulli Associates projects that $84 trillion will pass from the Baby Boomer and Silent Generations to heirs and charities through 2045, the bulk of it concentrated among households that were already high-net-worth. This is not a rising tide. It is an inheritance economy, and inheritance economies reward whoever already has family structures in place to receive, consolidate, and reinvest capital across generations. Families without that structure will watch the transfer happen around them, not to them. The transfer is not going to wait for African America to get its paperwork in order.

This is where the sentimental version of “generational wealth” needs to be retired. Passing down money is not the same as passing down power, and Black America has been sold the former as if it were the latter. Power, as any serious student of the Waltons, the Rockefellers, or the Kochs understands, does not come from an inheritance check. It comes from the entity that controls the check. The Walton family does not merely benefit from Walmart’s success; through Walton Enterprises LLC and the Walton Family Holdings Trust, they collectively control roughly 45 percent of the company’s outstanding shares, a concentrated bloc large enough to determine board composition, executive succession, and long-term strategy three generations after Sam Walton’s death. That is not inheritance. That is institutionalized command, engineered through trust structures, family governance, and a refusal to let ownership fragment. Jay-Z’s net worth impresses a magazine cover. It does nothing for the fortieth Black family down the street, because it is not organized as an institution — it is one man’s balance sheet, subject to one man’s mortality.

The uncomfortable truth is that most families, of any race, fail at this. Research tracked by the Family Business Institute finds that roughly 30 percent of family-owned businesses survive into a second generation, about 12 percent make it to a third, and only 3 percent endure into a fourth. Succession is hard even with capital, even with lawyers, even with three generations of practice at running something. What that data point exposes is not that Black families are uniquely undisciplined — it’s that family continuity is a discipline nobody is taught, and African America has had roughly one-fifth of the time (counting from Emancipation, and accounting for the systematic destruction of Black wealth through redlining, urban renewal, and outright terrorism such as the 1921 razing of Tulsa’s Greenwood district) to build the muscle memory that older American dynasties built over five and six generations. The response to that deficit cannot be more individual grit. It has to be structure, copied deliberately from where it already works, and adapted ruthlessly to this community’s actual starting conditions.

So build the structure. A family constitution — a written document specifying mission, capital rules, and succession mechanics — costs nothing but discipline and an afternoon with a competent estate attorney, yet almost no Black family has one, while every dynasty mentioned above treats theirs as more binding than a corporate bylaw. A family office does not require billionaire assets to justify its existence; pooled family capital in the low six figures is sufficient to retain a fee-only advisor, establish an LLC or trust structure, and begin making coordinated decisions across a real portfolio — brokerage accounts, retirement vehicles, business equity, insurance-funded trusts, even royalty and intellectual-property streams — instead of six relatives each managing a fragment of the same family’s capital in isolation. Land is one asset class among several and should be governed the same way the rest are: never liquidated to cover an emergency when it could instead be collateralized, folded into a trust, or held alongside an equity stake in a family business and a diversified investment account, each professionally managed rather than administered by whichever relative answered the phone first.

None of these families stayed inside their founding asset. Koch Industries began as a part-interest in a single Minnesota oil refinery bought out in the 1940s and 1960s; under Charles Koch it diversified deliberately into pipelines, fertilizer, pulp and paper, ranching, glass, electronics, and commodities trading, so that no single market downturn — a refining glut, a paper-price collapse, a bad cattle season — could touch the whole estate at once. The Rothschilds began as court bankers to European nobility in the 1760s and, over two centuries, moved family capital into railways, mining, real estate, energy, and, notably, wine estates like Château Lafite and Château Mouton — acquired not as hobbies but as productive, appreciating assets that diversified the family’s holdings away from the banking sector that made them. Even the Waltons, whose fortune is most associated with a single company, don’t hold it as a single asset: Walton Enterprises runs its own internal investment arm allocating family capital into private equity, real estate, and outside ventures entirely apart from Walmart stock, precisely so the family’s fate isn’t fused to one retailer’s stock price. In every case, the founding asset became the seed capital for a portfolio, not the permanent shape of the estate. That is the model the eleven acres in Americus should be measured against. The land was never meant to be the ceiling of that family’s wealth — it was meant to be collateral for the next asset, security for a loan into a business, a hedge alongside a brokerage account, one holding in a portfolio instead of the whole of it. Held that way, structured that way, it doesn’t matter whether the estate a family passes down began as land, a barbershop, a nursing license, or a pension. What matters is whether it was ever allowed to grow past its origin.

None of this is exotic. It is standard operating procedure for every dynasty this essay has named. It has simply never been marketed to African America as something within reach, because the wealth management industry profits more from selling individual products than from building family institutions that don’t need it.

Institutions of the wider Black ecosystem have a direct, self-interested role here, and this is where the case must be made in dollars, not sentiment. A Black-owned bank or credit union that captures family trust deposits and estate accounts gains stable, patient capital instead of transactional balances. A historically Black college or university that structures a real endowed-chair or scholarship-naming relationship with a family — rather than accepting a one-time gift — gains a recurring donor relationship spanning generations rather than a single tax-season transaction. Fisk, Tougaloo, Dillard, and Xavier of Louisiana have decades of experience cultivating exactly this kind of multigenerational donor family; Alcorn State, Coppin State, Savannah State, Bethune-Cookman, Norfolk State, Delaware State, Fort Valley State, and Morgan State could each become the anchor institution for a rising family dynasty if they pursued the relationship as deliberately as the Rockefellers pursued the University of Chicago or the Dukes pursued the university that bears their name. The institution that captures a family early, before its capital scales, is the institution that owns the relationship when that capital multiplies. This is not charity. It is customer acquisition, and any HBCU treating it otherwise is leaving its own endowment on the table.

The same logic extends past the water’s edge. Diaspora capital coordination — joint investment vehicles linking African American family offices with counterparts in the Caribbean and across Africa Core — is not a symbolic gesture toward Pan-Africanism. It is a hedge against the concentration risk of building wealth inside a single, historically hostile domestic market. A family real estate or infrastructure fund co-managed across African American, Jamaican, and Ghanaian family offices diversifies political risk, currency exposure, and asset class in one structure, while building exactly the kind of institutional density and strategic coordination that isolated, single-country family wealth can never achieve alone.

None of this happens through moral appeal, and this publication has no interest in making one. Appeals to racial solidarity have moved conferences and Twitter timelines; they have not moved balance sheets. The case for family institutionalization has to be made the way the Waltons, the Kochs, and the Wallenbergs made it to their own descendants: this structure protects what you have from your own children’s mistakes, from probate courts, from market volatility, and from the actuarial certainty that someone in every family eventually dies without a plan. Estate planning is not morbid. It is the single highest-leverage act of institution-building available to a family with under a million dollars in assets, and it costs less than a used car.

There is also a governance failure hiding inside the sentimental version of Black wealth-building that deserves direct confrontation. Families that treat wealth distribution as an equality exercise — splitting everything evenly among heirs regardless of role, competence, or commitment — are optimizing for fairness at the expense of survival. The Family Business Institute’s own data on why family enterprises collapse points overwhelmingly to succession disputes and undefined governance, not lack of capital. A family that assigns real roles — someone accountable for investment decisions, someone accountable for philanthropic strategy, someone accountable for legal and tax exposure — and backs those roles with actual authority, not just a title at Thanksgiving, will outlast a family that insists every cousin gets an equal, undifferentiated vote on every decision. Institutions require hierarchy. Families building institutions will have to get comfortable with that, however uncomfortable it sits against a cultural instinct toward flattened, communal decision-making.

The alternative to all of this is not neutral. It is continued erosion. Every family that fails to formalize governance sends its capital back into the undifferentiated churn of individual consumption — the paycheck model this publication has criticized elsewhere, in which wealth is treated as something to be spent rather than something to be commanded. Every dollar that leaves the Black institutional ecosystem through an unplanned estate, an uninsured death, or a liquidated piece of land is a dollar the next generation has to earn from zero, while families with institutional infrastructure simply compound what they already hold. The compounding gap in the Federal Reserve’s data is not an accident of history. It is the visible output of one set of families running institutional software and another set running none at all.

The mason in Americus did not fail his family. He succeeded at everything available to him in 1952, in a state where a Black man building wealth at all was itself an act of defiance. What failed him was the absence of a structure that could have held what he built past his own lifetime, and the absence of a plan to let that first asset become seed capital for a second and third — a trust, a governance document, a designated successor with both the authority and the training to keep the estate whole and growing, whatever form that estate took or became. That absence is fixable, at a scale of millions of families, in this generation, and it applies as much to a brokerage account or a stake in a family business as it does to eleven acres of Georgia clay. The Kochs turned one refinery into a dozen industries. The Rothschilds turned a banking desk into vineyards and mines. Neither family mistook where they started for where they had to stay. It requires no act of Congress and no act of philanthropy from outside the community. It requires families to stop organizing themselves as clusters of individuals bound by affection, and start organizing as institutions bound by structure, because affection does not survive probate court and structure does. The eleven acres are gone. Whatever the next generation holds — land, equity, a business, a portfolio, or something none of them have thought to build yet — does not have to stop there, and does not have to follow them into the ground.

Disclaimer: This article was assisted by ClaudeAI.