My stake in Roc Nation should go to you. Leave a piece for your siblings too. — JAY-Z
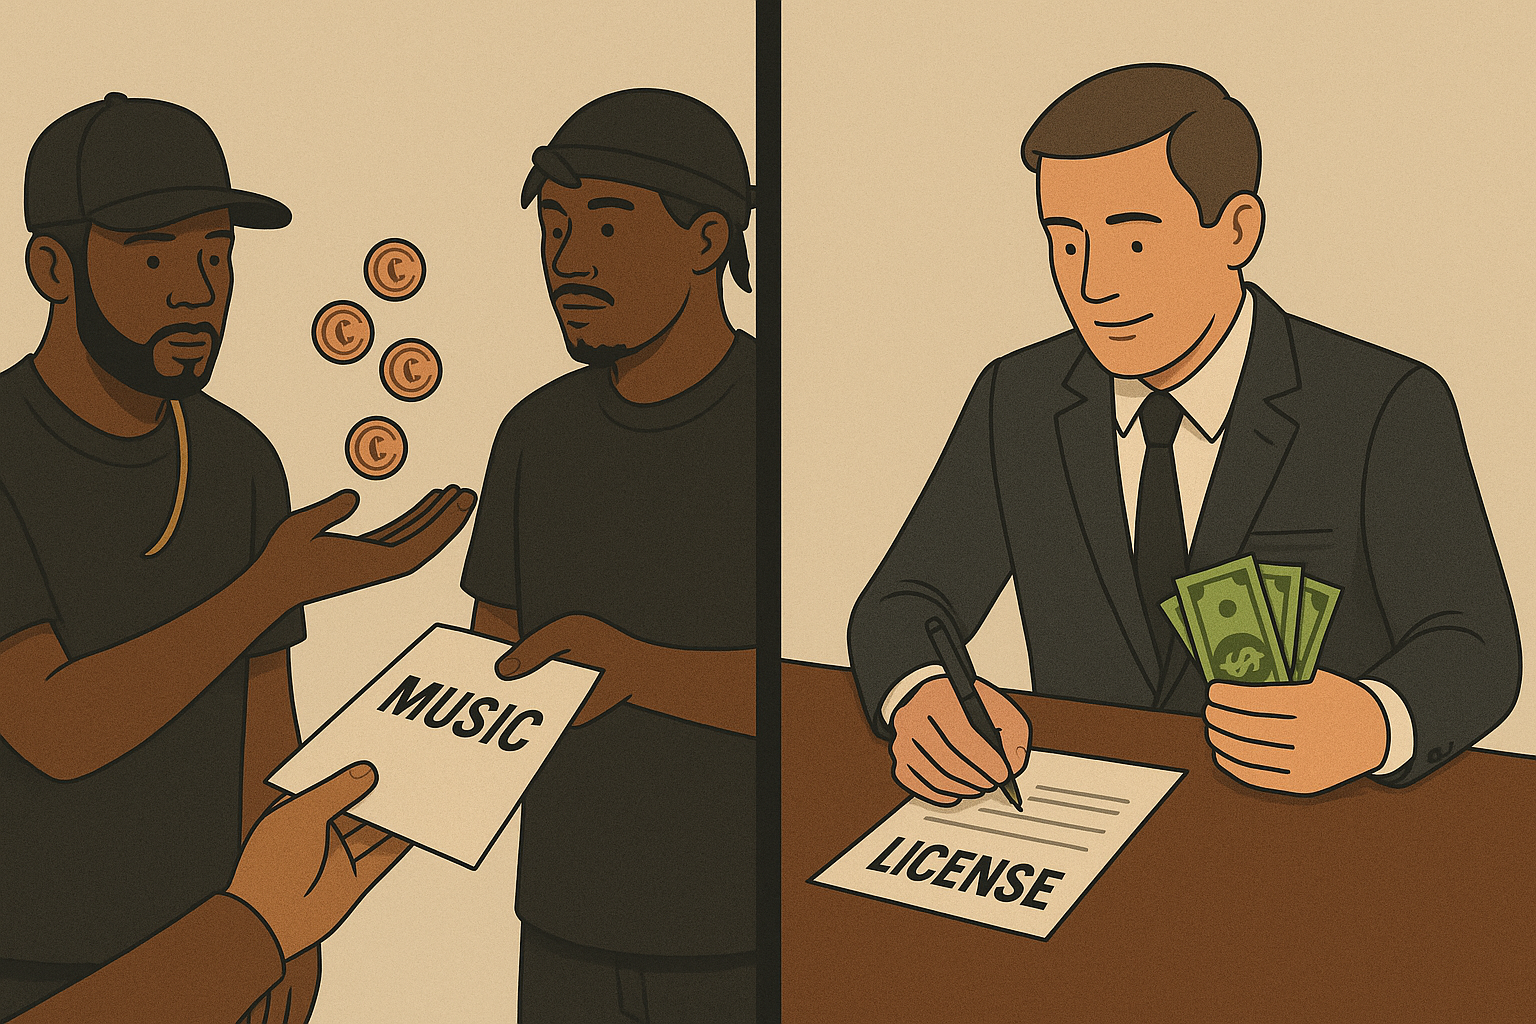
Hip-hop created one of the largest and most influential waves of cultural production in modern history, a global ecosystem now valued in the tens of billions of dollars, rooted entirely in African American creativity. Yet as this asset class matured into one of the more reliable yield-generating instruments in entertainment finance, African America missed the allocator’s window. Rather than building an institutional buyer capable of acquiring, warehousing, and compounding the value of these catalogs at scale, the assets were sold piecemeal into a marketplace of external capital, and the long-duration cash flows that should have anchored African American balance sheets now sit instead on the books of firms with no obligation to the community that produced them.
This is not a critique of individual artists. Each seller acted rationally given the liquidity available, the risk they were carrying, and the absence of any institutional counterparty built for them. The failure sits one level up, at the level of capital formation. Over the past decade, catalog transactions involving Future, Lil Wayne, Nelly, Metro Boomin, Dr. Dre, and the estates of The Notorious B.I.G. and Juice WRLD confirmed what allocators across the industry already suspected: music IP behaves like an uncorrelated, inflation-resistant annuity, and hip-hop catalogs in particular carry decades of runway as the genre’s first generation of superstars ages into legacy status. Wall Street underwrote that thesis aggressively, and it did so through familiar channels; publishing majors, sovereign wealth-backed royalty funds, and private equity vehicles purpose-built to acquire exactly this kind of asset. African American institutional capital was not at the table to underwrite it at all, not because the thesis was unclear, but because no vehicle existed on our side capable of acting on it.
What was missing was not talent, timing, or demand. It was a dedicated acquisition vehicle, an African American-controlled counterpart to the publishing majors and the private-equity-backed royalty funds that have spent the last five years bidding up catalog multiples. Had that vehicle existed, artists negotiating an exit would have had a buyer that kept the rights, the governance, and the recurring royalty stream inside the community’s own institutional perimeter, rather than a forced choice between liquidity and control. The absence of that buyer meant the negotiation itself was structurally lopsided: artists sold to counterparties who understood the asset’s long-term value precisely because they had modeled it for years, while the community whose creative output generated the value had no equivalent underwriting capacity of its own.
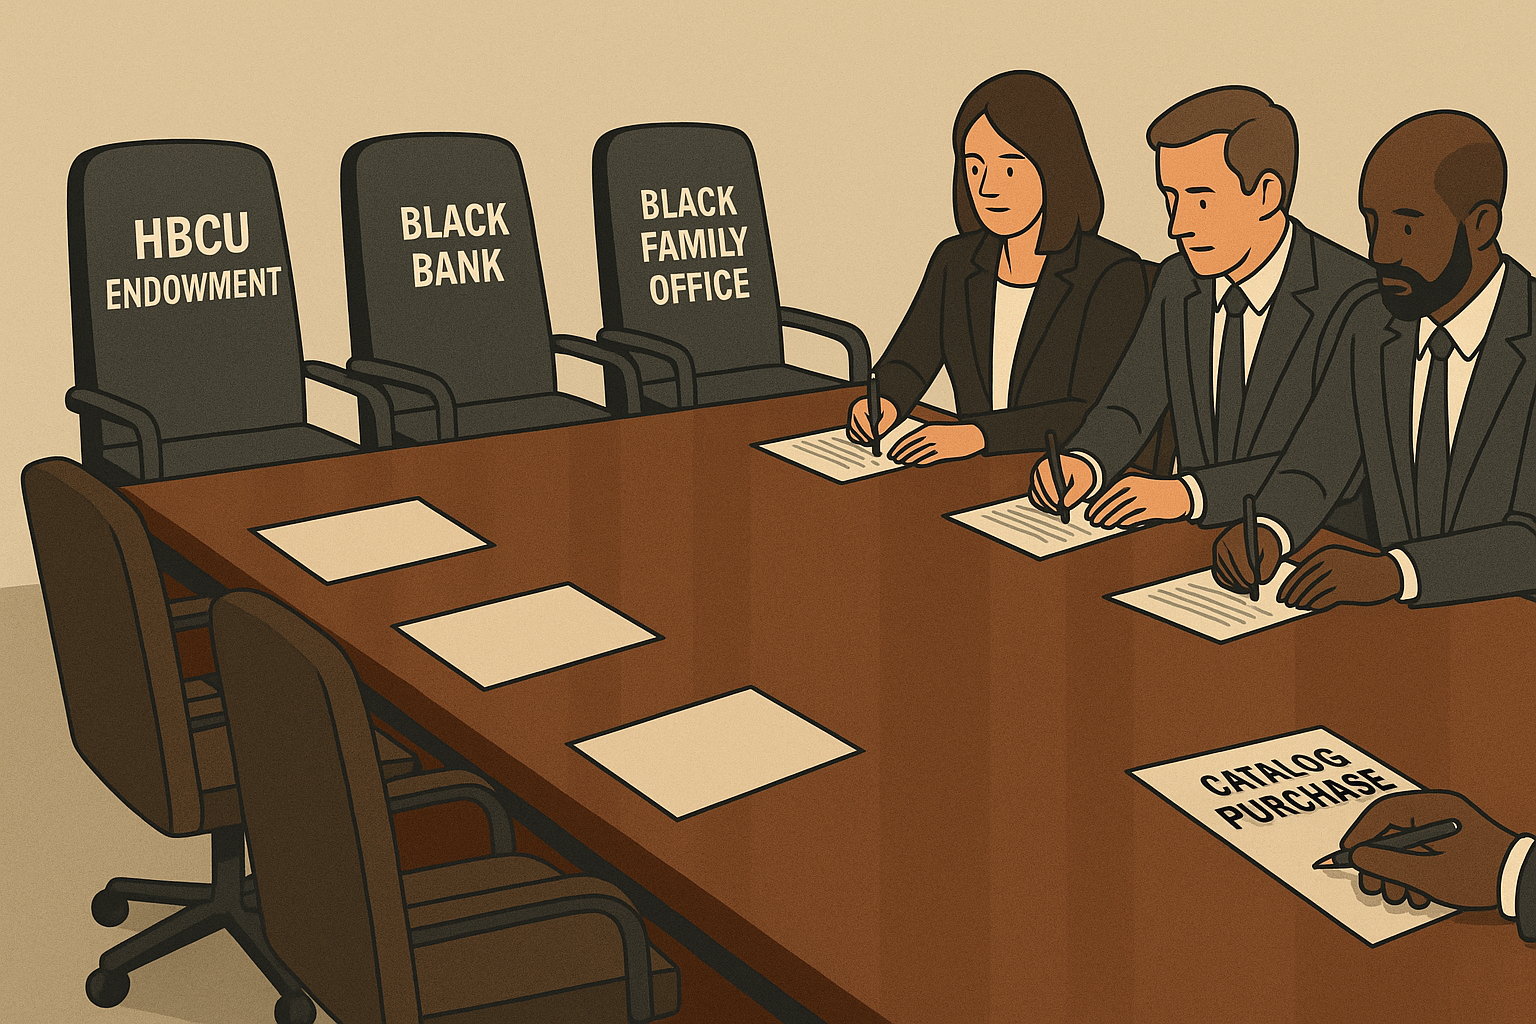
Modeled correctly, the vehicle looks less like a philanthropic gesture and more like a standard alternative-asset fund structure: a seeded acquisition platform, anchored by a small number of large limited partners — HBCU endowments, African American-owned banks and credit unions, pension allocators, and family offices — committing capital in the $150–200 million range at formation, with a mandate to acquire catalogs directly and co-invest alongside artists willing to trade full monetization for partial equity and long-term governance rights. Structured as a permanent-capital vehicle rather than a closed-end fund with a forced exit, it could compound royalty income across cycles the way infrastructure and timberland funds do, instead of racing toward a liquidity event. Every acquisition would function less like a purchase and more like a reinvestment: royalties recycled into scholarships, research fellowships, and follow-on acquisitions, building an internal rate of return measured not only in dollars but in institutional density. A second-tier warehouse facility, syndicated among African American banks and credit unions, could have financed acquisitions between capital calls, the same short-duration lending structure regional banks routinely provide to specialty finance funds elsewhere, just never extended to a Black-owned entity in this asset class.
Had this vehicle been seeded fifteen or twenty years ago, HBCU endowments that anchored the fund would today be collecting recurring royalty income and equity appreciation tied to some of the most consumed music on Earth — music their own institutions helped make possible by training generations of the artists, producers, engineers, and executives who built the genre. That is precisely the kind of long-duration, intergenerational asset endowments are built to hold, and it is exactly the kind of asset African American endowments still do not. It would also have solved a problem HBCU endowment officers raise consistently in private: a shortage of proprietary deal flow uncorrelated to the equities and fixed income already crowding most endowment portfolios.
The math on deployment is not speculative. Catalog multiples across the sector have traded in a range that makes even modest-scale entry accretive within a few years of steady licensing and streaming revenue, before accounting for the additional upside AI-driven licensing markets are expected to unlock. A firm seeded a decade or two ago, compounding acquisitions and reinvested royalties at that pace, would plausibly be a multi-billion-dollar institution today — very likely the largest African American-owned investment company in the country — and one whose asset base would not be office towers or equities correlated with the broader market, but irreplaceable, decades-durable intellectual property. Even a partial version of this thesis, consolidating a fraction of the past decade’s catalog sales under one African American-controlled holding structure, would today represent a multi-billion-dollar balance sheet generating tens of millions in annual cash flow — capital that could seed STEM endowments, venture funds, homeownership programs, land trusts, and fellowship pipelines rather than flow to shareholders with no stake in African America’s socioeconomic future. That is a materially different institutional posture than the one African America occupies today, where capital campaigns are run reactively, dollar by dollar, rather than compounding passively off an owned asset base.
That asset-class discipline matters on its own terms. Music IP is one of the few alternative categories where cash flows are largely insulated from the business cycle — people keep streaming during recessions — while also carrying genuine appreciation potential as catalogs age into classic status and licensing surface area expands across film, television, advertising, gaming, and international streaming markets. For allocators used to real estate cycles and public equity volatility, a hip-hop catalog fund would have offered something rare: uncorrelated, long-duration, culturally proprietary yield. And unlike most alternative asset classes African American institutions are chasing as new entrants — private equity, venture, and commercial real estate, where the community is competing on someone else’s terms and someone else’s decades of accumulated deal experience — this is one where the community is not catching up to someone else’s supply chain. It is the supply chain, and the only asset class where African America’s comparative advantage is not aspirational but already realized in the underlying creative output itself.
The opportunity cost compounds beyond the balance sheet. A consolidated catalog platform would have anchored career pipelines HBCU graduates are largely locked out of today — catalog valuation, music-rights law, licensing and sync placement, royalty accounting, AI-audio and data engineering, and global rights management. Those are high-margin, high-skill roles that now exist almost entirely inside firms African America does not own. Hundreds of positions that could have been anchored within a Black-controlled firm instead sit inside companies with no connection to the community whose creative output built the underlying asset. Ownership, not employment, is the relevant comparison here. A generation of African American executives has been well compensated running divisions of catalogs they hold no equity in; the transformative wealth event was always upstream, in the ownership stake, not the salary. The distinction matters because well-paid labor, however senior the title, does not compound the way ownership does — a lesson the ownership class has always understood and the professional class is still catching up to.
Governance follows capital, and that is where the deeper cost sits. Whoever holds the catalog decides which brand campaigns get licensed, which political messaging gets amplified or denied, and how an artist’s estate is administered after death. A board seated with artists, HBCU representatives, and African American family offices would not need to romanticize the music to protect it; it would simply have the standing to make licensing and estate decisions in the community’s interest, the same way any controlling shareholder does elsewhere. When ownership sits outside the community, that discretion sits outside it too — and African America’s most consumed cultural export continues generating returns for balance sheets with no stake in the institutions that produced it, no obligation to reinvest in the schools that trained its creators, and no reason to weigh cultural stewardship against quarterly licensing revenue.
The central lesson is structural, not moral. Artists cannot build institutions alone, and institutions have to exist before artists need them, not after. Without a buyer built for this purpose, artists sold into the only marketplace available — and did so rationally. The absence of an African American-controlled acquisition vehicle is an institutional-capital failure, not an individual one, and it is the same failure pattern that shows up whenever African America produces enormous cultural or economic value without first building the entity designed to capture and compound it. Other communities have not been shy about doing exactly this in adjacent industries — building dedicated acquisition vehicles ahead of a wave rather than reacting to it after the fact. The absence of a comparable African American vehicle in music is not for lack of a workable template; the template already exists elsewhere.
The window has not fully closed. A second wave of catalog monetization is forming as AI licensing markets mature and as hip-hop’s global consumer base expands across Africa, South Asia, and Latin America. A vehicle built now — structured with a multi-class equity model that lets artists contribute catalog for ownership shares, anchored by HBCU endowments and African American financial institutions, governed by a board that includes artists and HBCU leadership, and staffed with dedicated valuation, estate-protection, and licensing divisions — would not be building something unprecedented. The publishing majors and royalty-focused funds now competing for this paper have already proven the model works. The only open question is whether African American institutional capital enters this cycle as a buyer, or watches a second generation of catalogs leave the community the way the first one did.
Disclaimer: This article was assisted by ClaudeAI.