Tag Archives: Black business growth

Capital Without Corridors: Why African America and Black Britain Need Shared Institutional Infrastructure

“Economic power is the last frontier of freedom. Until we control our commerce, we will never fully control our destiny.” — Marcus Garvey
In 1900, a group of Alabama farmers pooled cotton receipts to charter a bank that no single one of them could have opened alone. None held more than a few hundred dollars. Together, they held a institution. Three thousand miles away, in the port city of Cardiff, West African and Caribbean seamen who had settled after the world wars were doing something structurally similar without knowing it: forming burial societies, credit pools, and mutual aid clubs that functioned as proto-banks in a country that would not lend to them. Neither group called what they were building an “institution.” They called it survival. A century later, the descendants of both efforts are still solving the same problem in isolation from each other; separated by an ocean, a currency, and a regulatory system, but bound by an identical structural deficit: African-descended capital that has no dedicated channel through which to find African-descended enterprise.

In a world increasingly defined by interconnected markets, fractured democracies, and rising demands for racial equity in capital allocation, a new kind of institutional infrastructure is quietly gathering momentum: a transatlantic Chamber of Commerce dedicated exclusively to African American and African British businesses. From Atlanta to Birmingham, from Washington to Wolverhampton, Black entrepreneurs face parallel challenges and untapped opportunities. Creating a formalized economic corridor between these two post-imperial spheres could serve as a powerful mechanism to leverage common history, shared struggles, and mutual aspirations.

The thesis is straightforward and, for an institutionally minded reader, uncomfortable: African America and Black Britain have spent a century building parallel, disconnected, and chronically undercapitalized business ecosystems when the more rational architecture, the one every other diaspora with meaningful economic power has eventually built, is a coordinated one. A formal, dual-headquartered Chamber of Commerce linking African American and Black British enterprise, with structured extensions into Africa Core and the Caribbean, is not a symbolic gesture. It is an overdue piece of institutional infrastructure, and its absence has a measurable cost.

Start with the scale of the deficit on each side of the Atlantic. In the United States, Census Bureau data released in November 2025 puts Black or African American-owned firms at 3.4 percent of all employer businesses, generating $249.0 billion in receipts, a share roughly a quarter of what proportional representation would require, given that Black Americans make up about 14 percent of the population. That 3.4 percent is not stagnant; it reflects real growth. Pew Research’s analysis of the same Annual Business Survey data found that the number of majority Black-owned employer firms rose from 124,004 in 2017 to 194,585 in 2022, with gross revenue climbing 66 percent over that span, from $127.9 billion to $211.8 billion. The trend line is genuinely upward. The base it is climbing from, however, remains a small fraction of the American business landscape, and growth in firm count has not been matched by growth in access to the capital markets that convert a firm into an institution.

That capital gap is where the American and British stories converge most precisely. Black-founded startups in the United States received an estimated 0.4 percent of all U.S. venture funding in 2024, down from a 2021 peak of 1.3 percent, according to Crunchbase data. By 2025 the figure had fallen further, with Black-founded companies capturing roughly $942 million, or about 0.32 percent, of total U.S. venture investment, even as overall startup funding ticked upward. In the United Kingdom, the trajectory is nearly identical in shape. Extend Ventures’ decade-long study found that between 2009 and 2019, Black entrepreneurs received just 0.24 percent of British venture capital, spread across only 38 businesses. The post-2020 racial-reckoning period produced a temporary correction, Black British founders’ share of venture capital rose to a high of roughly 1.1 percent in 2021, but by 2023 it had drifted back down toward the historical baseline, settling under one percent. Two economies, two regulatory systems, two currencies, and functionally the same outcome: capital markets that treat Black entrepreneurship as a rounding error rather than a segment.

This is not, William A. Foster IV’s editorial framework would insist, a story about individual founders failing to pitch well enough, or about isolated instances of bias that better networking could resolve. It is a story about the absence of dedicated institutional plumbing. Every diaspora that has meaningfully closed a capital gap has done so through coordinated infrastructure rather than dispersed individual effort; trade associations that aggregate demand, chambers that formalize relationships with governments and lenders, and capital vehicles that are patient enough to survive a single bad funding cycle. African America and Black Britain have built pieces of this infrastructure independently and, until now, never linked them.

The existing landscape illustrates both the appetite for such coordination and its current fragmentation. In the United States, the U.S. Black Chambers network now spans more than 145 chambers of commerce and business organizations across 42 states, representing approximately 326,000 Black businesses. The National Black Chamber of Commerce has scaled internationally, describing itself as operating across 50 nations with more than 200 chambers and 150,000 member businesses, and has begun structuring investor-ready projects that connect diaspora business networks to sovereign development plans. These are meaningful institutions. But their scope, by design or by history, remains largely national or loosely federated rather than architected as a single transatlantic capital corridor with dedicated underwriting capacity, shared data infrastructure, and formal standing with both the U.S. Small Business Administration and the British Business Bank simultaneously. No existing body treats African American and Black British commerce as two nodes on a single circuit that also runs through Accra, Kingston, and Lagos.

The British Business Bank’s own research underscores why formal capital-market coordination, rather than networking events, is the correct unit of intervention. Its most recent smaller-business finance survey found that business owners from Black, Asian, or other ethnic-minority backgrounds are considerably more willing to use external finance than their white counterparts; 45 percent versus 31 percent — yet a majority of Black entrepreneurs, 59 percent, say it would be difficult for them to access external finance at all. This is not a demand-side problem. It is a supply-side and structural one: willingness to borrow and grow exceeds the system’s willingness to lend, and no institution on either side of the Atlantic currently exists whose sole mandate is closing that specific gap for this specific population, at scale, on commercial terms.

A transatlantic Chamber addresses this gap through five interlocking functions rather than one. First, a capital fund seeded by community-owned financial institutions, diaspora-led family offices, and university endowments rather than by philanthropy alone providing both debt and equity on terms that do not require founders to first exhaust personal and family savings, the financing method that a large share of Black founders on both sides of the Atlantic currently rely on by default. Second, coordinated policy and procurement advocacy, pressing simultaneously on U.S. supplier-diversity enforcement and on the U.K.’s post-Brexit search for new trade partnerships, rather than lobbying each government in isolation. Third, structured bilateral trade facilitation, lowering the transaction cost for a Detroit manufacturer seeking distribution in Birmingham or a London fintech seeking U.S. regulatory counsel. Fourth, technical and executive education built through partnerships with business schools inside the historically Black institutional ecosystem; Hampton University’s School of Business, North Carolina A&T’s College of Business and Economics, and Norfolk State University’s business programs each already train the kind of operational and financial talent a chamber of this scale would need to staff its capital-deployment and underwriting functions, and each represents exactly the kind of talent-concentration opportunity that strengthens an ecosystem rather than scattering its best-prepared graduates into unrelated industries. Fifth, a shared media and visibility function, ensuring that capital allocators on both continents actually see the businesses this infrastructure is meant to serve, rather than relying on each fund manager’s personal network to surface deal flow.

The extension into Africa Core and the Caribbean is not a rhetorical flourish; it is the mechanism by which the Chamber avoids becoming merely a larger version of the national bodies that already exist. A Ghanaian textile exporter gains a retail partner network in the United States. A Jamaican agribusiness founder accesses diaspora investment capital through a London-based office rather than relying solely on remittance flows. A Lagos-based fintech gains regulatory counsel for U.S. market entry without having to build that relationship from zero. Diaspora capital; currently fragmented across remittance corridors, individual angel checks, and disconnected family offices gains a structured channel that treats cultural affinity as a genuine capital-allocation advantage rather than a sentiment to be invoked at conferences and then set aside.

Institutional design questions deserve the same rigor. The Chamber would require dual legal structures from inception: a 501(c)(6) trade association in the United States, paired with a registered company or charitable incorporated organisation in the U.K., with a governance structure that gives neither headquarters — Atlanta or Washington on one side, London or Birmingham on the other — permanent seniority over the other. Founding capital would come from anchor institutions with existing balance-sheet capacity: community-owned financial institutions and credit unions already serving these populations, university endowments with mandates for economic-development investment, and corporate members whose supplier-diversity commitments currently lack a scaled vehicle to deploy against. Membership tiers; micro-enterprise, SME, and strategic partner would each carry distinct services, from a shared digital procurement and analytics portal at the lowest tier to co-investment rights at the highest, ensuring the institution serves capital formation at every stage of a firm’s life rather than only its earliest or latest.

Two structural risks deserve explicit acknowledgment rather than the kind of hedging that weakens an institutional argument before it is made. The first is mission drift: chambers of commerce, across both American and British history, have a well-documented tendency to devolve into event-hosting and networking bodies once their founding capital is spent, precisely because measurable outcomes are harder to sustain than ribbon-cuttings. The corrective is structural, not aspirational tying the Chamber’s continued funding and leadership mandates directly to published, audited metrics: capital deployed, procurement contracts won, jobs created, and follow-on funding raised by member firms, reported with the same rigor HBCU Money applies to its own Annual Wealth Report. The second risk is fragmentation by geography or ideology, splintering Black entrepreneurship advocacy into competing regional bodies that dilute rather than concentrate institutional density. The corrective here is deliberate: the Chamber should explicitly position itself as connective tissue linking the U.S. Black Chambers network, the National Black Chamber of Commerce’s international infrastructure, and their British and African counterparts, rather than as a rival institution competing with them for the same donor and member base.

The politics of building this require independence as a precondition, not an afterthought. In Washington, alignment with the Congressional Black Caucus and the Small Business Administration offers legitimacy and access to existing procurement-diversity mandates. In London, a government still searching for a coherent post-Brexit trade narrative has practical incentive to support a commerce initiative that deepens U.K.–Africa trade linkages without new fiscal exposure. Neither relationship should come at the cost of the Chamber’s ability to critique either government’s enforcement failures, since an institution whose legitimacy depends on political patronage in either capital is an institution built on the same instability it is meant to correct.

What is being proposed, ultimately, is not a networking body but a piece of financial infrastructure closer in function to a development bank with a trade-advocacy arm than to a conventional chamber of commerce. The data on both sides of the Atlantic point to the same conclusion: African-descended entrepreneurship is not undersupplied in ambition, formation rate, or willingness to borrow. It is undersupplied in dedicated capital infrastructure built at the scale its population and growth trajectory actually warrant. Two nations, two currencies, and one underlying deficit make the case for one coordinated institution rather than two isolated ones. The alternative — continuing to build parallel, undercapitalized ecosystems that never formally connect — is not neutral. It is a continued transfer of talent, capital, and institutional capacity away from the very communities generating them, which is precisely the kind of leakage that a coordinated architecture, however difficult to build, is designed to stop.

Disclaimer: This article was assisted by ClaudeAI.
Minding Whose Store: African America Businesses Generate Just 0.43% of U.S. Revenue

Large numbers without context can be misleading to our economic reality and how institutionally poor we are. – William A. Foster, IV

If you are minding someone else’s store, then who is minding yours? Or maybe you focusing on what someone else is doing has not even allowed you to focus long enough to open your own store. These were my thoughts in 2014 when the Huffington Post decided to let the world know that the New York Times has no African American writers in their culture section. I had to take a deep breath knowing that many African Americans would chase this story and scream bloody murder and cries for fairness and justice. Of course Huffington Post at no point in time addressed the real problem of just why things like this occur, namely the New York Times (nor Huffington Post) has any African American ownership. Ironically, the same African Americans who are screaming bloody murder have probably never picked up the Amsterdam News, a 100 year old plus African American newspaper headquartered in New York that was started with a $10 investment ($356 in 2025 dollars) in 1909.

Let us talk about some numbers that should shake us to our core — not as a source of despair, but as a call to serious, sustained action. According to a February 2025 Brookings Institution report analyzing U.S. Census Bureau data, there are approximately 194,585 Black-owned employer businesses in the United States — firms with at least one employee — which generated a combined $212 billion in revenue in 2022, the most recent year of available data. Those 194,585 employer firms collectively employ approximately 1.2 million people. When non-employer businesses are included, the total number of Black-owned firms rises to approximately 3.6 million. But here is the critical detail buried in that larger number: roughly 96% of all Black-owned businesses are non-employer firms, and the average non-employer small business earns just $47,794 per year. The economic weight of the entire sector, in other words, rests on a relatively narrow base of employer firms. That $212 billion figure sounds substantial until you hold it up against a single data point: Wal-Mart’s annual revenue.

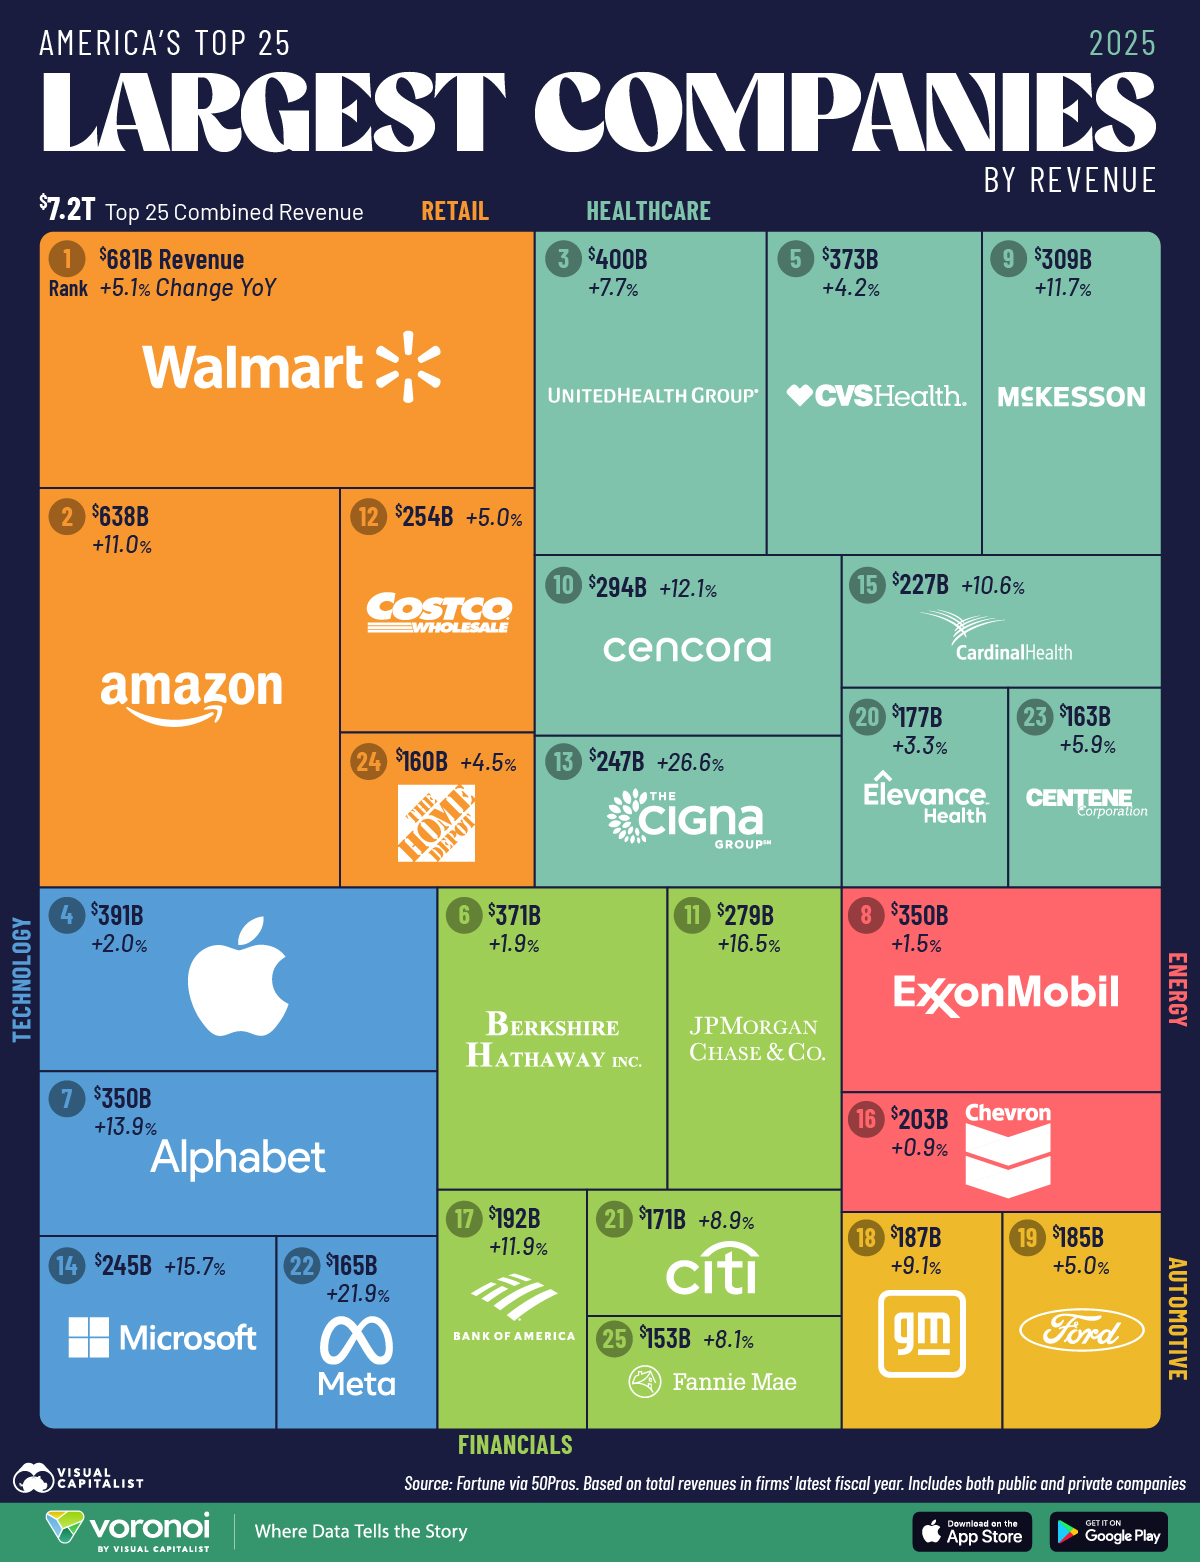
In its most recent fiscal year ending January 31, 2025, Wal-Mart Stores, Inc. reported global revenues of approximately $681 billion. Its U.S. operations alone, the stores that sit in our neighborhoods, that employ our family members at wages that often keep them below the poverty line, that accept our dollars by the billions every single day generated revenues that dwarf the total economic output of every African American-owned employer business in America combined. One company. One corporation founded by one family in Rogers, Arkansas in 1962. That single enterprise generates in annual revenue more than three times what nearly 200,000 Black-owned employer firms produced together.

And Walmart is not alone in that distinction. According to the 2025 Fortune 500, there are 15 individual American companies — each one, by itself — whose annual revenue exceeds the combined $212 billion generated by all Black-owned employer businesses in the United States. Walmart. Amazon. UnitedHealth Group. Apple. CVS Health. Berkshire Hathaway. Alphabet. ExxonMobil. McKesson. Cencora. JPMorgan Chase. Costco. Cigna. Microsoft. Cardinal Health. Fifteen companies. Nearly 200,000 Black-owned businesses. The math is not close.

Now zoom out further. Total revenues across all U.S. businesses in 2022 were $50.9 trillion. Adjusting for estimated growth through 2025, that figure is approximately $58.9 trillion. Black-owned businesses, generating an estimated $251 billion in 2025, represent roughly 0.43% of all U.S. business revenue for a community that makes up 14.4% of the population. That is a representation ratio of 1 to 33. Black Americans are generating business revenue at one thirty-third the rate their population share would suggest. And if Black-owned businesses were generating revenue proportional to their share of the U.S. population, that figure would not be $251 billion — it would be $8.5 trillion. The gap between where Black business stands today and where population parity would place it is approximately $8.2 trillion. That is not a talking point. That is the scoreboard.

Every few years, a video goes viral. A store manager says something racist. A Black customer is followed around a retail floor. Social media explodes. Calls for a boycott trend for 48 hours. And then, quietly and almost universally, people go back to shopping. The outrage dissipates. The dollars continue flowing. This is not an indictment of any individual. The economics of convenience and price are real. Wal-Mart did not become the world’s largest retailer by accident it built a supply chain and a pricing strategy that made it genuinely difficult for lower and middle-income Americans to shop elsewhere. But the conversation about African American spending power, often cited at $1.3 trillion annually, too frequently begins and ends with the individual consumer. Buy Black. Shop Black. Support Black businesses. The moral case is sound. The economic impact, however, is limited so long as it depends entirely on the goodwill and discretion of individual purchasing decisions.

The more instructive question is not whether Black consumers will choose to spend with Black businesses. It is whether Black businesses exist that other communities have no choice but to spend with. Every community that has achieved durable economic power has done so not only through consumer loyalty campaigns but through institution-to-institution capital flows. When a Jewish-owned law firm retains a Jewish-owned accounting firm, when an Asian-owned manufacturer contracts with an Asian-owned logistics company, when a white-owned corporation deposits its cash reserves in a white-owned bank that is not individual charity. That is an ecosystem. Capital circulates. Wealth compounds. Institutions grow. The African American community generates $1.3 trillion in annual spending but has yet to build the institutional infrastructure that would allow a meaningful share of that capital to circulate within the community before it exits. We need Black-owned businesses operating in sectors that other communities must engage — technology, logistics, healthcare, finance, agriculture, defense contracting — not merely retail and personal services. The goal is not to ask anyone to spend with us out of solidarity. The goal is to build enterprises so essential, so deeply woven into supply chains and institutional relationships, that the transaction happens regardless of anyone’s racial sympathies.

But this failure of institutional circulation is not only about what non-Black institutions do with their dollars. It is equally about what Black institutions do with theirs. As HBCU Money has documented, only two HBCUs are believed to bank with Black-owned banks meaning more than 90% of historically Black colleges and universities do not deposit their institutional funds with African American-owned financial institutions. Howard University, African America’s flagship HBCU, partnered with PNC Bank — an institution with over $550 billion in assets — to create a $3.4 million annual entrepreneurship center focused on teaching students about wealth building, while Industrial Bank, a Black-owned institution with $723 million in assets, operates in Howard’s own backyard. Virginia Union University announced a real estate partnership with Keller Williams, a non-Black national franchise, rather than any of the Black-owned real estate firms operating in Richmond. Alabama State University directed a $125 million financial transaction to a non-Black institution when Black-owned alternatives existed. These are not isolated incidents. They are a pattern. The six-hour circulation rate of the Black dollar is not solely a consumer problem it is an institutional one. When the very institutions built to serve African America will not circulate capital with African American-owned enterprises, they are not just minding someone else’s store. They are funding it.

The late Dr. Amos Wilson, in his landmark work on Black economics, argued that the question of Black political and social power could not be separated from the question of Black economic power. You cannot negotiate from a position of strength when you are economically dependent on those with whom you are negotiating. This is not a new observation. Booker T. Washington said it. Marcus Garvey built a shipping line around it. The founders of Black Wall Street in Tulsa, Oklahoma died for it. What makes the Wal-Mart comparison so instructive is not that it should produce shame. It should produce strategy. When Sam Walton opened his first store, he was not competing with Sears and Kmart by screaming about their hiring practices. He was building infrastructure — distribution networks, vendor relationships, loss-leader pricing strategies, and real estate positioning. He was minding his store. The result, three generations later, is a company that generates more revenue than the combined output of all African American businesses in the nation. The African American community has the talent. We have demonstrated that abundantly, in every field from medicine to technology to entertainment to law. We have the consumer base. At $1.3 trillion in annual spending, the Black consumer market is the envy of marketers worldwide. What has historically been missing is the intentional, sustained, and institutionalized redirection of that spending power toward Black-owned businesses at scale.

It would be intellectually dishonest to lay the entire weight of this disparity at the feet of consumer behavior alone. Structural barriers to Black business ownership are real and documented. Access to capital remains the single greatest obstacle. African American business owners are rejected for small business loans at rates significantly higher than their white counterparts — Black-owned small businesses received full funding in just 38% of cases, compared with 62% for white-owned firms. The racial wealth gap — driven in large part by decades of discriminatory housing policy, redlining, and exclusion from wealth-building programs like the GI Bill — means that Black entrepreneurs often lack the family wealth and generational capital that serves as seed funding for so many successful businesses. But the capital problem runs even deeper than loan denial rates. According to HBCU Money’s 2024 African America Annual Wealth Report, African American household assets reached $7.1 trillion in 2024 — yet consumer credit has surged to $740 billion, now approaching near-parity with home mortgage obligations of $780 billion. For white and Asian households, the ratio of mortgage debt to consumer credit stands at approximately 3:1. For African American households, it is nearly 1:1 — meaning a disproportionate share of Black borrowing finances consumption rather than wealth-building assets. Consumer credit grew by 10.4% in 2024, more than double the 4.0% growth in mortgage debt, suggesting that rising asset values are not translating into improved financial flexibility. The community is running faster to stay in place.

What makes this particularly damaging for business formation is where that debt flows. With African American-owned banks holding just $6.4 billion in combined assets — down from 48 institutions in 2001 to just 18 today — the overwhelming majority of the $1.55 trillion in African American household liabilities flows to institutions outside the community. A conservative estimate puts annual interest payments transferred from Black households to non-Black financial institutions at approximately $120 billion. For context, that is more than half of what all Black-owned businesses generate in revenue in an entire year, flowing out of the community in interest payments alone. There is also genuine cause for measured optimism. The Brookings Institution found that Black-owned employer businesses grew by 56.9% between 2017 and 2022 with over half of all new employer businesses started in America during that period being Black-owned. Black-female-owned businesses grew at an even faster clip of 71.6%. Revenue from Black-owned employer businesses rose by 65.7%, and total payroll increased by 69.5%. This is not a community standing still. Yet consider what the employment numbers reveal about the depth of the remaining challenge. Of the roughly 22 million African Americans in the civilian labor force, only 1.2 million — fewer than 1 in 18 — work for a Black-owned business. That means the overwhelming majority of Black workers are building someone else’s enterprise, generating wealth that flows outside the community. Now consider this: there are approximately 3.4 million Black-owned non-employer firms — businesses with no employees at all. If every single one of those firms hired just one African American, Black business employment would go from 1.2 million to 4.6 million overnight — nearly quadrupling the number of African Americans whose economic livelihood is tied to Black ownership. That single hire, multiplied across 3.4 million businesses, would represent one of the most transformative economic shifts in African American history, without a single new business being started, without a single new law being passed, and without waiting for anyone’s permission. The challenge is that the gap between where we are and where parity demands we be remains enormous. Black Americans represent 14.4% of the U.S. population but own just 3.3% of employer businesses. To reach proportional representation, the number of Black-owned employer firms would need to more than quadruple. That is a generation’s worth of sustained work and it cannot be done without both structural support and the intentional recirculation of capital through Black-owned financial institutions. African American-owned banks, credit unions, and community development financial institutions exist specifically to fill this gap. HBCUs already produce 80% of the nation’s Black judges, half of its Black doctors, and a third of its Black STEM graduates — yet their business schools have yet to consolidate around a unifying entrepreneurial mission. A purpose-built African American MBA, anchored at HBCUs and focused explicitly on building and scaling Black-owned enterprises, could be the missing institutional link between Black talent and Black capital. The infrastructure, while still insufficient, is growing. The question is whether HBCUs — and the community they serve — will demand more of it.

Minding your own store does not mean ignoring injustice. It means recognizing that the most durable response to injustice is economic self-determination. It means that for every hour spent outraged about the New York Times culture desk, there should be five hours spent building, funding, patronizing, and amplifying African American-owned media. It means that HBCUs which have historically been the primary incubators of Black professional and entrepreneurial talent deserve the full financial and institutional support of the African American community, not just during homecoming season or when they make the national news for a coaching hire. It means that the $212 billion generated by African American employer businesses today should be $424 billion in a decade, and that achieving that goal requires both new business formation and a deliberate shift in where Black consumer dollars are spent. One company — one family’s vision, relentlessly executed over six decades — built an enterprise that generates more revenue than all 3.6 million Black-owned businesses in America combined. Imagine what those 3.6 million businesses could do if they were built with that same relentlessness, funded by that same community, and patronized by that same loyalty. That is the store worth minding. That is the story worth chasing.


HBCU Money is the leading financial resource for the HBCU community. Visit us at hbcumoney.com.

Disclaimer: This article was assisted by ClaudeAI.