“African Americans love to quote that the dollar does not stay in our community but a few hours, which is true, but it is the belief that if they just buckle down and patronize more Black businesses. Unfortunately, until we understand institution to institution circulation and retention of capital, patronizing is just a redundant talking point. The same as trying to move oil – with no pipelines.” – William A. Foster, IV
A city plans for a population of five hundred thousand. It builds roads sized for five hundred thousand, schools sized for five hundred thousand, a water system sized for five hundred thousand. Then, by policy rather than accident, it allows only thirty thousand of those residents to ever draw water from the municipal system. The other four hundred seventy thousand are permitted to live in the city, work in the city, pay taxes to the city but they must find their water elsewhere, in smaller private wells scattered across town, each one a fraction of the capacity the city itself was built to provide. No one calls this a water crisis. They call it culture, or preference, or the free market sorting itself out. The wells keep drying up. The city keeps growing. Nobody asks why the math never closes.
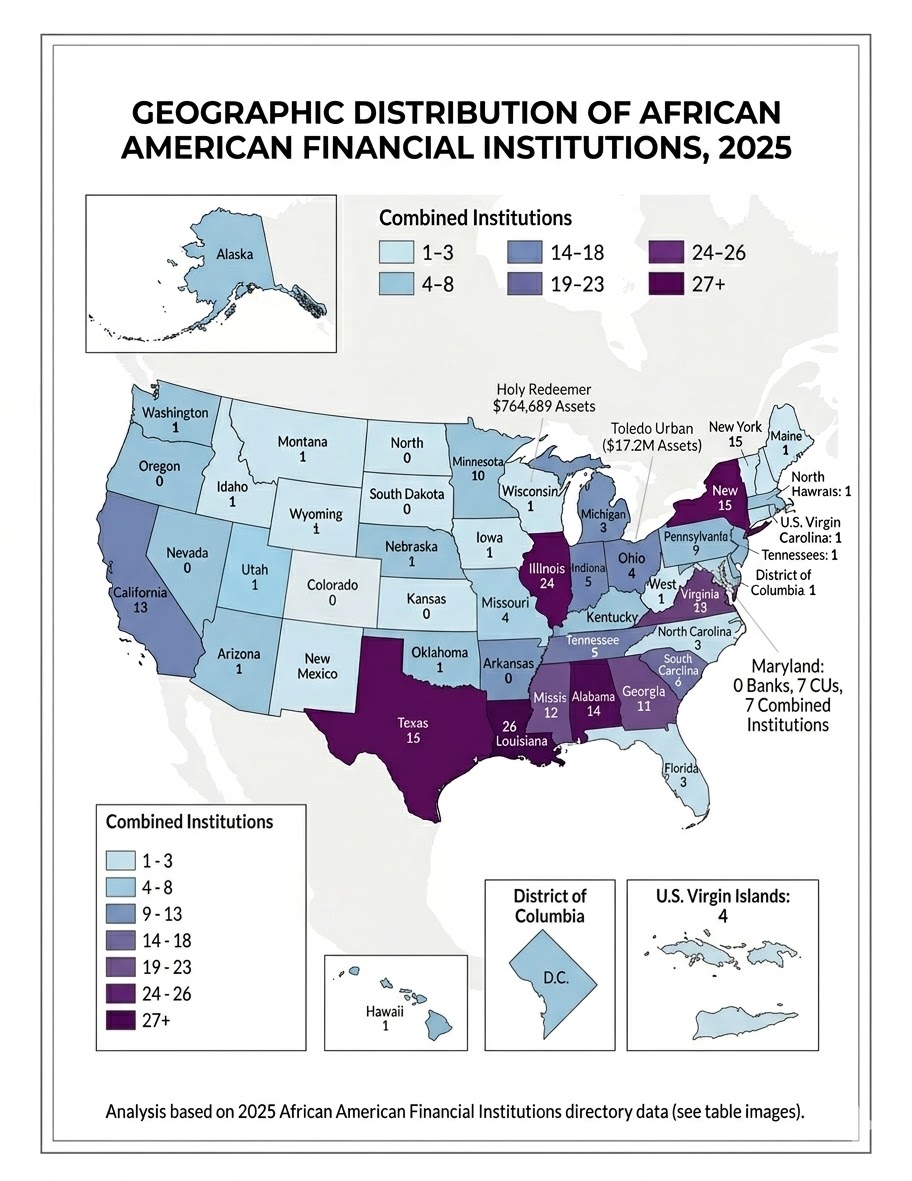
That is, in miniature, the condition of African American banking in the United States in 2025. It is not a story about seventeen small institutions doing their best against long odds, though that story is true and worth telling. It is a story about scale; about what full institutional participation in the American banking system would actually require, measured in dollars, and about how far short of that requirement the current system sits. The gap is not rhetorical. It is arithmetic, and once it is laid out in full, it becomes difficult to discuss African American banking capacity using the language of individual bank performance at all. The conversation has to move to population, to proportion, and to the institutional habits that keep the proportion from closing.
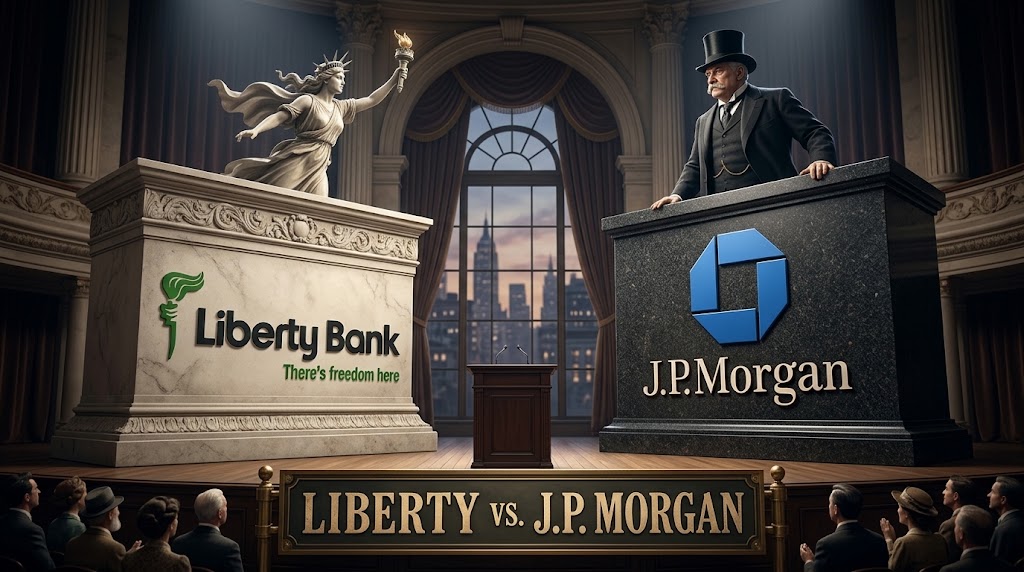
Start with the top of the American banking system. As of March 31, 2026, the seventeen largest U.S. domestically chartered commercial banks by consolidated assets led by JPMorgan Chase at just over $4.0 trillion, followed by Bank of America, Citibank, Wells Fargo, and thirteen others hold a combined $16.36 trillion in assets. Now set beside that figure the complete universe of African American-owned banks in the country: seventeen institutions, spanning fifteen states and territories, holding a combined $6.72 billion. The ratio between the two groups is roughly 2,432 to 1. JPMorgan Chase alone holds approximately 597 times the combined assets of every African American-owned bank in the country put together. Liberty Bank & Trust of New Orleans, the single largest African American-owned bank in America at $1.1 billion, is outweighed by JPMorgan Chase alone at a ratio of roughly 3,634 to 1.
The scale of that gap becomes easier to hold in mind with a single object. In October 2025, JPMorgan Chase opened its new global headquarters at 270 Park Avenue in Manhattan; a 1,388-foot tower designed by architect Norman Foster, built at a reported cost of approximately $4 billion. The building alone cost nearly 60 percent of the combined total assets of every African American-owned bank in the United States. JPMorgan Chase did not draw down its balance sheet to build it, did not strain its capital position, and continued operating as the largest bank in the world throughout construction. The tower is, in other words, a rounding error for JPMorgan Chase and very nearly the entire African American banking sector’s balance sheet at the same time, the same dollar figure describing two entirely different orders of magnitude, depending on which side of the ledger it sits.
These comparisons are dramatic, but they are also, in a sense, unfair not to African American banks, but to the argument. Comparing seventeen community and regional institutions to the seventeen largest banks in the wealthiest economy in human history will always produce a lopsided ratio; the same exercise run against Sweden’s entire banking sector would look similarly stark. The more useful question, and the one that actually measures institutional health, is proportional. What share of America’s banking assets would African American-owned banks hold if African America held banking assets in proportion to its share of the American population — no more, no less, simply parity?
The U.S. Census Bureau’s 2025 population estimates place the Black-alone population of the United States at approximately 46.2 million people, or roughly 13.5 percent of the national population. HBCU Money’s own 2025 African American Owned Bank Directory places total FDIC-tracked domestic bank assets at approximately $24.9 trillion. If African America held banking assets proportional to its population share of the country, African American-owned banks would need to control approximately $3.36 trillion in assets or 13.5 percent of $24.9 trillion. The actual figure, again, is $6.72 billion. The gap between where population parity would place African American banking capacity and where it actually sits is approximately $3.355 trillion. To close that gap through organic growth at current rates where the sector’s total assets grew from $6.4 billion in 2024 to $6.7 billion in 2025, a $326 million increase would take not years or decades but centuries. Put differently: African American-owned banks would need to be roughly 500 times larger, in aggregate, than they are today simply to reach proportional representation. Not to dominate the banking sector. Not to overtake it. To match it.
It is worth sitting with what $3.36 trillion actually represents, because the number is large enough to lose its meaning through repetition. It is larger than the GDP of every country on earth except roughly the top eight. It is more than five hundred times the combined assets of every African American-owned bank that currently exists. It is, notably, not money that needs to be created from nothing it already exists, circulating through the American banking system, much of it deposited by African American individuals, businesses, churches, fraternities and sororities, professional associations, and institutions, simply routed through banks that are not African American-owned. The gap is not primarily a wealth-creation problem, though wealth creation matters. It is a capital-retention and capital-routing problem. The money exists. It is banking somewhere else.
This is where the conversation has to move from macroeconomics to institutional behavior, because the population-parity gap cannot be explained by African American banks lacking capable leadership, sound underwriting, or FDIC compliance. It has to be explained by where African American capital — individual, corporate, and institutional — chooses to be deposited, and the data on that question is uncomfortable. HBCU Money’s 2023 analysis of HBCU banking relationships found that of the country’s 107 HBCUs (U.S. Department of Education designation) and roughly 68 to 104 Predominantly Black Institutions (a federally designated but demographically fluid category, per the Postsecondary National Policy Institute), together approximately 200 institutions, only two were believed to bank with an African American-owned institution: Florida Memorial University, an HBCU, and Roxbury Community College, a PBI, both of which bank with OneUnited Bank. That means the overwhelming majority of the flagship educational institutions of Black America, the same institutions publicly organized around the mission of Black advancement, do not patronize the Black banking sector at all. This is not a scattered oversight. It is a structural pattern, and it repeats across nearly every category of African American institution: businesses, chambers of commerce, professional associations, churches, fraternal organizations, and nonprofits overwhelmingly bank with mainstream white-owned lenders, not because those lenders are barred by any law from serving them, but because institutional inertia, existing banking relationships, perceived convenience, and — bluntly — habit route the capital elsewhere by default.
Consider the case that HBCU Money’s 2023 piece surfaced: Howard University, the most prominent HBCU in the country, entered a five-year, $3.4 million-per-year partnership with PNC Bank to fund an entrepreneurship center on its own campus. PNC is a fine institution and the grant funded real programming. But PNC’s consolidated assets stand at roughly $568 billion as of early 2026, an amount that dwarfs the combined assets of every remaining African American-owned bank many times over, while Industrial Bank, an African American-owned institution with over $770 million in assets, sits a few miles away in the same city Howard calls home, unbanked by the university it neighbors. This is not a story about villainy. PNC did not do anything wrong by funding a center at Howard. It is a story about institutional default: when the moment came to choose a banking partner, the largest, most convenient, most established option was chosen, and the community institution built to receive exactly this kind of patronage was not seriously considered as an alternative. Multiply that single decision by every HBCU, every Black professional association, every African American-owned business banking outside the sector, every fraternity and sorority housing its national treasury with a conventional lender, and the population-parity gap stops looking mysterious. It looks like the predictable output of thousands of individually reasonable decisions that, in aggregate, produce collective institutional abandonment.
The deeper issue is what might be called the B2B lapse in African America’s institutional framework, the absence of a functioning business-to-business and institution-to-institution circulation system comparable to what other ethnic economic communities maintain as a matter of course. Economic development research has long noted that a dollar circulating within a tightly networked community; Asian immigrant enclaves, Jewish community networks, historically insular white ethnic communities tends to pass through many hands and institutions before leaving that community’s economic orbit, sometimes for weeks. The African American dollar, by contrast, is frequently cited as leaving the community’s economic orbit within hours, not because African American consumers spend irresponsibly, but because the institutional infrastructure that would capture and recirculate that dollar: Black-owned suppliers banking with Black-owned banks, insured by Black-owned insurers, audited by Black-owned accounting firms, financed by Black-owned lenders was never built to the density that other communities achieved, and where pieces of it do exist, they are not systematically used by the institutions closest to them. This is Institutional Density and Capital Retention, HBCU Money’s foundational concepts, expressed as a single measurable failure: African American institutions do not bank African American, insure African American, or contract African American at anywhere near the rate that would let the ecosystem compound on itself.
The consequence of that lapse is not merely symbolic. Capital retention compounds. A dollar deposited in an African American-owned bank does not simply sit there; under fractional reserve banking, it becomes the basis for loans to African American-owned businesses, African American homebuyers, and African American institutions that a mainstream lender evaluating the same borrowers through unfamiliar underwriting assumptions, without community-specific knowledge, and often with documented disparities in approval rates is statistically less likely to extend. Every HBCU endowment, every Black professional association’s operating account, every Black-owned business’s payroll account that banks outside the African American-owned system is not merely a missed opportunity for solidarity. It is a forgone multiplier on the community’s own capital, and it is the single most tractable lever available for narrowing the $3.36 trillion gap, because it does not require new wealth creation, it requires redirection of wealth that already exists.
“Do we want power? Or do we want the illusion of inclusion and equality? Because they are not the same.”
An institutional ecosystem that controls 0.027 percent of its own country’s banking assets does not set terms — it accepts them, from lenders who evaluate its businesses, its homebuyers, and its institutions on assumptions built for someone else’s community. Every dollar redirected into an African American-owned bank is a dollar that compounds inside the ecosystem instead of outside it becoming loan capital for the next Black-owned business, the next Black homebuyer, the next Black institution, and every dollar that stays outside it is a dollar the ecosystem permanently forfeits control over. Closing the population-parity gap is not a matter of asking African American institutions to sacrifice convenience for symbolism. It is a matter of an ecosystem deciding whether it intends to hold power over its own capital or continue lending that power to institutions that already hold $16 trillion of it.
The apex of African American banking’s share of national assets was 1926, when the sector held roughly 0.2 percent of America’s banking assets; ten times its current 0.027 percent share, achieved with a fraction of today’s Black professional class, Black business revenue, and Black institutional wealth. The population-parity gap is not a ceiling African America has never approached. It is a floor the community once stood far closer to, and has since drifted away from not through catastrophe, but through a hundred years of unexamined institutional habit. Closing even a fraction of that distance would not require African America to build something unprecedented. It would require African America’s own institutions to stop routing their capital away from the very system built to hold it.
Disclaimer: This article was assisted by ClaudeAI.
 HBCU Money
