All banks are listed by state. In order to be listed in our directory the bank must have at least 51 percent African American ownership. You can click on the bank name to go directly to their website.
OTHER KEY FINDINGS:
11 of the 16 African American Owned Banks saw increases in assets from 2021.
African American Owned Banks (AAOBs) are in 15 states and territories. Key states absent are Maryland, Missouri, New York, Ohio, and Virginia.
Liberty Bank and Trust Company is headquartered in Louisiana, but also operates in 7 other states including Mississippi; Kansas and Missouri; Michigan; Alabama; Illinois; and Texas. OneUnited is headquartered in Massachusetts, but also operates in California and Florida.
There has not been an African American Owned Bank (AAOB) started in 23 years.
Alabama and Georgia each have two AAOBs.
African American Owned Banks have approximately $5.5 billion of America’s $22.9 trillion bank assets or 0.02 percent.
African American Owned Banks control 1.7 percent of FDIC designated Minority-Owned Bank Assets.
2022 Median AAOBs Assets: $150,072,000 ($194,181,000)
2022 Average AAOBs Assets: $325,391,000 ($297,692,000)
TOTAL AFRICAN AMERICAN OWNED BANK ASSETS 2022: $5,531,655,000 ($4,763,079)
The ache for home lives in all of us, the safe place where we can go as we are and not be questioned. Maya Angelou
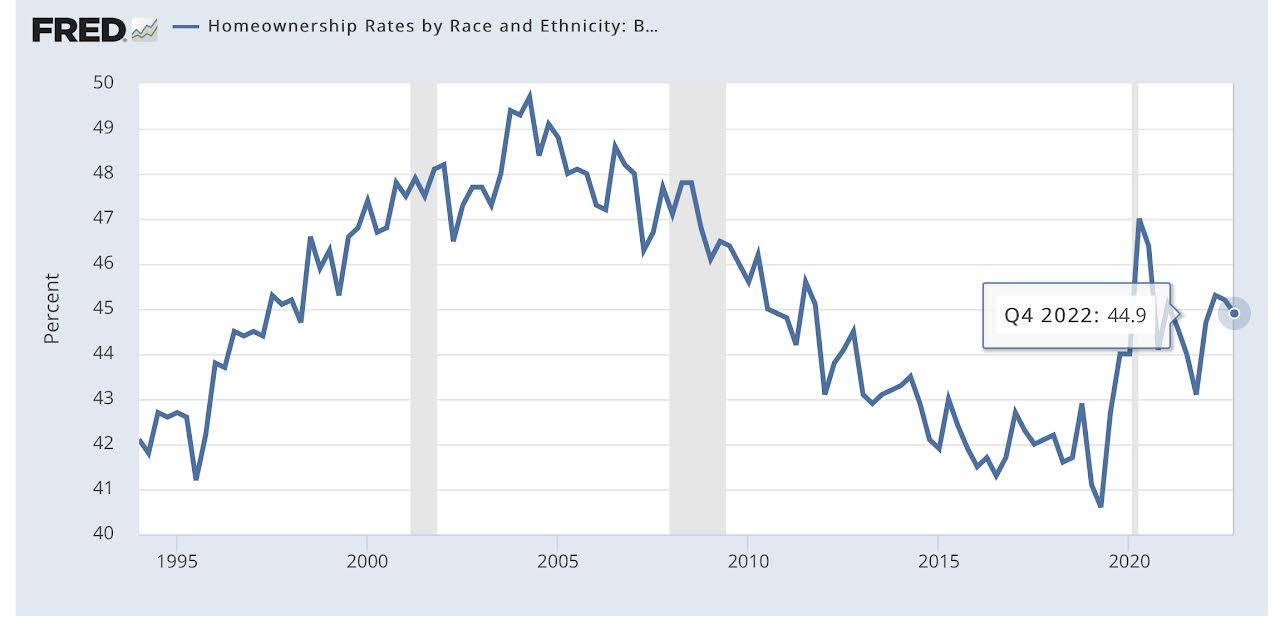
African American homeownership (pictured below) has never breached above 50 percent. Ever. According to HBCU Money data, it would take $14.7 billion in down payments for African American homeownership to just reach 50.1 percent. This is assuming that those 900,000 African American households would only be using FHA at 3.5 percent down. A debatable matter on the risk side that such low down payments would pose to households should the real estate market turn against them in the early years of their ownership. The $14.7 billion could decrease given the geography of African Americans being predominantly focused in the southeastern United States where homes on the whole are cheaper than much of the rest of the country. Using the southeastern median home price in fact would drop the $14.7 billion down to $12.3 billion. How big is this number? African American owned banks (what is left of them) only hold $4.3 billion in assets combined. The approximately 100 remaining HBCUs have combined endowments of around $3 billion. There are 44 people (none of which are African Americans) on the Forbes 400 who are individually worth more than $14.7 billion.
The causes of this are many, but the impact of it has been extremely pointed. In a country where homeownership has significant social and economic value to a group, African Americans have largely been starved of the social and economic oxygen that homeownership prevails and continue to lack the ecosystem necessary to make the sustained push above and beyond what has now become the mythical 50 percent line. But all hope is not lost.
Recently, Carla Holmes, a Norfolk State University alumnae and community banker, sat down for an interview to discuss the history of African American homeownership and more importantly the potential path forward. “I often say that community development found me. I noticed there was a need for education and training in the community and especially in the Black community in moving towards homeownership and understanding more about affordable housing.”
As a leader, you must consistently drive effective communication. Meetings must be deliberate and intentional – your organizational rhythm should value purpose over habit and effectiveness over efficiency. – Chris Fussell
In the world of economic development and real estate development there are fundamentals that allow for development to take place. One of those fundamentals is what is known as an anchor. According to Janover Commercial Real Estate, “An anchor tenant is the largest or most prominent store in a retail commercial real estate development, intended to help draw customers into the area. In strip centers and power centers, anchor tenants are often big-box stores or grocery stores, while in shopping malls, they’re more likely to be department stores.” Anchors can be a myriad of things such as neighborhoods, megachurches, downtowns, boarding schools, and yes (but not limited too) colleges and universities.
It is a simple question really. What good is African America’s $1.6 trillion in buying power if all of it goes into companies owned by non-African Americans? From the FAMUAN Online, “Studies say that the average lifespan of the dollar is approximately 28 days in Asian communities, 19 days in Jewish communities, 17 days in white communities — and just six hours in Black communities.” Yet it seems there is no actual intentionality on changing this. No thought to why it is happening and certainly no thought to solutions. One major issue of course is that everything African American institutionally operates on an island. There is virtually no interconnectivity between African American institutions or intentionality on creating it. The real question begs, do we understand what it would take to actually increase the African American dollars circulation?
There are a plethora of independent Black owned coffee shops in every city where an HBCU is located and yet HBCUs are more excited to bring Starbucks to their campus. Texas Southern and Prairie View A&M University could feature The Breakfast Klub on their campus, but instead Sodexho, a French owned company, dominates their food services and many other HBCUs. An opportunity to create a food hall of locally owned African American food businesses both on and near our campuses is missed, ignored, simply not considered. The opportunity to have African American banks and credit unions present on or near our campuses – again, missed, ignored, and simply not considered. Many have argued that HBCUs banking needs are too big for African American owned banks. Despite, Florida Memorial University and Roxbury Community College, an HBCU and PBI both banking with OneUnited Bank. Albeit they are smaller HBCUs, this claim that HBCUs financial needs are beyond that of African American owned banks is not actually founded in any real assessment. Even if one were to go with this notion (as faulty as it is) this does not remove the institutions ability to ensure African American banks and credit unions have access to their faculty, staff, and students to open accounts and build relationships. What about the Divine 9, student organizations, and the like? Do we believe they too have to “complicated” of financial needs to not bank with an African American owned bank or credit union? Even if just the faculty, staff, students, and low level organizations with the campus banked with African American owned banks it would be enough to double the size of them alone. This lack of intentionality is painfully screaming at us. Opportunities for HBCU/African American health providers like dentists, doctors, therapists, etc. to be given space on or near HBCU campuses could be highly proactive in addressing and preventing many of the health crises we find the African American community facing.
What happens if we become intentional? What happens if we become proactive and not reactive to trying to circulate the African American dollar using HBCUs as the anchor? These small businesses grow first and foremost. With this growth come jobs and interns for our students, new wealth for the owners of the businesses and an opportunity for HBCUs to build sponsorship and endowment relationships with them. Our students working for these African American firms are now using their intellectual capital to build more African American institutions, reducing their own student debt loads while in college, and maybe just maybe be an early employee that received stock options that make them a millionaire of the next Google, FedEx, Microsoft, Dell, Nike, SNL Financial, or any of the other major companies that we may or may not realize were started on college campuses and in college towns. Except in this case, they are companies that are HBCU Alumni/African American owned. Those banks and credit unions would then be able to open multiple branches and put predatory financial services in our communities out of business. They would have the deposit bases to offer more small business loans for HBCU entrepreneurs and mortgage loans for HBCU homeowners. This is not even to speak of the implications of such an increase in the tax base in those areas that the K-12 schools that often surround HBCUs would significantly benefit. K-12s that are usually filled with African American children who could one day be HBCU students. The multiplier effect due to the intentional circulation could be hard to measure because there are so many social, economic, and even political ramifications of our intentionality when it comes to the African American dollar, but to say it would be a profound paradigm shift would be an understatement.
All banks are listed by state. In order to be listed in our directory the bank must have at least 51 percent African American ownership. You can click on the bank name to go directly to their website.
OTHER KEY FINDINGS:
African American Owned Banks (AAOBs) are in 14 states and territories. Key states absent are Maryland, Mississippi, New York, Ohio, and Virginia.
There has not been an African American Owned Bank (AAOB) started in 22 years.
Alabama and Georgia each have two AAOBs.
14 of the 16 African American Owned Banks saw increases in assets from the previous directory.
African American Owned Banks have approximately $4.8 billion of America’s $22.8 trillion bank assets or 0.02 percent.
African American Owned Banks control 1.5 percent of FDIC designated Minority-Owned Bank Assets, which is down from 1.7 percent in 2020. A fourth straight year of declines.
2021 Median AAOBs Assets: $192,932,000 ($106,140,000)
2021 Average AAOBs Assets: $302,218,000 ($225,519,000)
For comparison, Asian American Owned Banks have approximately $66.7 billion in assets spread over 61 institutions. Asian American Owned Banks saw a decrease of $62.6 billion increase (48.4 percent) since 2020.
TOTAL AFRICAN AMERICAN OWNED BANK ASSETS: $4,835,494,000
Owning a home is a keystone of wealth – both financial affluence and emotional security. – Suze Orman
Poor people know they are poor. Unfortunately, it is the African American working and middle class who do not know they are also poor. The problematic reality that because you can buy something does not mean you can afford it plagues much of African America’s working and middle class. These tend to be households who have higher education, higher incomes, and higher homeownership rates – but they also tend to have financial net worths that are just as poor as – well, the poor. Why? They tend to be more acutely indebted due to their education, home, car, and consumer poor, just as financially illiterate, and almost always just as asset poor as their poor counterparts in the African American community. However, any conversation about passive or investment income or financial health as a pillar in line with mental health and other priorities of a well functioning household is often met with angst or disgust. The prioritization of asset accumulation over consumption is met with more resistance than Americans against British taxation without representation – and we know how that ended. But not to worry, there seems to be no revolution brewing here (sarcasm). African American wealth accumulation continues to be an afterthought of the African American household. Upper middle class, affluent, rich, or wealthy being a thought of more as something for “others” and not ourselves. The achievement of degrees, a house, cars, and consumption is all we seem to believe life requires. Should times get tough, many within the community will tell you that a second job, a better paying job, or more education is more times than not the answer to a “better” life. Again, wealth and asset accumulation not so much.
How dire is the wealth situation for African America? Bloomberg recently reported that Black-White wealth gap has not budged in the past 40 plus years and is actually trending worse. McKinsey and Company report that nearly 20 percent of African American households have a negative net worth. The National Community Reinvestment Council’s report shows, “African Americans, who in many categories have the greatest gender economic equality, have the greatest gender wealth disparity though still having little wealth compared to Whites. Single Black men’s median wealth was $10,100, compared to Single Black women’s median wealth of $1,700.” An immense issue when one considers that the majority of African American households are headed up by single African American women. One would certainly suggest that because women are the load bearers for raising and providing for African American children and often extended family that this has also severely hampered their ability to accumulate wealth. An issue that is not as prevalent for African American men. None the less, it proves dire for the community as a whole that this is the case. Last but certainly not least (or all), there is the matter that African American homeownership has never breached above 50 percent which for the majority of families serves as the foundation that a lot of intergenerational wealth is built upon.
One of the general wedges to the wealth gap is asset ownership. Two-thirds of African American wealth according to Bloomberg is held in housing and very little in other asset classes like stocks in particular. This has presented an acute problem over the past 70 years as Bloomberg reports, “stocks have appreciated five times as much as housing prices.” However, the complexity of wealth without a conversation around income and disposable income which is income left over after expenses that can be used for savings and investing is vital to the conversation. African American median income is $45,870 according to Statista, the highest it has been in the past 30 years. The problem of course is that it remains the lowest of all four ethnic groups tracked (see graph below) with Latinos, European, and Asian Americans having median incomes of $55,321, $74,912, $94,903, respectively. Unfortunately, there is not a high enough savings rate that could truly overcome this lack of income. Despite the perception, African Americans are savers in line with their European American counterparts. Again, you can not catch up in a race running at the same speed as someone who is 100 yards ahead of you. This is the problem for African America. We are trying to save and invest at the same rate as those who have in most cases six times our wealth. So if home ownership is already our largest asset, then why are we suggesting that African American couples prioritize having two going into a marriage rather than one after they get married?
Every HBCU state except for Pennsylvania offers a homestead exemption. What is the homestead exemption? According to Investopedia, “The homestead exemption is a way to minimize property taxes for homeowners. It is also a legal provision offered in most states that helps shield a home from some creditors following the death of a homeowner’s spouse or the declaration of bankruptcy. The homestead tax exemption can provide surviving spouses with ongoing property tax relief, which is done on a graduated scale so that homes with lower assessed values benefit the most. The homestead exemption is helpful since it is designed to provide both physical shelter and financial protection, which can block the forced sale of a primary residence.” A person or couple can only have one homestead at a time, unless they both enter into the marriage with their own homestead. At which point, both parties are allowed to retain their individual homesteads. This means both properties will be taxed at a reduced rate creating more disposable income. Something they would not be able to do if they simply purchased a second home later in the marriage. What is that second homestead worth potentially?
According to Mortgage Calculator, the average annual property taxes in the United States is approximately $3,800. The homestead exemption typically saves approximately $500 off of that tax bill. That $500 invested annually for 30 years at 8 percent return is worth over an extra $60,000 to a household and that is just the tax savings reinvested. Naturally, the second homestead would be rented out by the couple and used to generate additional passive income. Assuming the couple could generate a profit of $200 per month or $2,400 annually off that second property, they now have $2,900 to invest annually which over the course of 30 years at 8 percent return is worth over $350,000. We have not even added on the building of the equity from appreciation or the extremely low interest rates that accompany homestead properties versus traditional investment properties. Banks are far more likely to see a homestead property as a lower risk than investment properties which they believe a borrower is more likely to walk away from than those that are homesteaded. Equity borrowed from the home could be used to reduce the households general tax bill overall further, leveraged to purchase non-homestead investment properties, or simply borrowed and used to invest in the stock market and because it is seen as “debt” does not carry tax liability on it. In other words, if a couple borrows $50,000 of equity out of their homestead property and make $10,000 on it, then they would only be paying taxes on the $10,000 but you still actually have $60,000 at your disposal. Whereas if you saved $50,000 and then made $10,000 on it, then you would be paying taxes on the entire $60,000. That almost $3,000 per year that would be coming from that property would also be an increase of 6 percent on the African American median income.
In the end of it all, assets and income go hand in hand. The more assets a family has the more income they produce and vice versa. In some ways, it is the epitome of the chicken and the egg conversation. For most African Americans, whom we see are highly unlikely to receive inheritance (see graph above) it becomes all about their family’s initial income and the race to acquire assets. Grievously, far too many African American families get the income and never convert it into assets. Taking advantage of prioritizing this little loophole can provide a family an extra $1 million in asset value and $80,000 in passive income if properly managed. An amount that currently would equal almost two times the African American median income. It is these small decisions that could have a monumental impact on the future of African American wealth and the closing of the wealth gap. In order for this to work as part of an overall strategy, HBCU alumni must prioritize having a sense of urgency about their finances and then be strategic about wealth and asset accumulation before tying the knot.



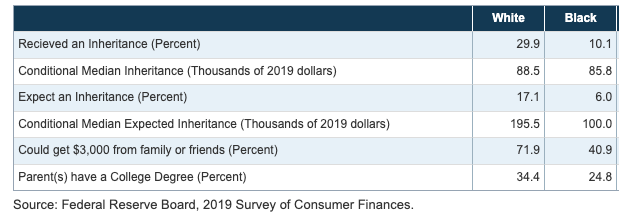
 HBCU Money
