Category Archives: Business

How the Government Helped White Americans Steal Black Farmland – And Why 1890 HBCUs Are Partially To Blame

Every good citizen makes his country’s honor his own, and cherishes it not only as precious but as sacred. He is willing to risk his life in its defense and is conscious that he gains protection while he gives it. – Andrew Jackson
Ukraine has been preparing for years for the eventual invasion that would come from Russia. It has been so even prior to Russia’s invasion and capture of Crimea in 2014. Why? Ukraine’s intelligence for one, President Vladamir Putin’s writings that expressed sentiment that the breakup of the Soviet Union was a great tragedy of the 20th century, Russia’s 2008 invasion of Georgia, and because well that is WHO Russia is and has shown itself to be. It would have been more of a shock were Ukraine to act shocked at Russia invading more than Russia invading. Put another way, if Ike Turner slapped someone and they were surprised, who is crazier – them or Ike Turner?

This seems to be African America always when it comes to European America though. Constantly surprised by consistent behavior. Harlem, Houston’s Third Ward, New Orleans, Compton, Roxbury, so on and so forth. What do all of these have in common? They were once thriving African American strongholds until gentrification. Each time the gentrification wave came, African Americans in those communities were caught off guard, unable and unprepared to launch a counterattack (or offensive).

In a recent article by The New Republic titled, “How the Government Helped White Americans Steal Black Farmland”, in detailed fashion we learned about one of the most vital departments of any country, agriculture, which impacts land, development, life expectancy, water and mineral rights, and so much more was used by the U.S. government through the USDA to spearhead the wealth transfer of African American farmland into European America’s hands. “Black farmers not only lost out on these massive subsidies—they have been effectively disenfranchised within the modern agricultural system. Under conditions of savage oppression, Black families emerged in the early 1900s with almost 20 million acres of farmland and “the largest amount of property they would ever own within the United States,” according to the historian Manning Marable. Since then, they have lost roughly 90 percent of that acreage” says New Republic. According to New Republic, there will be a study put out soon by the American Economic Association’s Papers and Proceedings journal that will value the land lost between 1920 and 1997 at approximately $326 billion. An amount that is equal to over 20 percent of African America’s $1.6 trillion buying power. The $326 billion valuation excludes the 160 million acres that Africa Americans who were enslaved were owed post Civil War from Special Order No. 15 that guaranteed the former enslaved population of around 4 million 40 acres apiece, but was reneged upon by the U.S. government ultimately making the loss arguably worth trillions today. Yes, trillions. The economic loss has had catastrophic social, economic, and political echoing impacts for generations. “Revolution is based on land. Land is the basis of all independence. Land is the basis of freedom, justice, and equality”, Malcolm X said. This alluded to the belief that every revolution was and is about land given that it impacts everything that lays to bear on any group, community, country, and diaspora. African American institutions, especially those focused on agriculture, should have made the protection of African American land a strategic priority.

Enter the 1890 HBCUs, which were created with the Second Morrill Act of 1890. There were 19 HBCUs created under this act (and two HBCUs which were created under the First Morrill Act of 1862, which primarily created HWCU agriculturally focused colleges and universities). For all intents and purpose, 1862 and 1890 colleges and universities were created with an emphasis on agriculture. Tuskegee, through the political clout of Booker T. Washington, is the only private HBCU that has land-grant status. The other two private universities that are land-grant institutions are Cornell and MIT. Among the 1890 HBCUs, they have three of the six HBCU law schools housed at Florida A&M University, Southern University System, and University of the District of the Columbia. Despite this, based on their websites none of three have any focus/concentration on agricultural law. This means that more than likely African American farmers and landowners are in the hands of lawyers who are both non-African American and trained at an HWCU/PWI institution. Given historical behavior, it is not hard to assume that those lawyers do not work in the best interest of our community. It also once again poses the question of the lack of strategy among African America at using its institutions to protect its social, economic, and political interest. Stemming the tide requires a change in HBCU strategy and realizing the purpose of our institutions is to serve and protect the other parts of the African American ecosystem.

There are a few pointed pivots that 1890 HBCUs can do to serve and protect the agricultural interest of African America. First, the three 1890 law schools (FAMU, SUS, and UDC) can create an African American agriculture concentration in their law schools. Again, to be clear, an African American agriculture concentration is not the same as general agriculture, which tends to be from a Eurocentric perspective. Focusing on agricultural law from the African American agricultural perspective and interest is paramount. Secondly, the three 1890 law schools can create a joint organization for African American Agriculture Defense Fund that will serve as a means to fund law defense for African American farmers, lobbying efforts towards African American agriculture, and regional African American agriculture legal research. Thirdly, all of the 1890 HBCUs needs to create master’s programs in agricultural law and policy focused on their respective local, state, and regional geographies. They can then push for alumni to create scholarships that will allow for a pipeline of agriculture majors to pursue law degrees at the three 1890 HBCU law schools. Lastly (but not all), a concerted emphasis on offering courses, lectures, and seminars on the purchase and maintenance of African American land ownership emphasized to students and alumni and available to our entire community.

If HBCUs are not going to be part of the institutional ecosystem built to serve and protect African American interest, then what is their purpose? Without protecting African American land, what little is left of it, then what is to come of African America? Protecting African American land takes more than just HBCUs, it also requires African American owned financial institutions, real estate organizations, families, communities, and more. However, 1890 HBCUs must take the vanguard and protect what we have so that we can start to stem the tide and move the trend upward again. The notion that land theft and assaults have been happening to African America for 100 years and we still have yet to respond with a counterattack or an offensive of our own is telling. HBCUs also are becoming more and more vulnerable to their land and the communities they are in, which are typically African American, being gentrified and the use of predatory land theft and assaults heightened. Howard University, Prairie View A&M University, and Texas Southern University all are witnessing land theft and assaults on the land surrounding their institutions. Unfortunately, there was and continues to be no unified strategic planning to protect them. In Howard University’s case, white residents have even been so gall as to suggest that the school be moved. This is just one example of over a century of attitudes that have helped lead to others justifying land assaults on African American landownership. We know who are our enemies are, we have the intelligence and tools, now is the time to start urgently preparing our troops to defend our lands.
Can NFTs Help HBCUs Close The Endowment Gap?

Black people lived right by the railroad tracks, and the train would shake their houses at night. I would hear it as a boy, and I thought: I’m gonna make a song that sounds like that. – Little Richards

The individual, familial, community, and institutional wealth gaps between African America and all other groups continues to widen. Despite the consequential donations from Mackenzie Scott and Michael Bloomberg in 2020 to HBCUs it is simply not enough consistently and overwhelming enough to put out the fire. That fire being the HWCU-HBCU endowment gap, which is over $100 to $1 – and widening. Ironically, African America is often standing there with a water hose in their hand watching their house burn while waiting on their neighbor to bring a bucket of water over and help. Why do we say African America has the water hose? By HBCU Money estimates, African America’s tuition revenue value to all colleges is worth $60 billion annually – only $6 billion of that goes makes it way to HBCUs. There are 100 plus HBCUs, but only two have institutional banking relationships with African American owned banks. In other words, there are things that if we just looked inwardly there would be substantive change happening. Instead, we continue to wait for the “lottery” of other’s grace to befall upon us. And to that point, one of the greatest financial opportunities of our lifetime maybe falling upon us to use a resource within our institutions – our creativity.

It is no secret that African American creativity drives American culture. African American creativity has and is often exploited to the social and financial benefit of other groups. There maybe no greater example of that than hip-hop (and the music industry in general) where African American musicians created a genre of music that is now global in reach, but very little of it is actually owned by African Americans. Enter, the internet. Enter, NFTs. The internet is not flat nor is it democratized – after all even on the internet all of the mediums like Amazon, Facebook, Alphabet, Twitter, Square, etc. none are owned by African Americans. However, there is an increasing amount of decentralization that seems to be taking root in pockets of the World Wide Web where opportunities can be staked out. For instance, had an HBCU endowment in July 2011 purchased 5,000 bitcoins which at the time were $13.91 for a total of $69,550, then that HBCU today would have a value of $330 million today. To the best of our knowledge, there are no HBCUs holding bitcoin or any other cryptocurrencies in their portfolio. And while there is still plenty of time to add cryptocurrencies to the portfolio, there is also a new opportunity that one could easily argue is the equivalent of buying cryptocurrencies ten years ago. The NFT.

NFTs or non-fungible tokens are “Non-fungible” more or less means that it’s unique and can not be replaced with something else. For example, a bitcoin is fungible — trade one for another bitcoin, and you’ll have exactly the same thing. A one-of-a-kind trading card, however, is non-fungible. If you traded it for a different card, you’d have something completely different.”, says Mitchell Clark from The Verge. NFTs also work off the Ethereum blockchain, Ethereum being a cryptocurrency and blockchains are a digital distributed, decentralized, public ledger that exists across a network. So what can be a NFT? Again, Mitchell Clark from The Verge, “NFTs can really be anything digital (such as drawings, music, your brain downloaded and turned into an AI), but a lot of the current excitement is around using the tech to sell digital art.” NFTs are already showing their potential. A 14-year old girl made over $1 million from selling 8,000 NFTs according to Business Insider. The most expensive NFT sold to date went for $69 million at Christie’s. An amount that would still be greater than any donation ever given to an HBCU. Now imagine unlocking the creativity that exist on HBCU campuses with students, faculty, and staff.

This could ultimately be a win-win for everyone involved if setup properly. HBCUs can provide the space, hardware, infrastructure, and other support needed while students, faculty, and staff can provide the immense creative capital that we know. Unlocking African America creativity on campuses could quite literally means tens if not hundreds of billions into African American families, communities, and HBCUs. The incentive for HBCUs to invest in this infrastructure is simple. Financially more stable graduates, improved retention rates, potentially higher alumni donor rates, and a new stream of income for endowments.

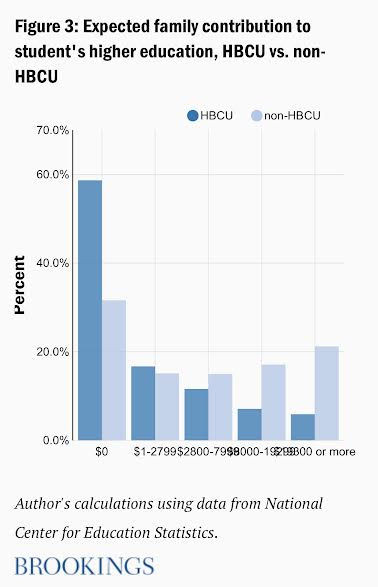
Students could see themselves earning enough to reduce or eliminate student borrowing costs. An immense hinderance to HBCU graduates creating generational wealth for themselves and their family. This barrier to wealth also is something that it could be argued contributes to poor alumni donor giving at HBCUs. HBCU donations of significance often come from older HBCU alumni who tend to wait and give a large donation either at the end of life or through their estate once they have passed on. HBCU students on a whole as reflecting in HBCU Pell Grant numbers are coming from far more low-income backgrounds their PWI counterparts. Brookings reports that almost 60% of HBCU students expect $0 in family contributions (graph below) to their education as opposed to less than one-third for non-HBCU students. On the other end less than 6 percent of HBCU students expect their family to contribute at least $19,300 to their education versus over 20 percent of non-HBCU students. This means that despite HBCUs on average costing significantly less than their PWI counterparts, HBCU students are still more likely to graduate with student loan debt and significant student loan debt loads. The most recent HBCU Money report showing that 86 percent of HBCU graduates finish with debt and a median of over $34,000 in student loan debt versus 40 percent and $24,000 in student loan debt for those coming from Top 50 endowed colleges and universities.

For HBCUs, the previous mentioned is great for their long-term sustainability, but in this case there is a huge financial reward to be had by HBCU endowments today. By providing the infrastructure, helping ensure the intellectual property rights, and more – HBCUs can create financial partnerships with students, faculty, and staff. This means that in the same way there is NIL (name, image, likeness) happening in collegiate sports, HBCUs too could use these partnerships as a means to recruit more African American faculty who often cringe at the pay rates at HBCUs. It also means that if a student, faculty, or staff produces an NFT for example that sells for $100,000, then potentially on a 50-50 split that the HBCU’s endowment just increased by $50,000. There is also the opportunity to have a foray into the entrepreneurship that is already taking root in the NFT as well as the supporting properties that will support it as an industry and asset class. As we mentioned, intellectual property attorneys in this new age will become even more valuable. There are currently six HBCU law schools who could create a focus on both IP and on digital IP in particular and those schools would be rewarded handsomely by being at the forefront of the curve. Simply put, there is just too much opportunity and money that has yet to even scratch the surface of value for HBCUs to not get involved in NFTs.

The acute importance of closing the endowment gap must be at the forefront of HBCU alumni conversations if our institutions are to be sustained into the next Millenia. It must be if we are to take serious the closing of the individual and institutional wealth gaps for African America. More importantly if HBCUs are to move beyond simply surviving and into empowered institutions that are truly able to serve the social, economic, and political interest of African America and the Diaspora, then having the institutional wealth and endowments necessary to do so is paramount. Climbing this mountain will be no easy task, but we can simply look at the wealth that has been created by our labor and our creativity as an enduring possibility of possibility. This time we must be the ownership of that creativity and protect its ownership at all costs.

Texas Southern University Host NAREB’s Black Homeownership Summit

“We need to intentionally invest in health, in home ownership, in entrepreneurship, in access to democracy, in economic empowerment. If we don’t do these things, we shouldn’t be surprised that racial inequality persists because inequalities compound.” – Pete Buttigieg

On the campus of Texas Southern University on November 4th and 5th, the National Association of Real Estate Brokers, an organization representing the interest of African American real estate professionals, hosted a homeownership summit with focuses on not only homeownership, but also student debt, access to credit, and investing. The importance of such an event being held on an HBCU campus can not be understated.

Intertwining African American institutions with each other has long been a struggle for the community’s development with African American institutions often operating on islands instead of a connected ecosystem. Events like NAREB’s Black Homeownership Summit at Texas Southern University helps highlight the power, potential, and scalability of what happens when African American (and Diaspora) institutions work together. What better place to address Black homeownership after all than on the campus of an HBCU? Soon to be African American graduates and professionals will be at the vanguard of trying to close the acute homeownership crisis that African America continues to face (graph below).

One of the keynote speakers at the NAREB Black Homeownership Summit event was Teresa Bryce Bazemore, CEO and President of the Federal Home Loan Bank of San Francisco, speaking exclusively to HBCU Money about the event said, “We need all the parties in the housing finance industry and other stakeholders to collectively work to eliminate the barriers to homeownership. In this new environment, all consumers including Black and Brown people should be able to participate equally in the dream of homeownership. We need initiatives that can help potential buyers with improving their credit, saving for down payments and understanding the entire home buying process from A to Z. We also need to make sure that the lending rules are equitable.”

HBCU Money’s Suggested Five Initiatives For HBCUs Can/Should Be But Not Limited Too:

  • Making financial literacy a mandatory part of matriculation for HBCU students. This can be done through the financial aid office, workshops, or a class.
  • Providing HBCU students work study jobs that go into the community at African American K-12 schools and teaching financial literacy.
  • Partnering with African American owned banks and credit unions. Due to their deposit bases, many African American owned banks and credit unions simply can not participate in the primary mortgage market and there are few to none African American owned non-bank mortgage lenders. This leaves the African American community in an extremely vulnerable position to predatory lending as has been demonstrated and shown time and time again. HBCUs are a key to growing assets within African American financial institutions through students, alumni, and institutionally.
  • Offering more scholarships for ALL students. Scholarships are purposed to reduce student loan debt, but they are often resigned to high achieving students despite the majority of students being in the middle. This becomes highly problematic for African Americans who usually do not have the familial wealth to assist in paying down or off their student loan debt. HBCUs while cheaper than our PWI counterparts on the whole could be doing even more to reduce the student loan debt burden for African American students by ensuring that any student who is academically eligible has an opportunity to reduce their student loan debt burden. This provides an opportunity upon graduation that more of their initial paycheck is going towards wealth building and potential homeownership rather than debt burden.
  • Encouraging the use of startups like HBCU Real Estate, who has part of their mission statement to use a portion of their profits to provide down payment assistance for HBCU alumni who seek to purchase primary or investment properties.

Homeownership and real estate ownership have long been a cornerstone to establishing generational wealth in the United States. Despite this, the African American homeownership has never crossed over the 50 percent threshold and according to MarketWatch and has always maintained a 20-30 percentage point gap between African and European Americans. African America’s civilian noninsittuional population as of October 2021 was 33.7 million and its civilian labor force is 20.6 million and the African American labor force 20 and over is 19.9 million. Assuming that 44 percent of the 19.9 million are homeowners (8.7 million), it would take approximately 1.5 million more African Americans to become homeowners to get African America above 51 percent. Based on the most recent data provided by Zillow, the typical value of U.S. homes is $308,220 as of September 2021. Between 1999 and 2021, the median price has almost tripled from $111,000 to $308,220. This means in order for those 1.5 million to acquire homes they would need down payments of approximately $16.2 billion using FHA’s 3.5 percent down financing or $10,800 per potential African American homebuyer. While it does not on the surface seem like a lot to many, that number represents almost 45 percent of the African American median net worth, but a mere 6 percent of European American median net worth.

Just for perspective on that $16.2 billion, there are no African Americans with a net worth more than that, but there are 45 Americans whose single net worth exceeds $16.2 billion. The road to achieving more African American homeownership will be no small task, but events like NAREB/Texas Southern will go a long way in us doing the hard work together, lifting the heavy load together, and ultimately achieving our goal together.

Internet Services Startup Launched By Three HBCUpreneurs – Who Have Never Met

“Great things in business are never done by one person. They’re done by a team of people.” – Steve Jobs

It is a business story worthy of Hollywood. Mainly because it seems to be a storyline that you only find in movies. However, the story is very real and very powerful. Not only because of its potential, but also because of the possibilities that it presents. Three HBCUpreneurs from three different HBCUs start a business, but have never actually met each other in person. The power of the internet, the power of Twitter and most importantly, the power of the HBCU community.

The company, HBCU Real Estate, is an internet services company that seeks to help the HBCU community (but not limited too) find and use HBCU real estate service providers. Everything from real estate agents, mortgage brokers, interior designers, and more. The founders hope that it will even lead to business creation in the spaces of real estate that the HBCU community may have little to no presence. HBCU Money is aware of only one title company* owned by an HBCU alumnus. HBCU Real Estate’s mission is to help facilitate circulation of the HBCU community’s dollars and keep them in the HBCU community. If successful, it could potentially keep tens of billions of dollars within the HBCU community. The fact that none of the founders have ever met in person makes what they are trying to accomplish even more astounding.

For two years it sat on the proverbial shelf according to organizer, cofounder, and HBCU Real Estate’s Director of Product Development, William A. Foster, IV, a Livingstone College, Virginia State University, and Prairie View A&M University alumnus. “I am a multipreneur and have learned that more hands and brains on deck is almost always a good thing. I needed to meet and find the right people who could understand, compliment, add value, and who could see the potential just as much as I could. Also, I promised myself no more solo projects. When you are involved in as many businesses and organizations as I am, being able to spread the load is vital to success – and sanity.”

Enter Christen Turner, Spelman College and Southern University alumnus, and Marcus King, an alumnus of Prairie View A&M University, both HBCUpreneurs themselves. Ms. Turner, HBCU Real Estate’s Chief Technology Officer, also owns Janelle T. Designs, a graphic designs firm, as well as Forever Femme, an accessories company. Mr. King, HBCU Real Estate’s Chief Marketing Officer, owns Hardly Home, a clothing line that is catered towards travel that was featured on HBCU Money’s The HBCUpreneur Corner in 2015. What does it say to you (King) about the potential of collaboration for HBCUpreneurs that 5 different HBCUs are represented among the 3 cofounders? King answered, “The motto at my alma maters is that “PV produces productive people” and I think that can be said about HBCUs across the board. For years HBCUs have been producing top talent and should continue to do so as we seek to move forward and provide solutions to the problems our community faces.”

The three have followed each other on Twitter for years, although no one can remember for how long. It was towards the end of 2020 that Foster said he approached Turner and King about doing a collaboration or tweeted at them rather. “I sent out a tweet and tagged both of them saying that I need to cofound something with the two of them. Having watched them over the years I knew we would click and have the same kind of work ethic. I just needed to find out if they thought the idea had any legs. If it was not this, it was going to be something else.” The work ethic was confirmed when he said he got an email from Turner on Thanksgiving while he himself was working. Turner further drove the point home of the potential of the moment, “This business will be successful because of two reasons, respect and trust. Despite not having met in an ‘official’ capacity, our partnership seems to have a natural fit to it; almost like pieces of a puzzle. With William’s intuition, he was able to unknowingly add the right people to his team who would each be able to add something different. Whether from a professional standpoint or specific personality traits, we all came in with an immediate respect for each other’s talents and skills. This is why the business will be successful. There’s no questioning; there’s only action, openness, and honesty.” Usually in Hollywood the movie ends with and they lived happily ever after – The End, but in this case it is clear that this is just The Beginning.

For more information, visit http://www.hbcurealestate.com

5 Things African Americans Have To STOP Saying About Black Businesses

“Negro banks, as a rule, have failed because the people, taught that their own pioneers in business cannot function in this sphere, withdrew their deposits.” – Carter G. Woodson

African American businesses face a lot of hurdles in their ability to get started, grow, and survive. They come from everything from a lack of access to capital, predatory behavior by other communities, and a plethora of other variables that make being an African American entrepreneur not something for weak of heart. However, one of the most formidable adversaries to African American entrepreneurs is the African American community’s perception and attitude towards the very businesses trying to spur economic development in and for the community. 

The HBCU Money staff put together a list of five things they would like to see the community’s behavior and attitude towards African American businesses improve.

5. Can I get the “hookup”?

The goal of a business is to pay for its expenses, pay its workers, and hopefully after all is said and done leave enough money for its owners to have a living. Yet, family, friends, and sometimes strangers seem to think for the African American small business owner or entrepreneur we are the exception to that rule. The “hookup” has been the downfall of many African American businesses. Instead, this is a great opportunity to say how can I hook this business up with more word of mouth advertising so that they can grow and bring jobs and wealth to our community? 

4. Black businesses have bad customer service.

Has an African American store ever followed you around the store? Accused you of stealing before you walk in? Redlined your whole community? The list could go on and on. Yet, you rarely hear us as loud and vocal about customer service from other communities as you do the trope about African American businesses’ customer service. Is there bad customer service? Yes. Is there good customer service? Yes. Like all other communities we run the gambit, but the bad ones whilst a minority tend to get the lion’s share of the perception. Do African American businesses take customer service seriously enough? That is a different question all together, but what is definitely not true is that African American customer service is far worse than the predatory behavior we experience in other community’s businesses. Perspective.

3. Black businesses charge too much.

African American businesses are often accused of charging too much for their product or service. There are a number of factors to this misconception. More times than not African American businesses are in line with the market pricing. However, when they do tend to be higher than the industry, it is because their business is heavily reliant upon an African American consumer or they lack the ability to scale. Being heavily reliant on an African American consumer base is fundamentally economically challenging. We are the group with the lowest median income and wealth, which means we have the least disposable income to be consumers in the mainstream sense. Whereas a consumer in another community maybe able to purchase a product every week, we maybe only able to purchase it every month. For an African American business this forces them to try to capture more sale at once because of how rare the sales will be. We also rarely have the resources to scale our businesses which allows for driving down costs, but again this in large part is because of factors like African American small businesses having less access to capital, businesses too highly focused on African American consumers who have little disposable income, and a concentration in businesses that are often very difficult by their very nature to scale (i.e. restaurants, barber/beauty shops, clothing lines). 

2. Products are inferior.

Outside of food, hair, and entertainment there seems to be a pervasive belief that African American businesses tend to offer subpar products and services. To Dr. Woodson’s aforementioned point, it is often in areas where our own community believes we are incapable of competing and doing well in the space that this is so acute. African American businesses tend to try to produce a product that is superior in many cases because they are fighting this perception. However, it should be noted that there is often a disconnect of what should be quality and should not be. Also, if a consumer is buying a knockoff or counterfeit product which is popular in the community, then the expectation needs to be aligned as such. Unfortunately, that is not always the case. 

1. Need to do more for the community.

Before African American businesses can often become profitable they are being asked to give away their products and/or services to the community. A common misconception often that because you own a business, then you must be making money. It can take an average of two to three years for most conventional businesses to become profitable and even that is a tricky statement. Being profitable simply means that your business revenue is greater than your business expense. So for instance, if your businesses expenses are $2,000 and your business earned $2,001, then you are profitable. However, nobody would assume that that businesses is making enough money for its owner to live on let alone even take a salary. In most instances, especially for African American businesses those early years are spent plowing every dollar of revenue back into the business because usually there was little in the way of startup capital provided. It is usually many years before a business can actually support its owner(s) financially. Does this mean African American business owners should do nothing for their community? Absolutely not. In reality many do even when they can not afford to do so, but we are saying that our community needs to be slower to criticize just how much a business should be doing before they have even had a chance to get our their proverbial feet.

At the end of the day, our businesses are trying to compete against sometimes what feels like insurmountable odds. Those odds do not need to be exacerbated by our own community. Holding African American small businesses and companies accountable is one thing, but continuously treating them in a nihilistic manner is a recipe for economic disaster. Economic development strategy has a myriad of components to it and our behavior and attitudes toward our own institutions goes a long way in our ability to become economically empowered.